


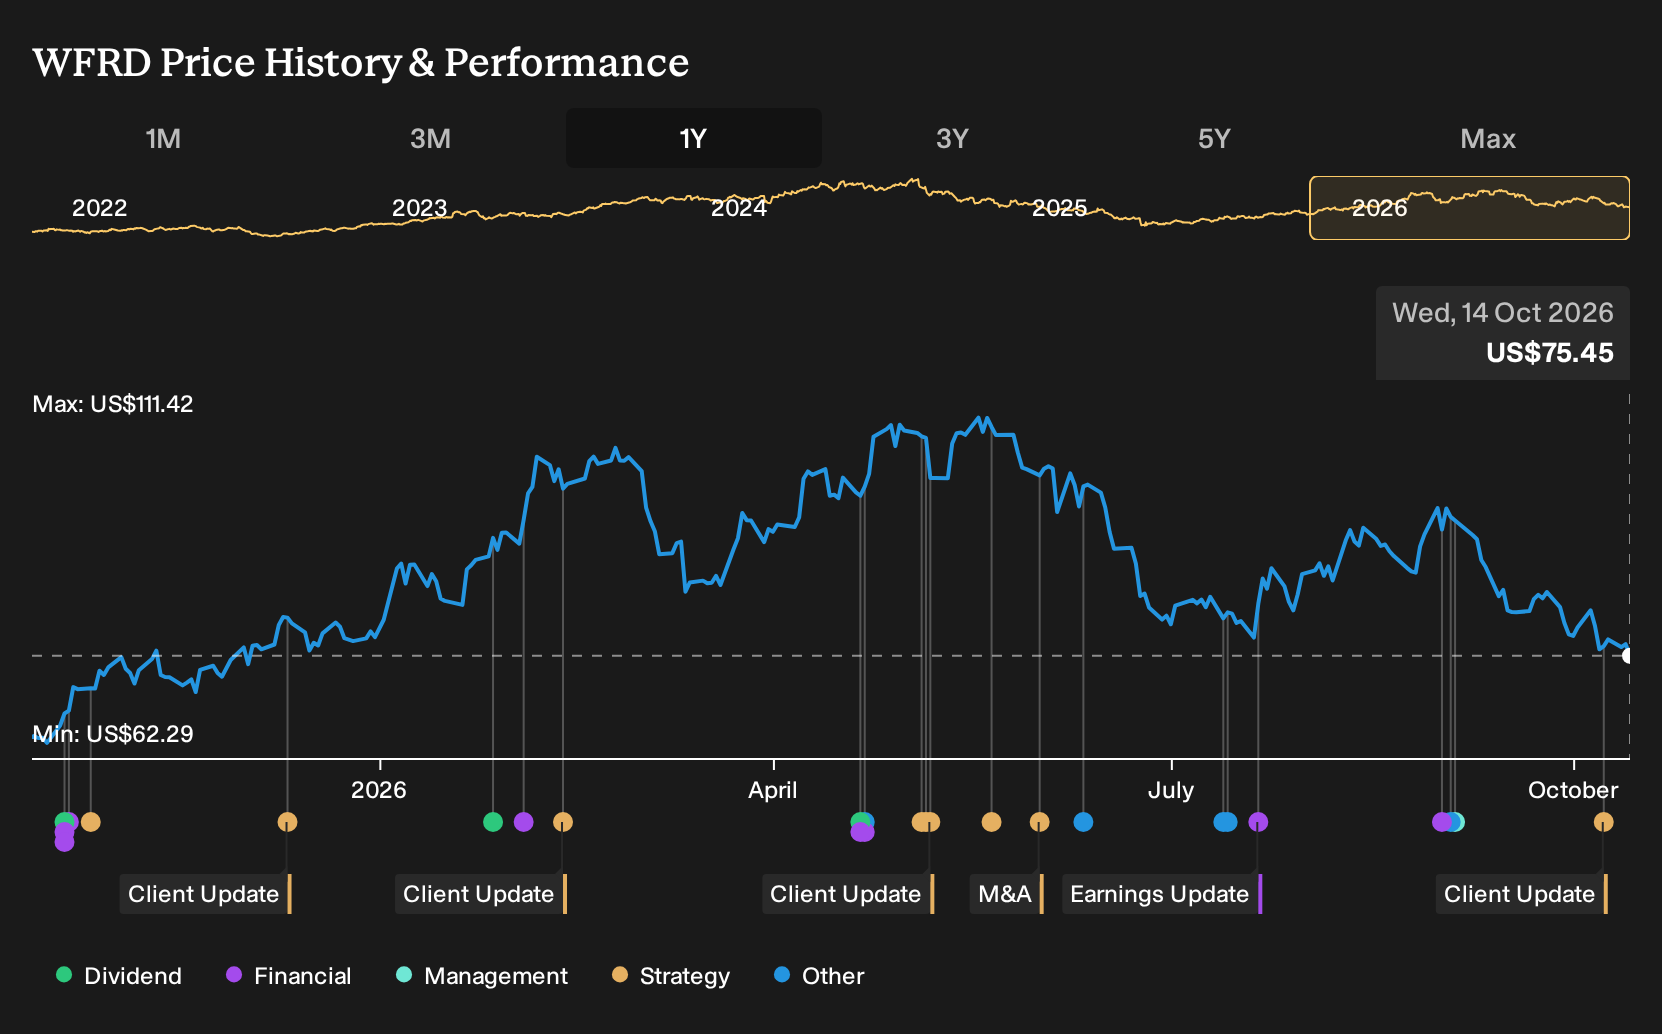
- Weatherford International reported that Equinor granted a two year extension across several frame agreements and named the company primary completion systems provider for the Statfjord and Oseberg licenses on the Norwegian Continental Shelf.
- This expanded Equinor work concentrates more long duration offshore activity into Weatherford International’s higher value completions portfolio, with a sharper focus on operational efficiency, well performance and life of well production support.
- We will now look at how Weatherford International’s expanded Equinor completions role could reshape the broader investment narrative around the business.
Scan offshore energy contractors taking on multi year work, such as Weatherford International’s Equinor extension, by reviewing our hand picked list of 43 power grid technology and infrastructure stocks
Weatherford International Investment Narrative Recap
To own Weatherford International, you need to believe the shift toward higher margin, technology led services like completions and managed pressure drilling can offset regional softness and contract roll offs. The expanded Equinor work fits that story because it leans on completions and long duration offshore activity that can support utilization and pricing in a focused part of the portfolio.
The near term swing factor is execution on earnings and free cash flow against already reduced 2026 guidance ranges. The biggest risk still sits in geopolitically exposed markets and the roll off of the Saudi LSTK contract. This Equinor extension helps mix quality, but does not remove those pressures.
The most relevant datapoint alongside the Equinor news is the upcoming quarterly report, where Weatherford International is expected to post earnings of US$1.21 per share on revenue projected to decline 8.2% year over year. That setup puts attention squarely on margins, contract mix and whether technology driven work is replacing lower quality revenue quickly enough.
Analysts see earnings estimates that are above the broader consensus, but the stock carries a Zacks Rank of 5, which flags uncertainty around a beat. In that context, the Equinor extension acts as a visible operational proof point. It highlights demand for the completions portfolio, while execution on integration, cost discipline and geopolitically exposed projects still defines how the next few quarters land.
Weatherford International's current narrative points to forecast revenue of about US$5.5b and earnings of roughly US$604.9 million by 2029, based on analyst estimates that assume 4.8% yearly revenue growth and an earnings increase of about US$238.9 million from current earnings of US$366.0 million.
Uncover why Weatherford International's fair value indicates a 55% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on Weatherford International focuses on upside from completions heavy offshore contracts like this Equinor extension. The most optimistic analysts were already penciling in revenue of about US$5.6b and earnings near US$623.2 million by 2029. Those forecasts came before this announcement, so your own view might shift as new information lands.
Explore 5 other Weatherford International fair value estimates, including one that suggests as much as 200% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own analysis.
- A great starting point for your Weatherford International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Weatherford International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weatherford International's overall financial health at a glance.
Looking for more investment ideas beyond Weatherford International?
Once you have a view on Weatherford International, it can help to widen the lens and see how other opportunities stack up on quality, balance sheet strength and income potential using the Simply Wall St Screener.
- If you want stability to be front and center, start with a 32 resilient stocks with low risk scores that has resilient fundamentals and lower risk scores.
- For investors who care most about financial strength, compare Weatherford International with our list of solid balance sheet and fundamentals (25 results) to see which businesses pair solid balance sheets with consistent fundamentals.
- If you prefer hunting for less crowded opportunities, use the 20 high quality undiscovered gems to spot underfollowed stocks with strong underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com