


Valvoline has seen its share price grind higher this year despite a weaker 1 year result, which naturally raises the question of whether the current tag around its stock is supported by the earnings the business is generating. For investors watching the recent moves, the key issue is how that earnings picture lines up with what the market is now willing to pay.
- The stock has fallen 13.7% over the past year, so anyone buying today needs to consider whether the earnings profile now justifies stepping in after that kind of drawdown.
- The company leans heavily on its service network and lubricant margins, which can influence how reliably it turns revenue into profit and how much flexibility it has to support future earnings.
- Your read on Valvoline is one view; the desks covering it have another. See what analysts think Valvoline's shares could be worth.
The stock's next move may depend on whether Valvoline's current price looks aligned with the earnings power that its business can realistically sustain.
If you are weighing whether Valvoline's earnings justify its recent move, it can help to compare that trade off with a focused list of 32 high quality undervalued stocks.
Is Valvoline Getting Expensive on Earnings?
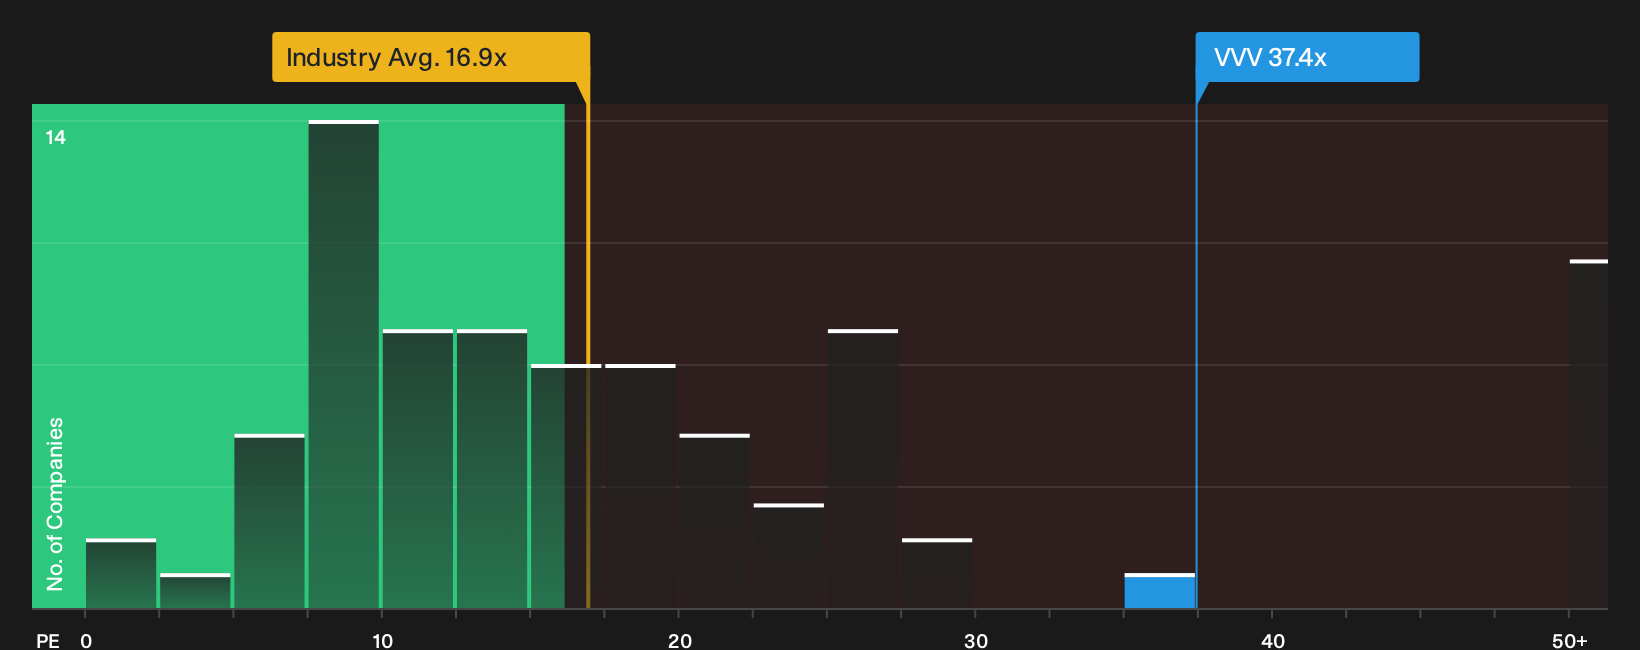
The P/E ratio suits Valvoline because earnings remain a core yardstick for a mature service and consumables business where cash flow is closely tied to net income. On this measure the stock trades on roughly 37.4x earnings, which is well above the Specialty Retail sector average of about 16.9x and comfortably higher than the peer group near 7.6x. That sort of gap indicates the market is attaching a premium to the company’s earnings stream compared with many other retailers.
The fair value framework that blends Valvoline specific factors, including its margins, balance sheet profile and risk, points to a lower P/E than where the shares currently change hands. The present multiple therefore sits above what that tailored model suggests would be a more balanced price tag, so anyone buying here is implicitly accepting a richer earnings valuation and needs to decide if the business quality justifies that premium. Explore the numbers behind Valvoline's P/E valuation.
The Valvoline Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Valvoline leaves off by spelling out what kind of future growth, margins and earnings profile would need to play out for the stock to be worth materially more or materially less than it is today, all housed on the Community page. Rather than relying on a single multiple or model, each scenario lays out the assumptions behind its view of fair value so you can track those against Valvoline's actual results over time.
One of the top community narratives on Valvoline: 30% undervalued
"The current valuation implies the share price does not fully reflect the company’s view that its resilient demand, store growth pipeline, premium oil mix, and cash generation support a positive investment narrative for Valvoline…"
Discover why this Narrative puts Valvoline at 30% undervalued.
One more angle on Valvoline that could reshape the picture
Valvoline’s valuation only tells part of the story because the people setting priorities, approving capital allocation and choosing where profits go also matter, along with how their pay packages are structured. See who runs Valvoline and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com