


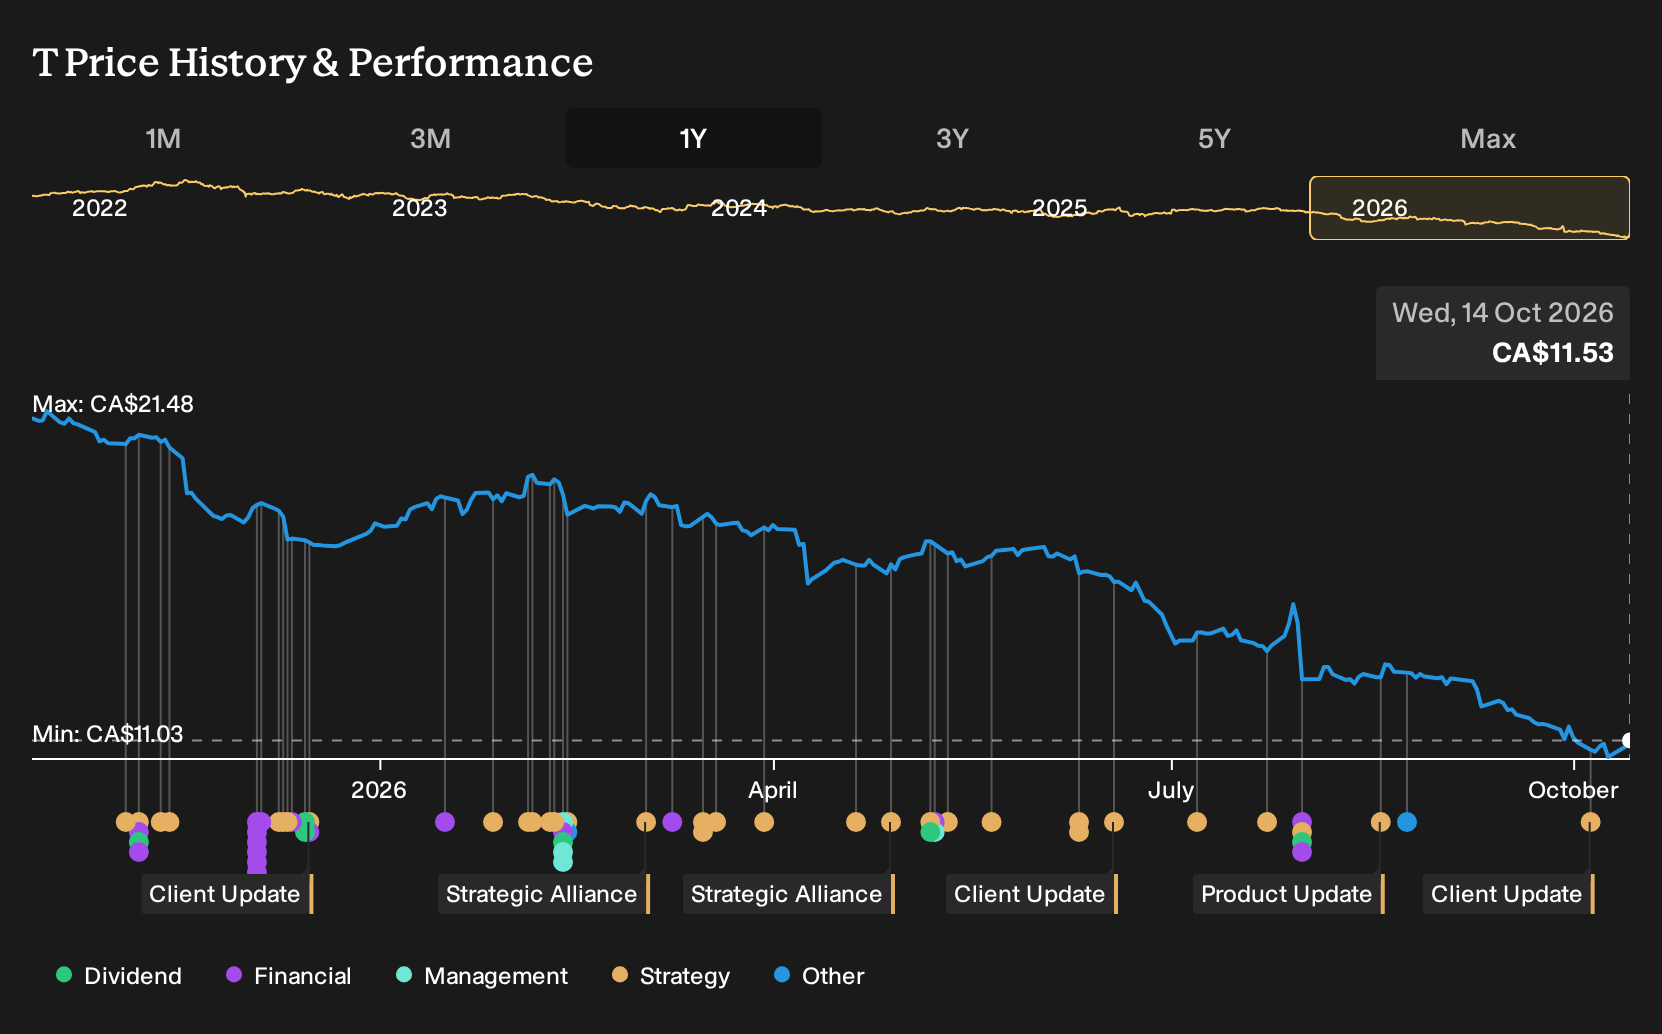
- On 14 October 2026, TELUS Digital announced a partnership with Parloa, combining Parloa's European AI CX and GDPR experience with TELUS Digital's regulated-industry delivery footprint across North America and Europe to implement Parloa's AI agent platform for large enterprises.
- The Parloa collaboration gives TELUS Digital another AI customer experience tool that can support higher value CX automation work across sectors such as telecom, banking, retail and healthcare, while using TELUS's global delivery workforce of more than 83,000 people in over 35 countries.
- This article examines how TELUS's investment narrative intersects with the Parloa AI customer experience partnership and its higher value digital mix.
TELUS Investment Narrative Recap
To own TELUS, you need to believe the telecom network, health and digital units can collectively turn today’s pressure on earnings, free cash flow and leverage into a steadier, cash generative profile by 2028. The Parloa AI CX deal leans into that idea, since it points TELUS Digital further toward higher value automation and data work.
The biggest near term swing factor remains execution on cost discipline, capital intensity and asset monetization to support debt reduction after weaker 2026 guidance. The main risk is that revenue softness, faster churn in legacy digital services or slower CXAI scaling leave leverage elevated for longer. The Parloa news does not materially change that risk balance yet.
The recent space based connectivity progress with AST SpaceMobile is the other development worth keeping on the radar beside the Parloa partnership. TELUS and AST completed an integration test between TELUS wireless infrastructure and AST’s Low Earth Orbit network that supported broadband data, voice and text directly between smartphones and satellites.
For TELUS, that trial speaks directly to the core telecom catalyst investors are watching, which is using a largely built out PureFibre and 5G footprint more efficiently rather than spending heavily on new builds. Satellite interoperability could extend coverage while keeping focus on capital discipline. The operational risk is straightforward. Turning a successful test into a reliable commercial service at scale will demand tight execution, clear device eligibility and careful management of potential cost and reliability questions from customers.
What the TELUS AI and Connectivity Story Assumes
TELUS' narrative projects CA$20.3b revenue and CA$2.0b earnings by 2029. This rests on revenue staying broadly flat each year and an earnings swing of about CA$2.9b from a loss of CA$919.0m today.
Uncover why TELUS' fair value indicates a 22% potential upside to its current price. This upside could narrow quickly if TELUS executes on its AI and connectivity plans.
Exploring Other Perspectives
Some of the most optimistic analysts already framed TELUS as an AI heavy story, assuming revenue of about CA$21.0b and earnings of roughly CA$1.9b by 2029. You might read the Parloa news and wonder if those AI assumptions now look conservative or stretched. Views differ widely, so explore several angles before deciding.
Explore 6 other TELUS fair value estimates, including one that suggests as much as 205% potential increase from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your TELUS research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TELUS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TELUS' overall financial health at a glance.
Looking for more investment ideas beyond TELUS?
If the TELUS story has sharpened your thinking about AI, connectivity and cash generation, you can use that same framework to filter other opportunities. The Simply Wall St Screener lets you move quickly from theory to a shortlist that actually fits your risk profile and income needs.
- For investors who want a balance of quality and a margin of safety, review a 7 high quality undervalued stocks that already pass strict fundamental checks.
- If capital preservation sits near the top of your priority list, start with 8 resilient stocks with low risk scores that score well on resilience metrics and business stability.
- Income focused readers who care about consistent cash payouts can scan a 3 dividend fortresses that combine higher yields with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com