


Workday (WDAY) has just loaded up its product pipeline with a cluster of generative AI launches and partnerships, including Autopilot Agents, Decision Intelligence, Work Intelligence, a headless Trusted Agent Platform, and a new tie-up with Anthropic.
For investors watching the tape, Workday’s recent AI push arrives after a mixed run in the stock, with a 90‑day share price return of 29.8%, a year‑to‑date share price decline of 8.27%, a 1‑year total shareholder return that is down 19.59%, and a 5‑year total shareholder return that is down 31.92%.
Scan how Workday’s AI push compares with other agents-and-automation plays by sizing it up against 92 AI infrastructure stocks that are shaping the next wave of enterprise workflows.
Workday’s AI announcements arrive at a time when its share price has seen movement in both directions. Are investors now re-rating the stock on fresh enthusiasm, or are they finally catching up with the underlying business reality?
Most Popular Narrative: 66% Undervalued
Workday last closed at $188.77, while the leading narrative fair value sits at about $550 per share, implying a wide gap between price and what that framework suggests the business could be worth on its cash flows.
The multi-year path this points toward is incremental, not speculative: existing customers expand into agent-based workflows on top of subscriptions they already pay for, backlog continues converting into recognized revenue at a predictable pace, and margin continues widening as the AI investment amortizes across a larger revenue base. The risk case, agents replacing rather than expanding the relationship, remains possible, but nothing in this quarter's filing supports it happening yet.
See why 17 investors see Workday as 66% undervalued.
Result: Fair Value of $550.10 (UNDERVALUED)
Still, the Workday narrative hinges on AI agents adding revenue rather than replacing core HR and finance subscriptions, and on margin guidance holding up if AI spend rises.
Find out about the key risks to this Workday narrative.
Another View: What Workday’s P/E Is Saying
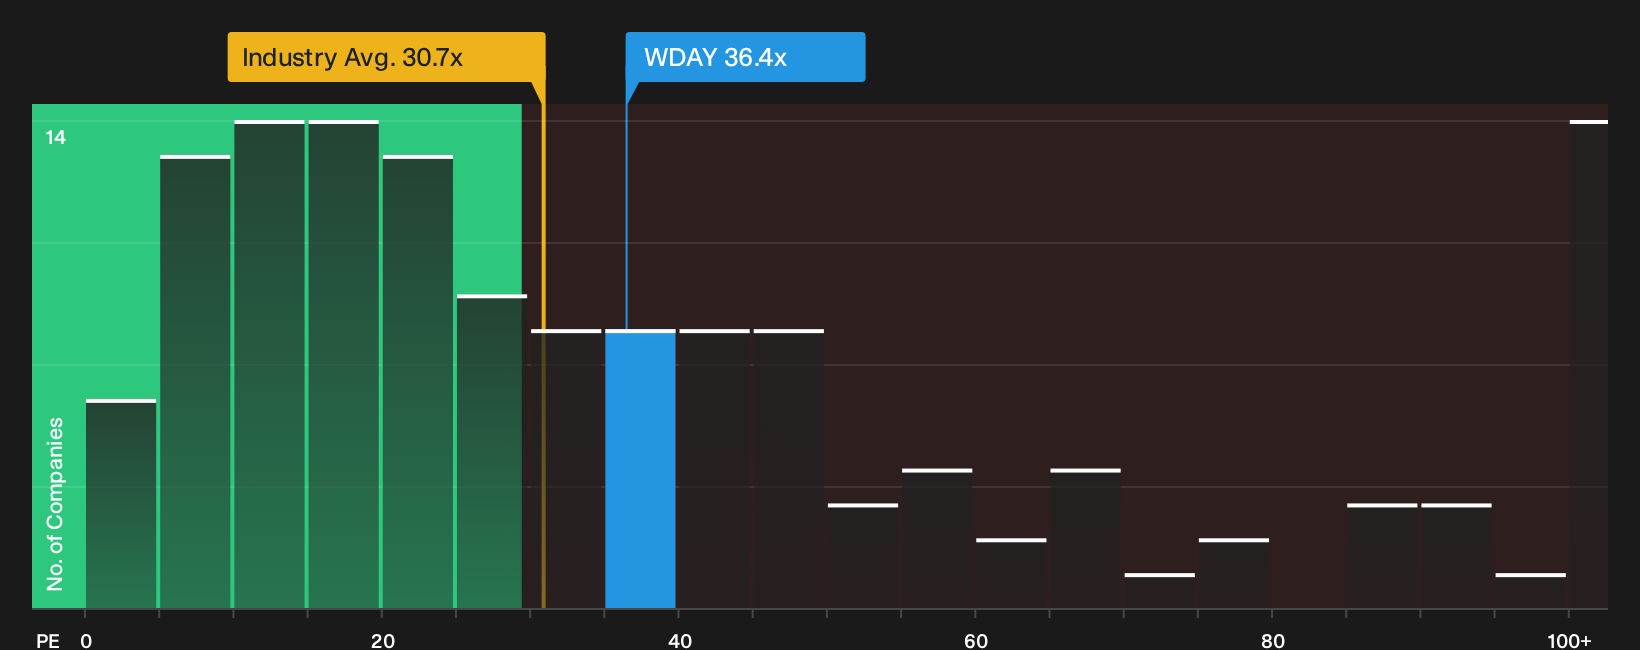
On price tags, Workday tells a different story. The stock trades at a P/E of 36.4x, compared with 17.7x for peers and 30.7x for the wider US Software group, while the fair ratio points to 37.1x. That leaves only a slim cushion. Is that enough comfort if sentiment turns again?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big claims about Workday’s potential are one thing. Running your own numbers is another, so move quickly, test the assumptions, and weigh the 3 key rewards.
Looking for more investment ideas beyond Workday?
If Workday has sharpened your thinking, do not stop there. Broaden your watchlist now and give yourself more ways for your research to pay off.
- Target potential mispricing by scanning for quality companies trading below estimated value through the 32 high quality undervalued stocks.
- Build a steadier income stream by reviewing the 7 dividend fortresses that combine higher yields with business durability.
- Dial down portfolio stress by focusing on the 32 resilient stocks with low risk scores that score well on financial resilience and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com