


AAON (AAON) is back in focus after the heating and cooling manufacturer joined other major HVAC producers in asking a federal judge to dismiss a price-fixing class-action lawsuit tied to equipment sales since 2020.
Recent trading shows that AAON shares have been under pressure, with the 1-day share price return down 6.57% and the 7-day share price return down 7.57% following the lawsuit headlines. At the same time, the 3-year total shareholder return of 51.81% and 5-year total shareholder return of 75.65% still point to a materially stronger longer run record than the past year, where total shareholder return declined 22.43%.
Scan beyond AAON and see how other HVAC and capital goods players under legal or pricing pressure are trading across our hand-picked 32 resilient stocks with low risk scores.
AAON now trades at a steep discount to both analyst targets and intrinsic value estimates after the lawsuit hit the stock. Is that a bargain, or a warning sign for valuation work next?
Most Popular Narrative: 40.2% Undervalued
On the latest numbers, AAON closed at $80.53, while the most followed narrative pegs a fair value at $134.75. This implies a sizeable valuation gap built on ambitious growth and cash flow expectations.
The main thing that has to go right is that AAON turns rapid BASX data center growth, AAON brand share gains, and heavy capex into sustained margin expansion and stronger free cash flow, despite recent gross margin pressure and historical negative free cash flow.
The numbers imply the market is pricing AAON as if current margin compression, high reinvestment, and the recent 17.4% share price decline are bigger risks than the potential upside from BASX capacity of more than US$2b and the doubled company-wide backlog.
See why 7 investors see AAON as 40% undervalued.
Result: Fair Value of $134.75 (UNDERVALUED)
Still, the AAON story leans heavily on BASX data center execution and on reversing gross margin pressure. Setbacks on either front could quickly challenge that 40.2% undervalued narrative.
Find out about the key risks to this AAON narrative.
Another View: AAON Through The P/E Lens
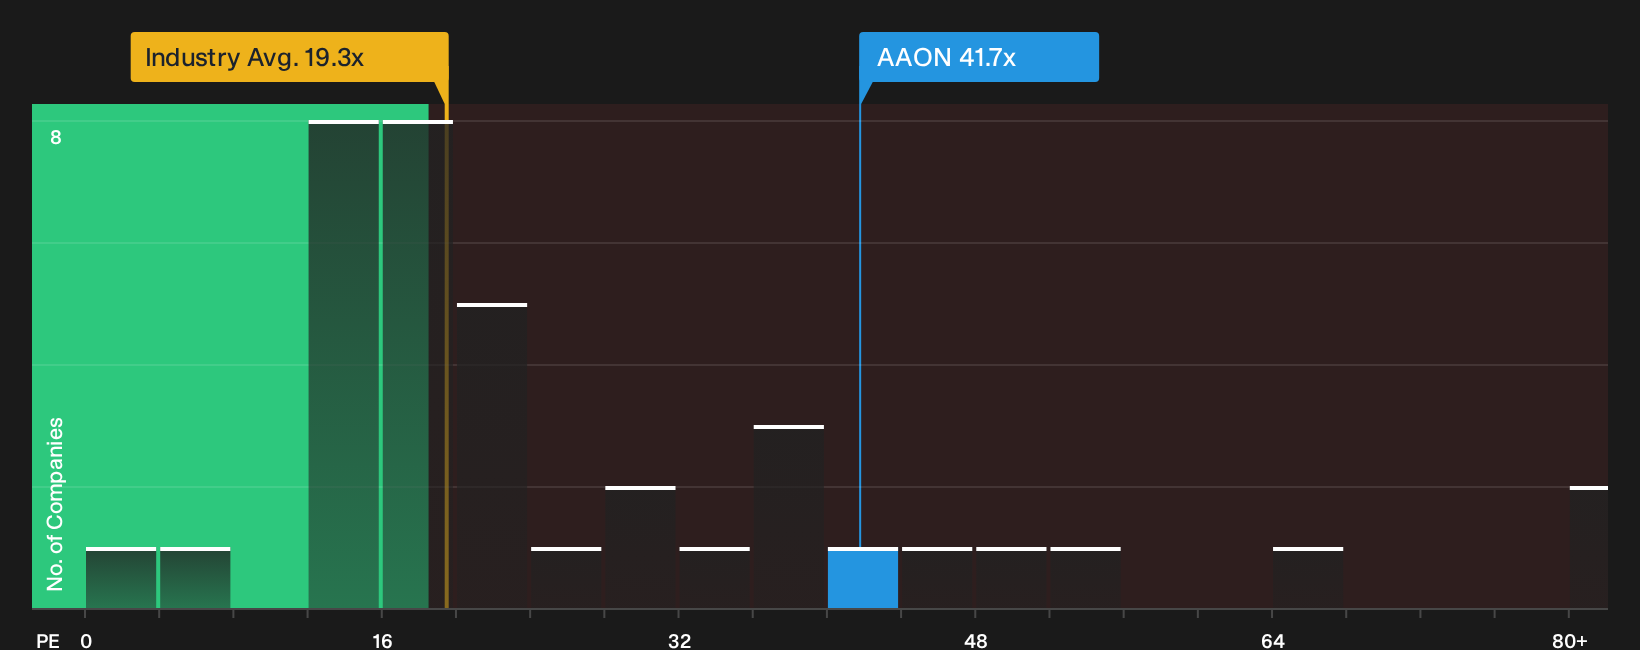
That 40.2% undervalued fair value on AAON clashes with what the earnings multiple is saying. The stock trades on a P/E of 41.7x, while peers average 31.8x and the US Building industry sits at 19.3x. A fair ratio of 47.6x suggests potential upside, but also a higher valuation risk. Which signal do you trust more?
For a closer look at how this earnings multiple compares across peers and the fair ratio trend, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about whether AAON’s recent slide and valuation gap point to opportunity or risk? Use the data, weigh both sides, and then check the 4 key rewards and 2 important warning signs.
Looking for more AAON-sized investment ideas?
AAON might be your starting point, but your next strong move could come from widening the search with focused screeners that surface different types of opportunities across the market.
Spot potential value candidates before the wider market pays attention by scanning a focused set of 20 high quality undiscovered gems that pair quality fundamentals with quieter publicity.
Lock in income-focused opportunities by reviewing a curated pool of 7 dividend fortresses built around higher yields and an emphasis on durability.
Strengthen the defensive side of your portfolio by filtering for a list of solid balance sheet and fundamentals (25 results) so your capital leans toward businesses with sturdier financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com