The Zhitong Finance App learned that on Thursday, Citibank released an in-depth analysis report on the results of major US banks for the third quarter of 2026. The report points out that the recent weak stock price performance of major US banks stems from the double-edged sword of the market dealing with interest rates remaining high for a long time (higher for longer): high interest rates support banks' net interest income in the short term, but continued high interest rates themselves will inhibit economic growth and put multiple pressures on the banking industry.
Citi explained that the yield curve is flattening and squeezing interest spreads, putting pressure on income prospects for interest rate sensitive fees; rising financing costs are compounded by macroeconomic uncertainty, capital market business prosperity is being questioned, investment banking projects are slowing down, and market transaction volume is declining. Overall, the US banking industry showed a pattern where core business was resilient in the third quarter, but the external market environment continued to tighten, and uncertainty about growth and fee revenue increased.
Revenue is polarized
The pattern of revenue differentiation in the US banking sector in the third quarter was very prominent, and the trend of net interest income and non-interest income was clearly split. Net interest income (NII) has become the core engine for the steady growth of banks, benefiting from continued demand for loans in the real economy, compounded by the repricing of fixed interest rate assets in a high interest rate environment, contributing strongly to the interest business.
On the other hand, the non-interest income sector fluctuated sharply: the wealth management sector showed impressive performance, with asset inflows and asset valuations driving many institutional wealth management businesses to achieve historical results; however, interest rates rose rapidly at the end of the quarter and market uncertainty rose, which significantly suppressed investment banking business and FICC (fixed income, foreign exchange, commodity) transactions, and customer trading activity declined, and new bond issuance and underwriting business cooled down markedly.
Deposit side: Strategy is rational and prudent, no longer aggressive savings grabbing
The large-scale loss of deposits that occurred in the first half of 2023 has subsided, but the migration of deposit structures continues. Funds continue to be transferred from interest-free deposit accounts to interest-bearing accounts, but the pace of migration has slowed down.
The overall deposit size of the industry has remained stable, some banks have achieved slight growth, and banks have maintained core transaction settlement accounts for enterprises and individuals. The deposit beta (the ratio of banks transmitting changes in the Fed's interest rate to savers) has returned to rationality, and deposit pricing pressure is mainly concentrated on large deposit books and high-yield savings products.
Currently, the banking industry's business mentality has changed. Instead of competing for debt by drastically raising deposit interest rates, it is focusing on deepening customer relationships with major banks and relying on more sticky transaction operating accounts to create a long-term, low-cost capital base. At the same time, the market judged that the large-scale transfer of deposits has basically come to an end. Most of the remaining deposits are business operating funds and personal daily settlement funds, which are more sticky; even if the Federal Reserve continues to raise interest rates in the future, the increase in deposit costs will be far weaker than in 2023.
Credit: Active risk reduction, overall credit quality is stable
The key word at the banking sector's credit level this quarter was active risk management rather than passive disposal of bad debts.
Judging from provisions and loan data, the trend of “more accruals than write-offs” is almost common. Major banks added more than $1.2 billion in total accrued reserves this quarter. In the context of the general expansion of loan scale throughout the industry, despite the absolute increase in the size of reserves, loan expansion was faster, and the provision coverage rate of many banks declined slightly. The increase in provision is mainly aimed at pre-risk defense against new investment loans, rather than a significant deterioration in the quality of existing loan assets. Taking Wells Fargo Bank (WFC.US) as an example, loans increased 11% year over year, and credit loss reserves fell from 1.52% to 1.38% of total loans; the increase in JPMorgan Chase (JPM.US) reserves was also due to an expansion in the scale of loans, not a deterioration in the quality of existing assets.
Although the overall consumer and commercial credit indicators in the US are still healthy, and the net write-off rate and overdue rate remain low, almost all large banks have taken the initiative to accrue more credit loss reserves. Commercial real estate, especially the office sector, is still a key monitoring risk point. Banks are also actively managing related exposures, and overall credit quality remains resilient.
Looking at segment segments, commercial credit risks are mostly individual enterprise case risks, and systemic risks are limited; US residents are still the ballast stone of credit, consumer spending remains strong, the quality of credit card and consumer loan assets performs well, and a strong labor market and salary income support residents' ability to repay their debts. However, market-side signals have changed, and credit spreads on high-yield bonds continue to widen, reflecting that the market is beginning to price future credit risk.
Sorting out agency ratings and target prices
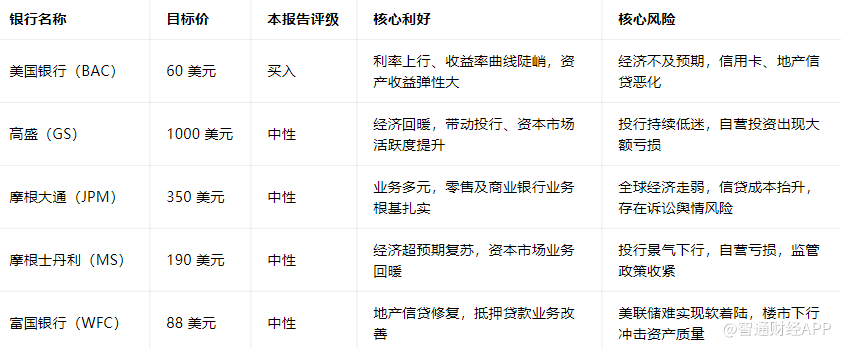
Citi used a discounted surplus income model to value the five leading US banks. It only gave Bank of America (BAC.US) a “buy” rating, while the remaining four institutions gave a “neutral” rating.