


Recent commentary around DXP Enterprises (DXPE) has focused on its revenue growth, expanding free cash flow margin, and steady share repurchases, a combination that is reshaping how investors frame this industrial distributor.
DXP Enterprises' share price has cooled slightly in the short term, with the 1-day move down 2.69% and the 30-day share price return down 0.82%, even as the 90-day gain of 6.54% and year-to-date share price return of 65.53% point to solid momentum. For long-term holders, the picture is even stronger, with total shareholder return of 48.93% over one year and very large gains over three and five years. This suggests that recent commentary on growth, free cash flow and buybacks is being weighed against an already strong run in the stock.
Spot opportunities with similar long-term compounding potential by scanning our curated list of 20 high quality undiscovered gems alongside DXP Enterprises.For DXP Enterprises, that recent cooling in the share price could be the market simply catching its breath after a strong run, or it could hint at sentiment outrunning the underlying business. The valuation section examines that potential tension in more detail.
Most Popular Narrative: 11% Undervalued
Set against DXP Enterprises' last close of $178.31, the most followed narrative pegs fair value at $200, which puts the current share price at an 11% discount and frames the recent pullback as a potential disconnect between price and the long term cash flow story.
The main thing that has to go right is that DXP Water and other higher-value engineered solutions continue to grow as a larger share of sales and margins, while the company manages its leveraged balance sheet and integrates recent acquisitions effectively.
The current valuation implies that the share price already reflects a bullish view that DXP Enterprises is fairly valued on the strength of its margin profile, cash generation and acquisition pipeline.
See why 9 investors see DXP Enterprises as 11% undervalued.
Result: Fair Value of $200 (UNDERVALUED)
Still, heavy debt of US$842.5 million and recent revenue and operating income misses that led to a 14.5% share price drop both challenge the optimism surrounding DXP Enterprises.
Find out about the key risks to this DXP Enterprises narrative.
Another View: Multiples Paint A Richer Picture For DXP Enterprises
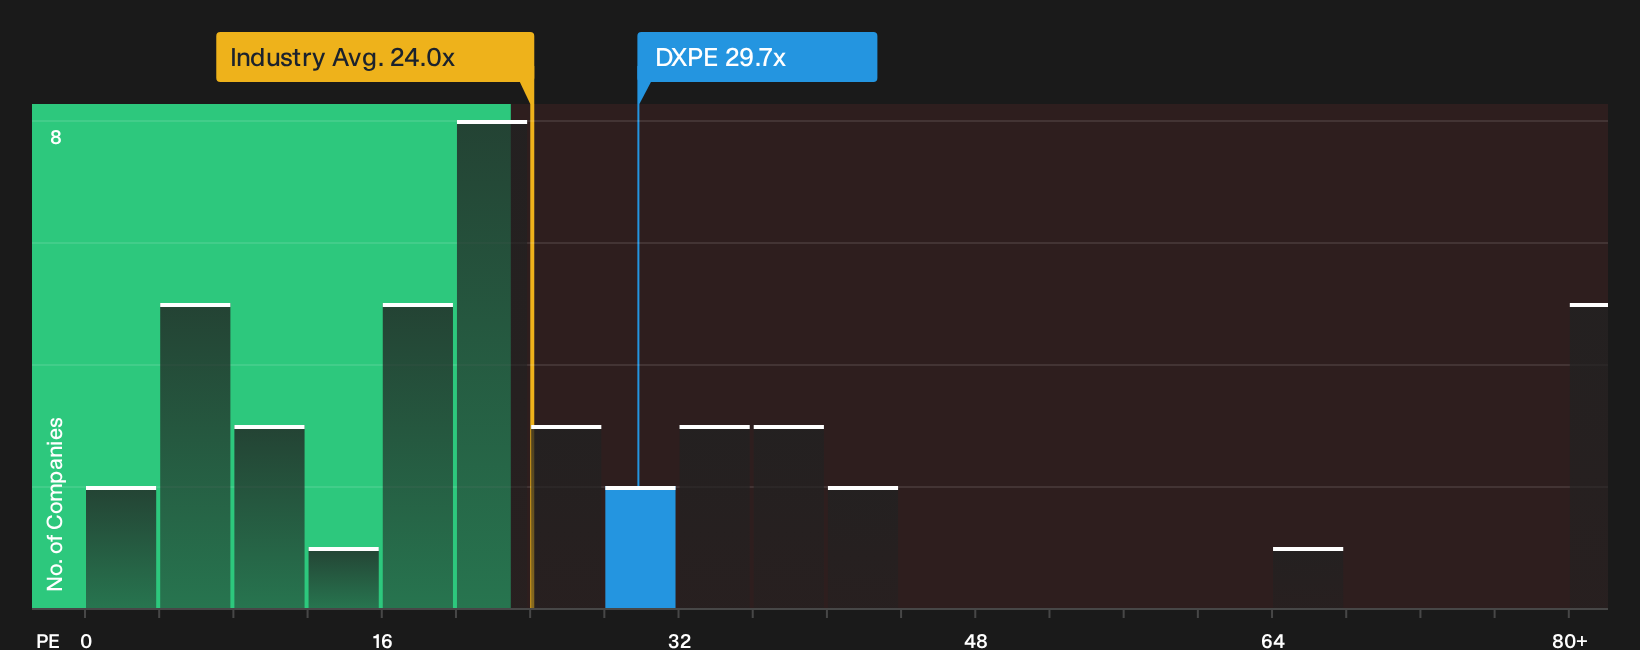
While the SWS model sees DXP Enterprises trading about 11.5% below fair value, the P/E ratio tells a different story. DXPE trades on 29.7x earnings compared with 24.5x for the US Trade Distributors group and a fair ratio of 27.1x. That premium suggests less margin for error if expectations slip.
For a closer look at how that valuation gap stacks up against peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions on DXP Enterprises are clearly split, so do not wait for consensus to form. Instead, check the data and stress test your own thesis using the full breakdown of 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond DXP Enterprises?
If you only stop at DXP Enterprises, you risk missing other setups that could fit your goals even better, so put a few fresh ideas on your radar.
- Target steadier compounding by checking companies on our 32 resilient stocks with low risk scores that pair resilience with controlled risk profiles.
- Prioritise financial strength by scanning the list of solid balance sheet and fundamentals (25 results) for businesses backed by robust balance sheets and fundamentals.
- Hunt for mispriced opportunities with the 32 high quality undervalued stocks and see which stocks the data suggests may trade below their underlying worth.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com