


The Clorox Company (CLX), based in Oakland, California, is a global consumer goods company. It has a market capitalization of approximately $10.2 billion. It manufactures and markets cleaning and disinfecting products, household essentials, personal care items, and wellness products, selling through established brands across more than 100 countries.
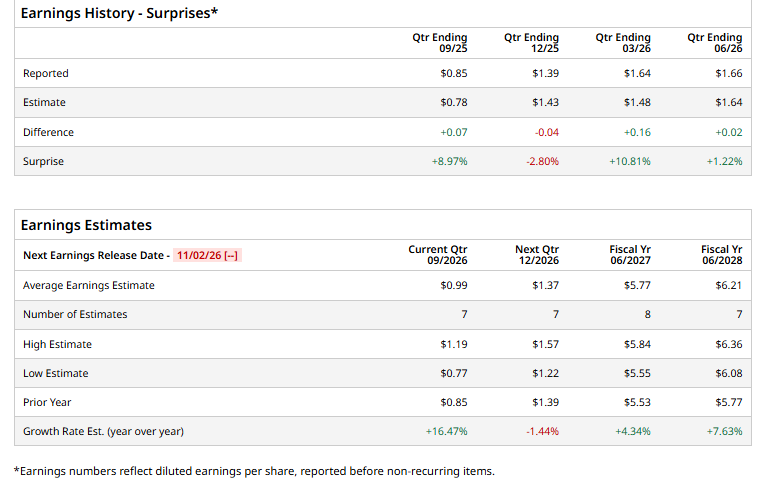
CLX is set to report its Q1 earnings on Monday, November 2, 2026, after the market closes. Ahead of the release, analysts expect the company to report diluted EPS of 99 cents, up 16.5% from 85 cents in the year-ago quarter. Likewise, CLX has exceeded Wall Street’s EPS estimates in three of the past four quarters.
For fiscal 2027, analysts expect CLX to report EPS of $5.77, up 4.3% from $5.53 in fiscal 2025. CLX’s EPS is projected to grow further to $6.21 in fiscal 2028, representing year-over-year growth of 7.6%.
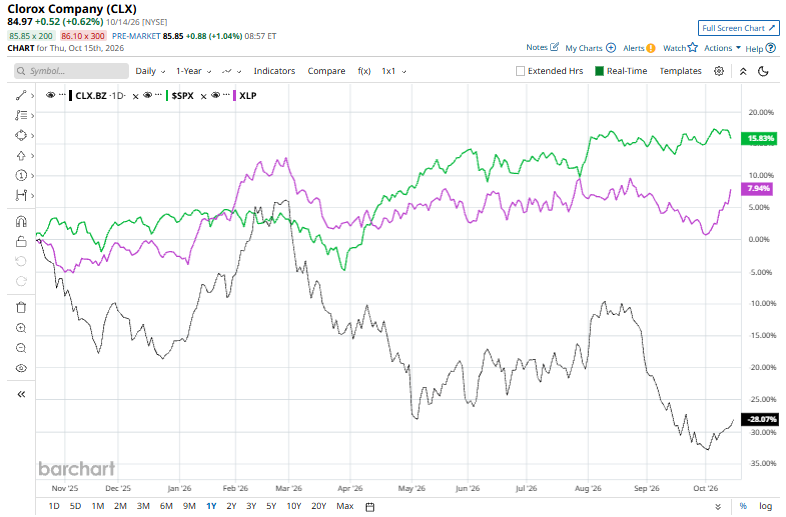
CLX shares have plunged 28.8% over the past 52 weeks, significantly underperforming the S&P 500 Index ($SPX), which gained 16.2%, and the State Street Consumer Staples Select Sector SPDR ETF (XLP), which advanced 8.8% over the same period.
Clorox’s underperformance reflects declining sales, sluggish organic revenue growth, and weakening cash flow generation. Revenue declined at an annual rate of 3.1% over the past three years, while average year-over-year organic revenue growth was just 1.7% over the past eight quarters, lagging the broader sector. Additionally, its trailing 12-month free cash flow margin fell by 4.7 percentage points over the past year to 6%.
Against this backdrop, Clorox officially launched Clorox Purell ProCare on Sept. 28, combining CloroxPro and GOJO, the maker of Purell, following its acquisition of GOJO earlier in 2026. The new business integrates sales, service, and distribution across a broader portfolio of hygiene products for professional and healthcare customers, potentially strengthening Clorox’s position in the professional hygiene market, expanding cross-selling opportunities, and supporting long-term value creation.
Analysts remain neutral on CLX, with a consensus “Hold” rating. Of the 18 analysts covering the stock, 14 recommend a “Strong Buy,” while the remaining four rate it a “Strong Sell.” The average analyst price target of $94.75 suggests potential upside of 11.5% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.