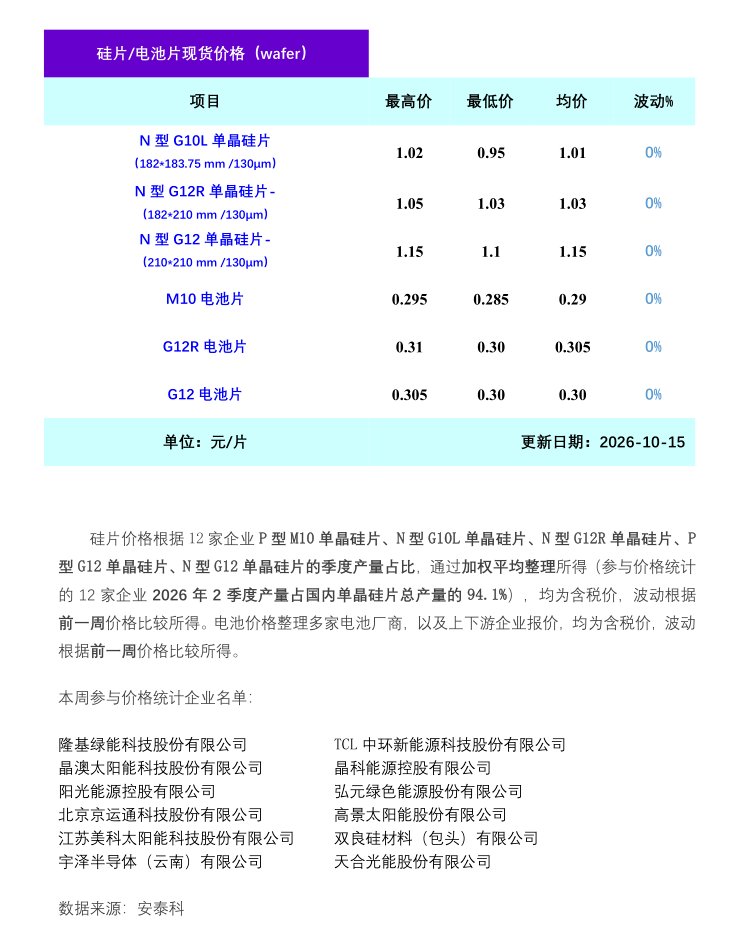
The Zhitong Finance App learned that according to Antec statistics, silicon wafer prices have been running steadily this week. Among them, the average transaction price of N-type G10L monocrystalline silicon wafers (182*183.75mm/130 μm) was 1.01 yuan/piece, the average transaction price of N-type G12R monocrystalline silicon wafers (182*210mm/130 μm) was 1.15 yuan/piece, and the average transaction price of N-type G12 monocrystalline silicon wafers (210*210 mm/130 μm) was 1.15 yuan/piece. The price of each type of silicon wafer remained flat compared to the previous quarter. There has been no significant change in battery prices this week and is relatively stable. Among them, the average transaction price for M10 cells is 0.29 yuan/piece, the average transaction price for G12R cells is 0.305 yuan/piece, and the average transaction price for G12 cells is 0.30 yuan/piece. According to research, module prices have been running steadily for the time being this week. Mainstream component prices are 0.69-0.71 yuan/W, which is the same as before the holiday season.
Market transactions were relatively light after the holiday. Upstream and downstream games were at a standstill, and the overall price of silicon wafers and batteries remained stable. Specifically, in the silicon wafer sector: On the one hand, downstream companies have relatively loose inventories, and mainly buy silicon wafers in immediate demand, price pressure, and small batches; on the other hand, upstream polysilicon manufacturers use full cost as the bottom line. Strong silicon prices provide a certain cost support for silicon wafers, and silicon wafer manufacturers are less willing to cut prices. According to research, the overall operating rate of the silicon wafer industry this week was the same as before the holiday season, with no significant changes. Among them, the operating rates of the two first-tier companies were 52% and 54%, the operating rate of integrated enterprises was between 56% and 60%, and the operating rate of the rest of the enterprises was between 50% and 78%. Cell sector: Although overseas preparation has come to an end, upstream silicon wafer prices have remained stable. At the same time, domestic demand for centralized projects is relatively stable, and rigid demand has replaced the overseas stocking gap. The battery market is relatively stable this week, and prices have been running steadily.
Looking ahead to the future market, the silicon wafer process: Polysilicon price increases bring cost support, and centralized projects release boosts demand. It is expected that the price of silicon wafers will remain stable in the future. Cell sector: According to information, most battery companies cut construction in October, reducing monthly production schedules. With active contraction on the supply side and rigid support from upstream silicon prices, the battery market is likely to operate steadily in the future.