


When prominent value investors establish new positions in beaten-down digital payment pioneers, market participants take notice. Re-entering heavily discounted sector leaders signals growing institutional conviction that operational turnarounds, robust free cash flow generation, and attractive valuations are setting the stage for a compelling long-term recovery.
Reflecting this renewed value thesis, David Einhorn’s Greenlight Capital (GLRE) recently added a new position in PayPal (PYPL).
PayPal Holdings
PayPal is a global digital-payments and fintech company operating the PayPal wallet, Venmo, Braintree, Xoom, and PayPal Credit. The company enables online checkout, peer-to-peer transfers, merchant acquiring, and cross-border payments, serving consumers and merchants while pursuing growth through branded checkout, Venmo monetization, agentic commerce, and AI-driven personalization.
PayPal's Stock Weakens in 2026
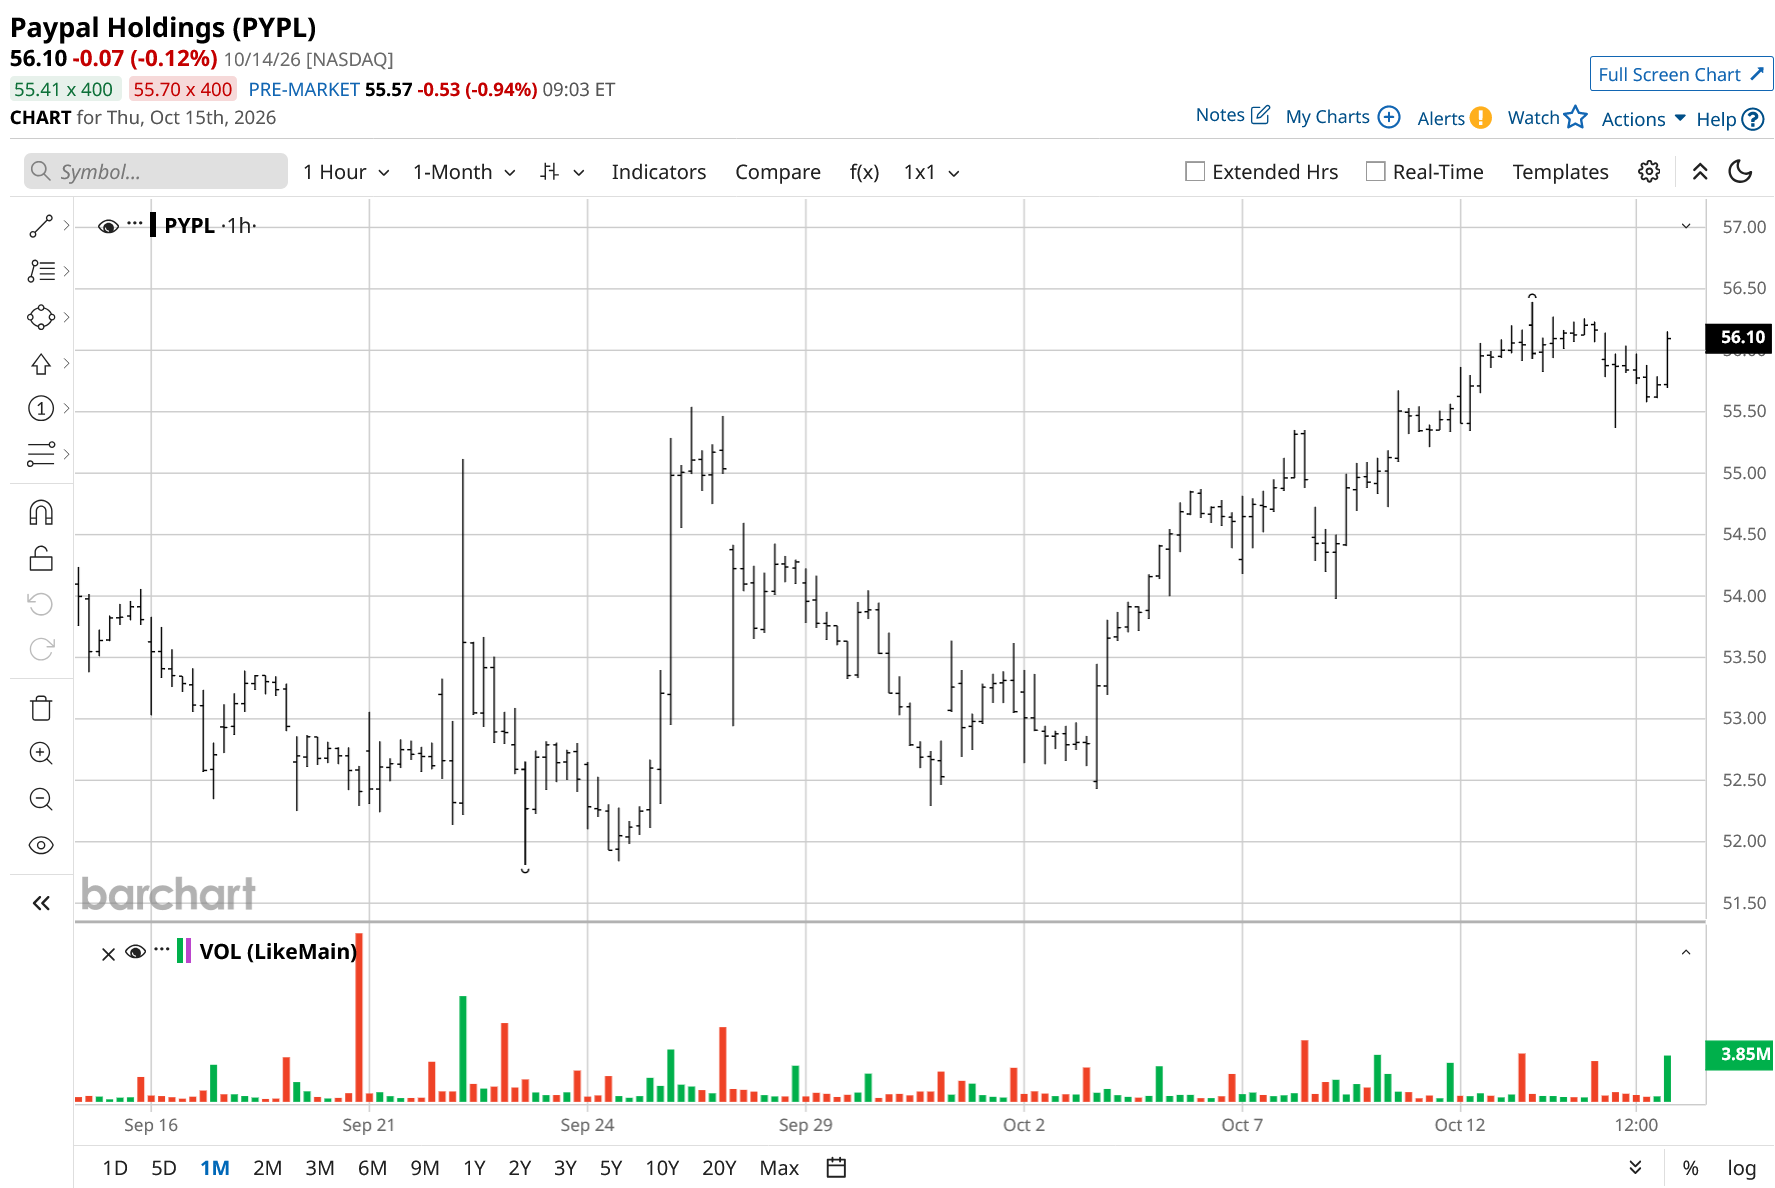
PayPal's stock has lagged the broader market in 2026 despite a recent recovery. PYPL closed at $56.10 on Oct. 14, down 5% year-to-date (YTD) and 19% over the past year. However, the shares gained nearly 3% in October as investors focused on its low valuation, roughly 10 times forward earnings, and a potential re-rating if branded checkout stabilizes and transaction-margin growth improves.
Compared with the S&P 500 Financials Sector ($SRFI), PayPal has underperformed over the past year but recently outperformed the sector during the third quarter. The Financial Select Sector SPDR ETF (XLF) declined 2.52% in Q3, while PayPal surged 17%, aided by merger-and-acquisition speculation and improving sentiment around its checkout business.
Mixed Earnings Results
In its latest reported quarter, PayPal generated revenue of $8.68 billion, up 4.8% year over year and above the Zacks consensus estimate of $8.51 billion. Non-GAAP EPS was $1.38, beating the $1.28 analyst forecast by $0.10, although EPS declined slightly from $1.40 in the year-ago period.
Operationally, total payment volume rose 10% year over year to $486.45 billion, while payment transactions increased 8% to 6.75 billion. Venmo volume grew 14% to $93.81 billion, active accounts reached 439 million, and branded checkout volume rose 2% on a currency-neutral basis, signaling stabilization in PayPal’s core checkout business.
Management raised full-year non-GAAP EPS guidance to $5.38, about 1% above 2025’s $5.31, while maintaining confidence in transaction-margin guidance. For Q3, PayPal expects low-single-digit EPS decline and branded checkout growth of 1% to 2%, with CEO Alex Chriss emphasizing long-term ambitions for double-digit EPS growth as Venmo, advertising, and agentic-commerce initiatives scale.
David Eihnorn Adds PYPL
David Einhorn’s Greenlight Capital added PayPal as a new long position in Q2 2026, signaling a value-oriented bet on the payments platform’s turnaround potential. Greenlight acquired its PYPL stake at an average price of $43.53, arguing that PayPal’s more than 400 million active customers and collection of payment assets were undervalued at roughly eight times earnings.
The fund sees opportunity after the stock sold off following weak Q4 results and a CEO transition, despite competition from Apple (AAPL) Pay, Shop Pay, and Buy-Now-Pay-Later (BNPL) services. The PayPal position represented about 1.6% of Greenlight’s portfolio, or approximately $62 million.
While Greenlight’s funds returned -4.3% in Q2 and trailed the S&P 500’s ($SPX) 15.2% gain, its PayPal purchase reinforces the view that PYPL could be a compelling contrarian fintech investment if branded checkout, Venmo monetization, and transaction margins improve.
Should You Buy PYPL Stock?
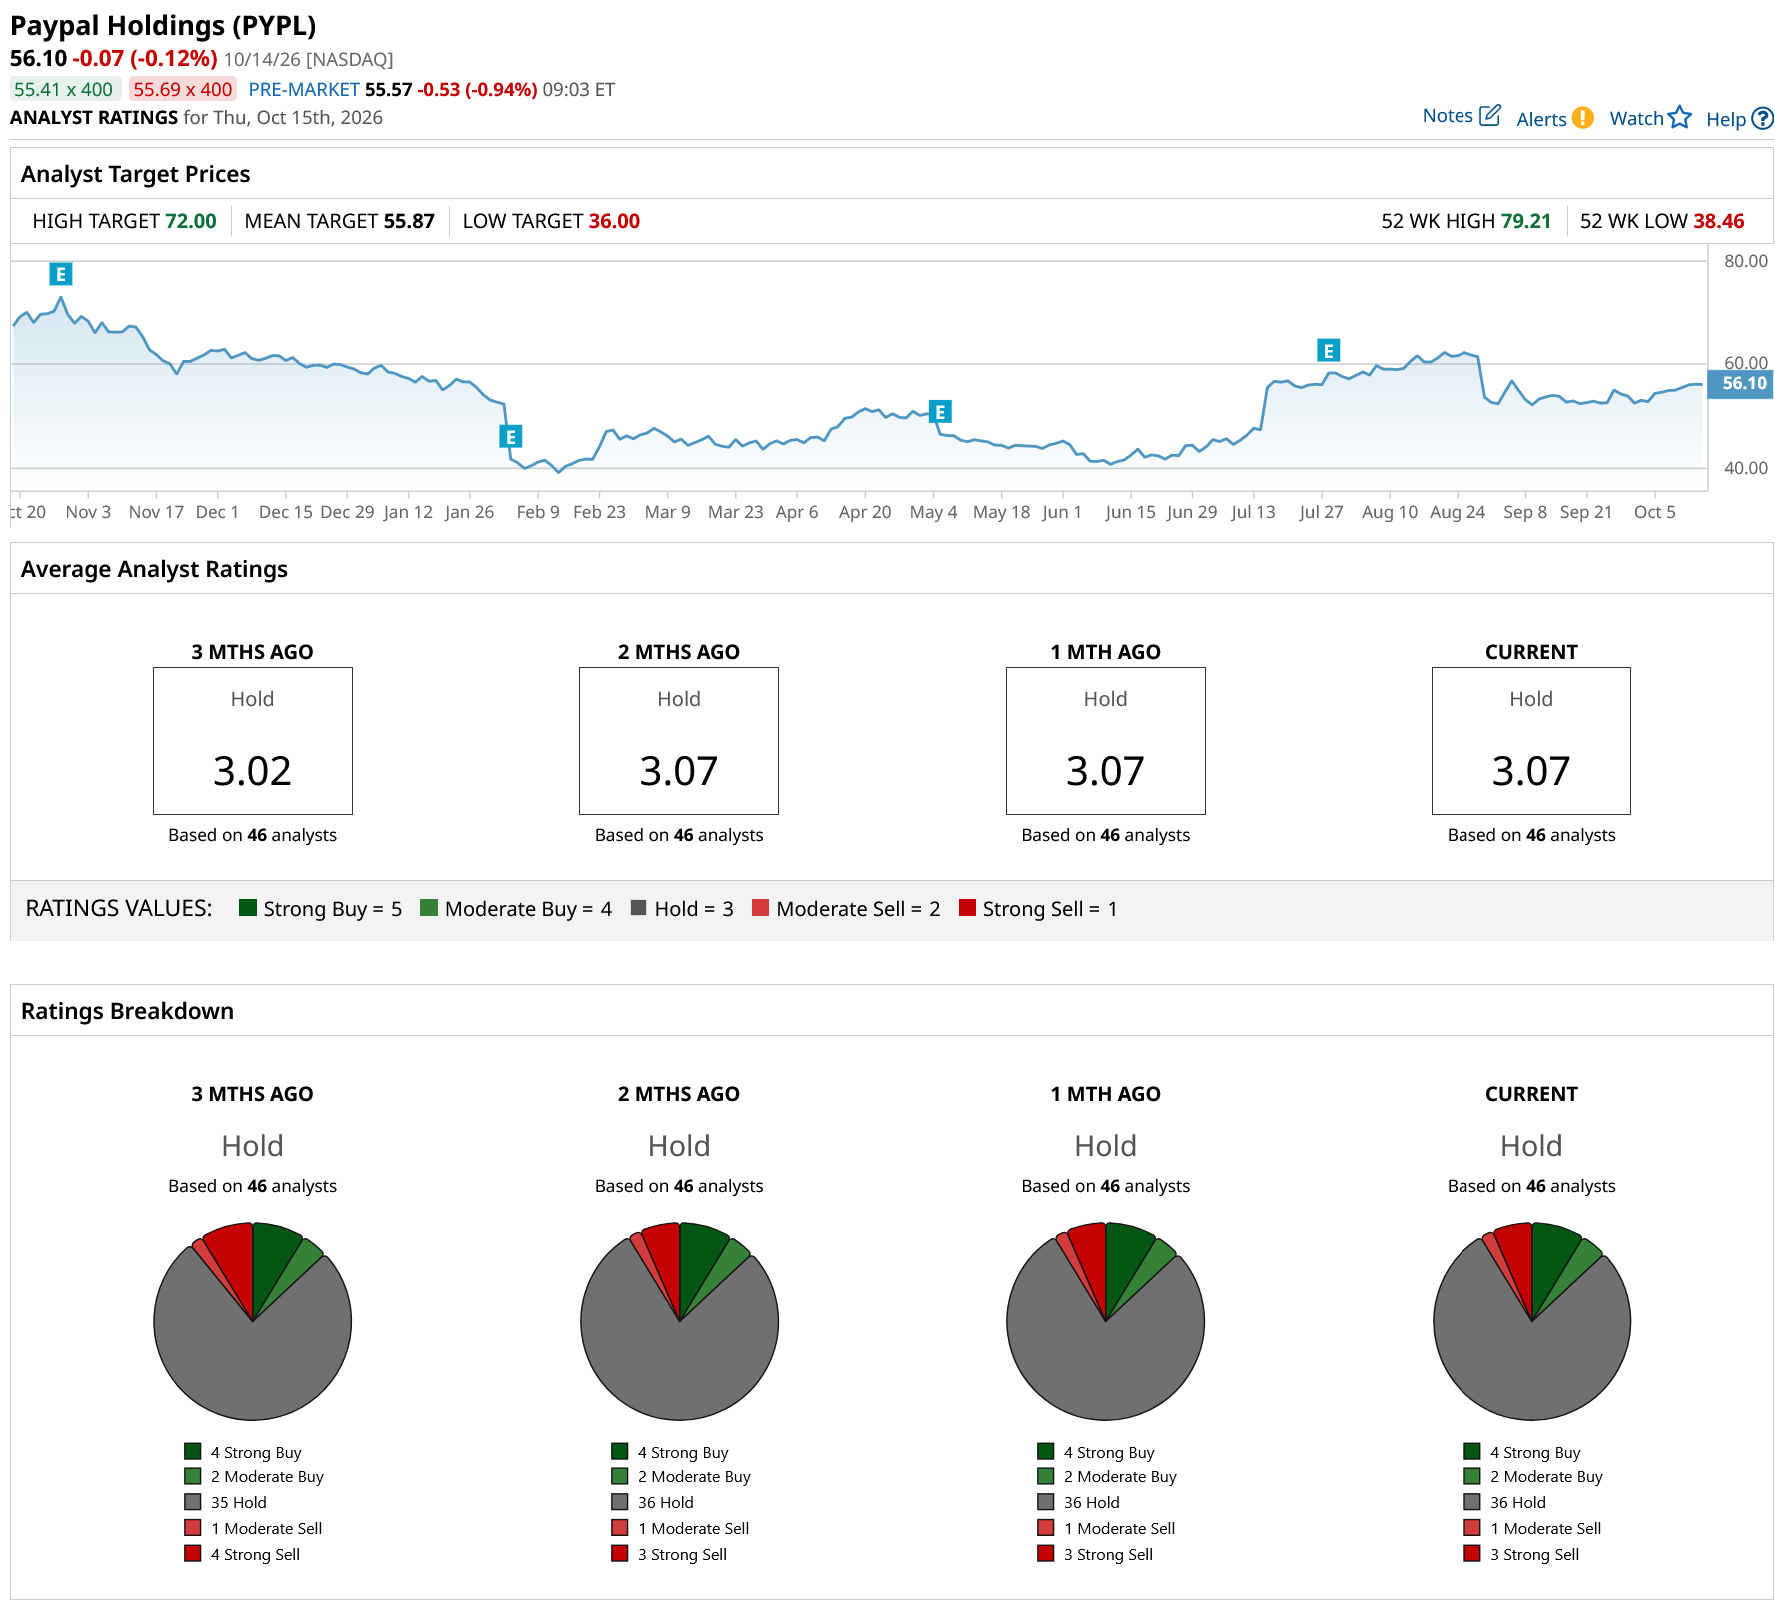
PYPL stock is a cautious buy rather than a clear one. Its “Hold” consensus, $55.87 average price target, and limited upside suggest Wall Street sees the stock as fairly valued despite its low earnings multiple. However, David Einhorn’s Greenlight Capital stake adds credibility to the turnaround thesis, particularly if branded checkout, Venmo monetization, and transaction margins improve. PYPL may suit patient value investors, but near-term execution remains essential.
On the date of publication, Ruchi Gupta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.