


Kroger (KR) is back in focus after Albertsons moved to recover at least US$8b in damages and a break-up fee related to their failed 2022 merger agreement.
The legal fight with Albertsons has put Kroger back in the headlines just as the stock has picked up short term momentum, with a 1-day share price return of 3.9% and a 7-day share price return of 6.5%. However, the 1-year total shareholder return is still down 6.6%, even after solid 3-year and 5-year total shareholder returns of 52.5% and 78.8%, which point to a much stronger longer term record.
Scan how Kroger compares with other large retailers building momentum after legal or corporate shakeups by reviewing the hand picked list of solid balance sheet and fundamentals (25 results) in the sector.
Kroger has just sprinted higher while still showing a weaker 1 year record. Do you lean into this rebound now, or wait for the valuation to blink first?
Most Popular Narrative: 3.9% Undervalued
Kroger last closed at $63.09, while the most followed narrative on the stock pegs fair value at $65.65. That gap is small in price terms, but the reasoning behind it leans heavily on how management is trying to rebuild the business model rather than just chase near term sales.
The central narrative tension of the latest call is the gap between two clean stories: cost discipline working exactly as committed, and the sales line missing the guidance range. Foran’s response was to present these as compatible, a demonstration that the financial model works even when top-line conditions don’t cooperate. “These results demonstrated the strength and flexibility of our operating model in a challenging sales environment” was the direct formulation. This is a real argument, not a deflection, because the cost savings mechanism did hold. But the argument requires the listener to accept that a sales miss is a stress test passed rather than a signal worth investigating on its own terms.
See why 1 investors see Kroger as 4% undervalued.
Result: Fair Value of $65.65 (UNDERVALUED)
Still, the Kroger narrative can break if cost cuts start to fatigue just as identical sales stay soft, or if legal outcomes materially change cash priorities.
Find out about the key risks to this Kroger narrative.
Another View: What Kroger’s P/E Is Telling You
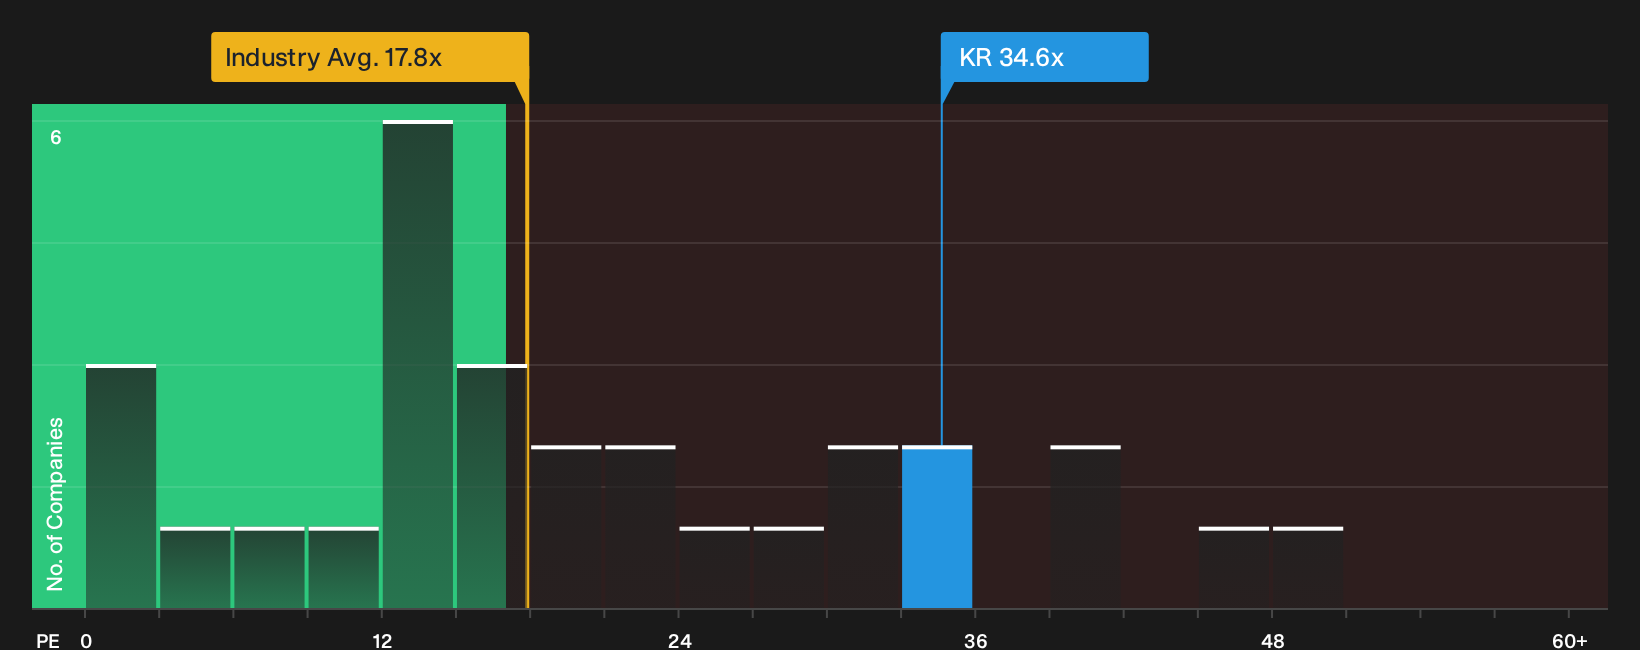
The story changes once you look at Kroger through its P/E. The stock trades on 34.6x earnings, while the US Consumer Retailing industry sits at 17.8x and peers at 21.5x. The fair ratio is 30.5x. That richer multiple can mean investors carry more valuation risk if sentiment cools.
For a closer look at how this pricing gap lines up with earnings power and sector norms, take a look at our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this combination of legal risk, valuation premium, and recovery discussion seems conflicted, consider quickly evaluating the trade off for yourself using the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Kroger?
If Kroger’s setup has you thinking about portfolio upgrades, use this momentum to refresh your watchlist with a few focused screens that surface different types of opportunities.
- Target potential mispricings by scanning 32 high quality undervalued stocks that combine quality fundamentals with prices that lag behind their underlying financial strength.
- Build a more resilient income stream by reviewing 7 dividend fortresses that concentrate yield and balance sheet support in the same ticker.
- Dial down portfolio stress by focusing on 32 resilient stocks with low risk scores that score well on stability and financial robustness before the crowd pays closer attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com