


Recent commentary around SolarEdge Technologies (SEDG) has shifted toward policy and macro headwinds, including the expiration of the 30% homeowner solar tax credit and new polysilicon tariffs raising cost and financing pressure.
SolarEdge Technologies’ share price has come under pressure, with a 1-day share price return of down 6.18% and a 90-day share price return of down 41.69%, while the 1-year total shareholder return of down 24.70% and 5-year total shareholder return of down 90.07% point to fading momentum as investors weigh policy headwinds, executive turnover, and the upcoming third quarter results.
Scan beyond SolarEdge Technologies and pressure-tested residential solar players by reviewing 43 power grid technology and infrastructure stocks, which may benefit as grid upgrades and on-site generation stay in focus.
SolarEdge Technologies now trades near multi year lows after a sharp reset, so the key issue is whether the meaningful repricing leaves more recovery ahead or if most of the easy upside already sits in the rear view.
Most Popular Narrative: 20.6% Undervalued
Against a last close of $30.52 for SolarEdge Technologies, the most followed valuation storyline points to a fair value of $38.45, which frames today’s policy and margin debate through a higher long term earnings lens.
Investors may be expecting margin expansion to accelerate as U.S. manufacturing ramps and global exports increase, but persistent elevated tariffs, increasing input/output volatility (such as the loss of natural EU FX margin "hedge" when exporting from the U.S.), and ongoing product mix headwinds threaten to compress gross margins and limit earnings growth.
See why 56 investors see SolarEdge Technologies as 21% undervalued.
Result: Fair Value of $38.45 (UNDERVALUED)
Still, extension of U.S. manufacturing tax credits and faster battery storage adoption could undercut the bearish case and strengthen SolarEdge Technologies’ longer term earnings narrative.
Find out about the key risks to this SolarEdge Technologies narrative.
Another View: SWS DCF Says Slightly Overvalued
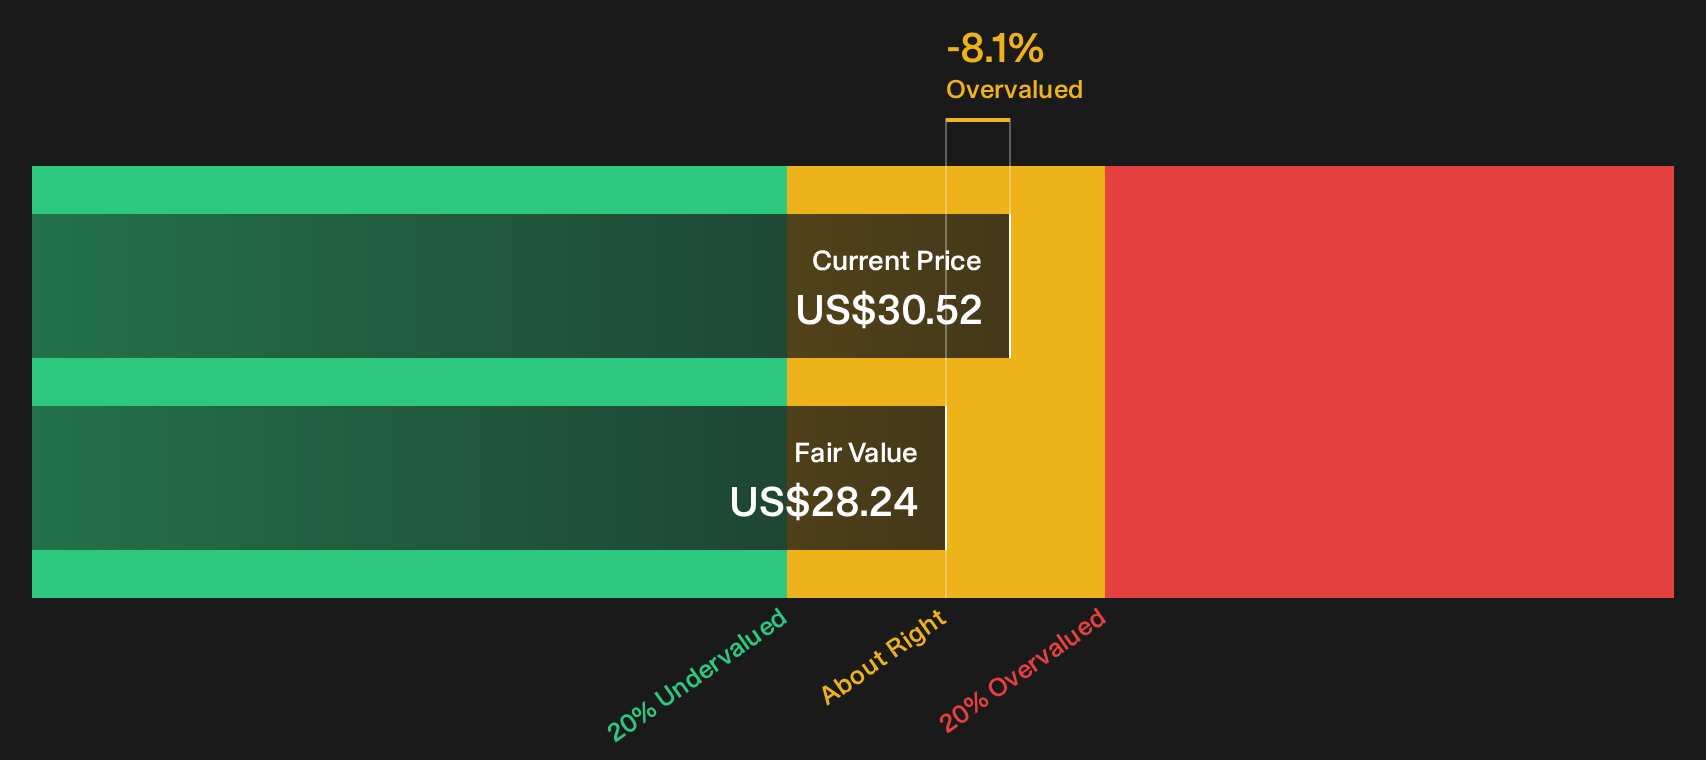
The popular narrative tags SolarEdge Technologies as 20.6% undervalued, yet the SWS DCF model points the other way. On that cash flow view, SEDG at $30.52 sits above an estimated value of $28.24, which suggests less of a clear bargain and more of a judgment call for you.
For a closer look at how cash flows, discount rates, and terminal assumptions shape that gap, it helps to see the full SWS DCF model in action: Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SolarEdge Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around SolarEdge Technologies is clearly mixed, so this is the moment to look at the numbers yourself and decide where you stand. Act while the data and market reaction are still fresh, and weigh both the upside potential and the issues that keep investors cautious by checking the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond SolarEdge Technologies?
Do not stop with SolarEdge Technologies. Broaden your watchlist using focused stock ideas that line up with the kind of risk, balance sheet strength, and upside you want.
- Target potential value opportunities by scanning a 32 high quality undervalued stocks that share strong fundamentals and may trade below their implied worth.
- Strengthen your portfolio foundation by focusing on companies with resilient finances through a list of solid balance sheet and fundamentals (25 results).
- Turn overlooked potential into a watchlist advantage by combing through a 20 high quality undiscovered gems before attention and capital crowd in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com