


Verisk Analytics (VRSK) is back in focus after its catastrophe and risk unit issued fresh insured loss estimates for Hurricane Isaias, pegging industry losses between US$1b and US$2b.
Against that backdrop, Verisk Analytics shares closed at US$180.58, with the 1 day share price return of 2.22% and 7 day gain of 7.05% offering a short term rebound. However, the 90 day share price return declined 10.38% and the 1 year total shareholder return fell 25.24%, pointing to fading longer term momentum despite recent news and product integrations such as the Solera claims collaboration.
Scan beyond Verisk Analytics and see how other catastrophe exposed insurers and data providers are positioned with our hand picked 32 resilient stocks with low risk scores for balance sheet strength and resilience.
The bounce in Verisk Analytics after the hurricane loss update and Solera tie up could indicate renewed confidence in the business, or simply reflect a shift in market sentiment. The valuation now merits a closer examination.
Most Popular Narrative: 135% Overvalued
Verisk Analytics closed at $180.58, while the most followed narrative on the stock pegs fair value at $76.85, which implies a very large valuation premium and frames the recent rebound in a different light.
Verisk Analytics is a regulatory-grade data toll on the US property & casualty insurance industry, monetized through approximately 83% subscription revenue with approximately 92% client retention. VRSK's narrow-moat franchise produces FCF with an unusually high degree of predictability, durable enough to justify a 15× exit multiple at a 35% margin of safety. The 2022 to 2025 portfolio simplification (Energy, Argus, 3E, Marketing Solutions all divested) has produced a cleaner pure-play with structurally higher margins (Adj EBITDA 56.2% in 2025 vs. 53.5% in 2023) and a shrinking share count (approximately 19% reduction since 2019). What the investor is paying for here is a regulatory annuity with an embedded MSD price-and-volume escalator, and walking away from any thesis premised on this becoming a HSD-to-DD revenue compounder.
See why 7 investors see Verisk Analytics as 135% overvalued.
According to Esteban, this framework treats Verisk Analytics as a dependable, cash generative toll operator on the insurance sector rather than a rapid top line expansion story, which naturally pulls the narrative fair value below the current share price when more aggressive growth assumptions are stripped out.
Result: Fair Value of $76.85 (OVERVALUED)
Still, Verisk Analytics faces pressure if insurance clients push back on pricing or if future catastrophe losses reshape how carriers use third party data tools.
Find out about the key risks to this Verisk Analytics narrative.
Another View: SWS DCF Fair Value For Verisk Analytics
Esteban’s narrative flags Verisk Analytics as sharply overvalued at a fair value of $76.85, yet the SWS DCF model paints a very different picture. On that framework, VRSK at $180.58 is trading below an estimated future cash flow value of $288.04, which points to undervaluation instead. When two methods disagree this sharply, which one do you trust more with your own capital?
Look into how the SWS DCF model arrives at its fair value.
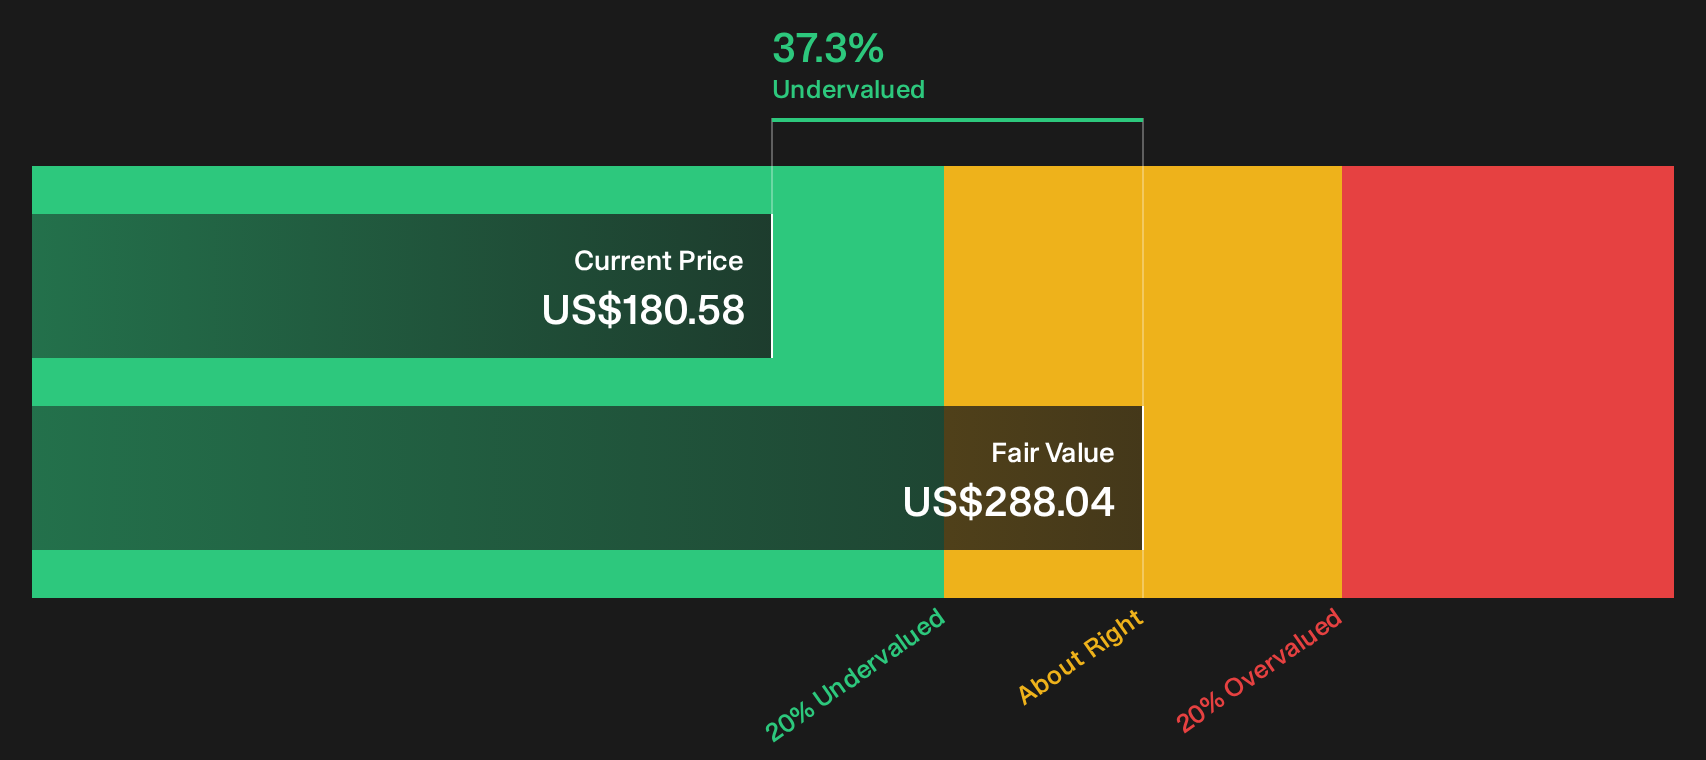
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Verisk Analytics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Verisk Analytics can be useful, as long as you pull up the numbers yourself and make a call quickly instead of drifting with headlines. To see a concise snapshot that highlights both the concerns and the potential upside in one place, start with 3 key rewards and 1 important warning sign.
Looking for more Verisk Analytics style investment ideas?
If Verisk Analytics has you thinking more carefully about price versus value, now is the time to widen the net and pressure test your next few ideas.
- Target steadier potential returns by focusing on businesses that screen for quality and valuation using the 32 high quality undervalued stocks.
- Strengthen your income game by reviewing companies that combine higher yields with resilience through the 7 dividend fortresses.
- Guard against nasty surprises by filtering for companies that score strongly on financial robustness with the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com