


W.W. Grainger (GWW) is back in focus after fresh research highlighted the distributor in two ways: a Zacks Rank of #2 and strong DuPont analysis metrics, while also flagging a richer valuation versus Global Industrial.
Recent trading has been lively for W.W. Grainger, with a 7 day share price return of 5.31% and a year to date share price gain of 32.56% that points to building momentum despite a 90 day share price decline of 5.09%. Over a longer horizon, shareholders have seen a 40.04% 1 year total shareholder return and 219.86% over 5 years, so the latest DuPont spotlight and valuation debate arrive on top of already strong multi year wealth creation.
Scan beyond W.W. Grainger and compare its momentum and value story with a curated 32 high quality undervalued stocks that share strong fundamentals and may be priced more conservatively.
Bulls point to W.W. Grainger’s earnings quality and DuPont credentials. Bears keep circling the valuation and the recent run in the share price. Which side do the numbers lean toward as you weigh what you are paying today?
Most Popular Narrative: Fairly Valued
W.W. Grainger last closed at $1,330.62, almost exactly in line with the most followed fair value estimate of $1,331.64 that applies an 8.24% discount rate and incorporates detailed assumptions about growth, margins and capital allocation through 2029.
The current narrative that W.W. Grainger is fairly valued and bullish suggests the share price already reflects ongoing double digit organic growth, mid teens operating margins, and consistent capital returns such as the recent dividend increase.
See why 30 investors see W.W. Grainger as 0% undervalued.
Result: Fair Value of $1,331.64 (ABOUT RIGHT)
Still, rising freight and fuel costs, along with pressure on private label product economics, could quickly challenge the W.W. Grainger fair value story.
Find out about the key risks to this W.W. Grainger narrative.
Another View: W.W. Grainger Looks Expensive On Earnings
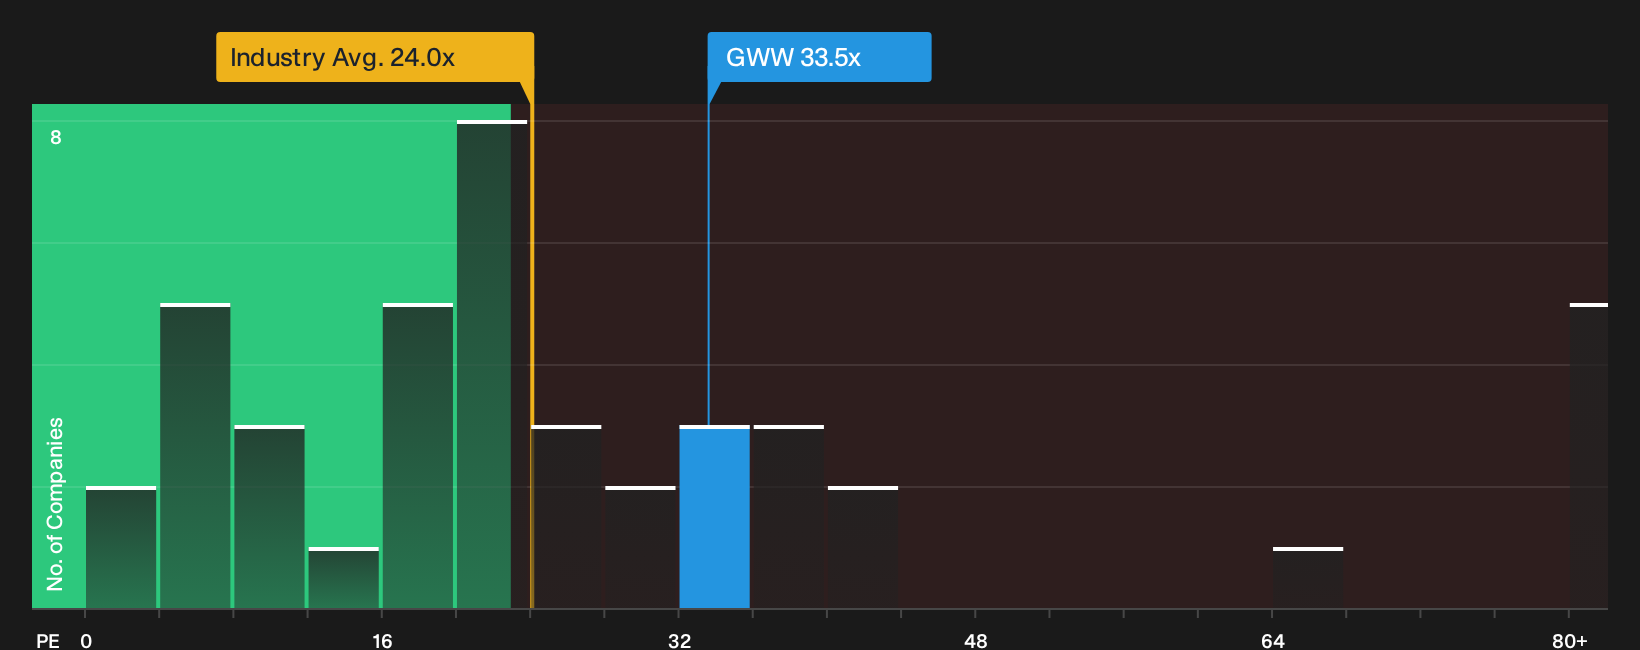
The analyst fair value story for W.W. Grainger leans on detailed cash flow and margin assumptions. A simpler earnings lens tells a tougher story. The stock trades on a P/E of 33.5x versus 27.6x for peers and a fair ratio of 25.9x, which points to richer pricing. How comfortable are you paying that premium if sentiment cools?
To see how that earnings multiple stacks up against history, peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around W.W. Grainger leaves you on the fence, move quickly to review the underlying figures, weigh the trade offs yourself, and see how our breakdown of 1 key reward and 1 important warning sign can help inform your view.
Looking for more W.W. Grainger style investment ideas?
If W.W. Grainger has sharpened your focus on quality and price, do not stop here. Use the Simply Wall Street Screener to surface fresh, data driven ideas that match your own risk, return, and income preferences.
- Target potentially mispriced opportunities early by scanning our hand picked 20 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Prioritise resilience in your portfolio by filtering for businesses on the list of solid balance sheet and fundamentals (25 results) that combine financial strength with disciplined capital use.
- Secure potential cash flow from your holdings by reviewing the 7 dividend fortresses that focus on higher yielding companies with screening around payout quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com