


Old Second Bancorp (OSBC) is back on investor radar as analysts lift earnings expectations ahead of the September quarter report on October 21, with forecasts calling for higher profit and revenue figures.
Recent price action has been softer, with Old Second Bancorp recording a share price return of 3.14% over 90 days and 26.44% year to date, while the 1 year total shareholder return of 39.94% and 3 year total shareholder return of 89.52% indicate momentum that has been strong over a longer horizon.
Scan how Old Second Bancorp stacks up against other potential opportunities by reviewing a curated set of 32 high quality undervalued stocks that combine solid fundamentals with room for a re-rating.
Old Second Bancorp now trades at a clear gap to both analyst targets and intrinsic estimates, so the real puzzle is where fair value sits inside that spread and how much of the recent run is already reflected in the price.
Most Popular Narrative: 12% Undervalued
Old Second Bancorp closed at $24.63 against a widely followed fair value marker of $28.00. This places the current quote below that narrative line and focuses attention on how much of its earnings engine is already recognized in the price.
The growing national specialty lending and powersports portfolio, with APRs above 10% and contribution margins above 8% even with loss rates around 2%, provides Old Second Bancorp with a higher yielding engine that can support revenue and net margin resilience.
See why 1 investors see Old Second Bancorp as 12% undervalued.
Result: Fair Value of $28.00 (UNDERVALUED)
Still, the Old Second Bancorp story depends on credit costs easing from elevated net charge offs and on its concentrated Illinois footprint avoiding a sharp local slowdown.
Find out about the key risks to this Old Second Bancorp narrative.
Another View: Old Second Bancorp Through The P/E Lens
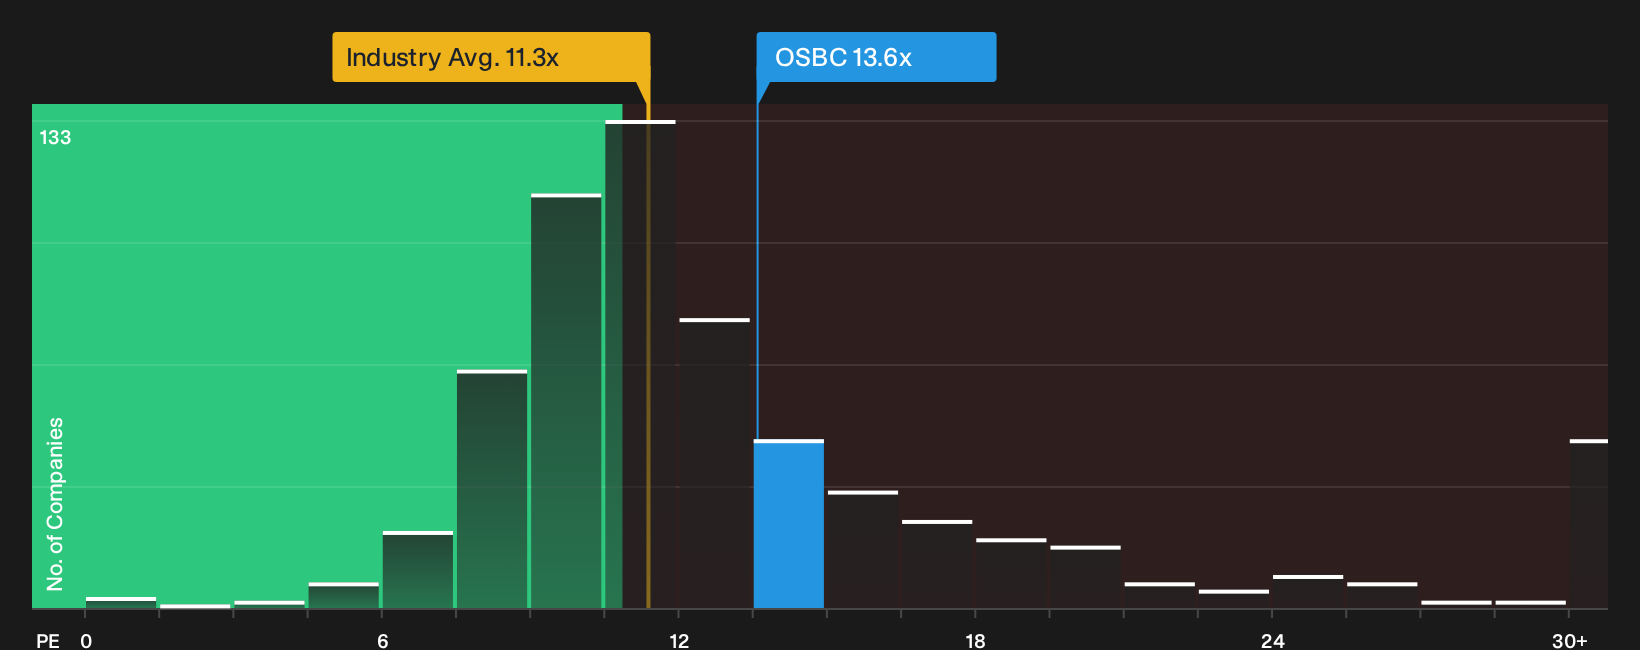
The story looks very different once Old Second Bancorp is viewed through its P/E ratio. At 13.6x earnings, the stock trades above the US Banks industry on 11.4x, above peers at 13.5x, and above a fair ratio of 12.1x that the market could eventually lean toward. That gap points to valuation risk if sentiment cools, so how much weight do you give this compared with the undervalued fair value narrative?
To see what the numbers say rather than the storyline, it helps to walk through the full valuation breakdown in one place, including how that fair ratio was set and what would need to change for it to move closer to the current P/E. See what the numbers say about this price — find out in our valuation breakdown.
Visualizing Old Second Bancorp against its peers on this metric can sharpen that judgment, especially if you are comparing several regional banks side by side.
Next Steps
Mixed signals or emerging opportunity? If this shift in sentiment has your attention, move fast and test the thesis against both caution and optimism with 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Old Second Bancorp?
Do not stop with Old Second Bancorp alone. Use fresh screeners to pressure test your thinking, spot new angles, and keep your watchlist working harder for you.
- Target reliable income by zeroing in on 7 dividend fortresses that aim to pair yield with balance sheet strength.
- Hunt for potential mispricing with a curated 32 high quality undervalued stocks that already clear quality and fundamentals checks.
- Secure more sleep-at-night positions by focusing on a 32 resilient stocks with low risk scores that filters for resilient financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com