


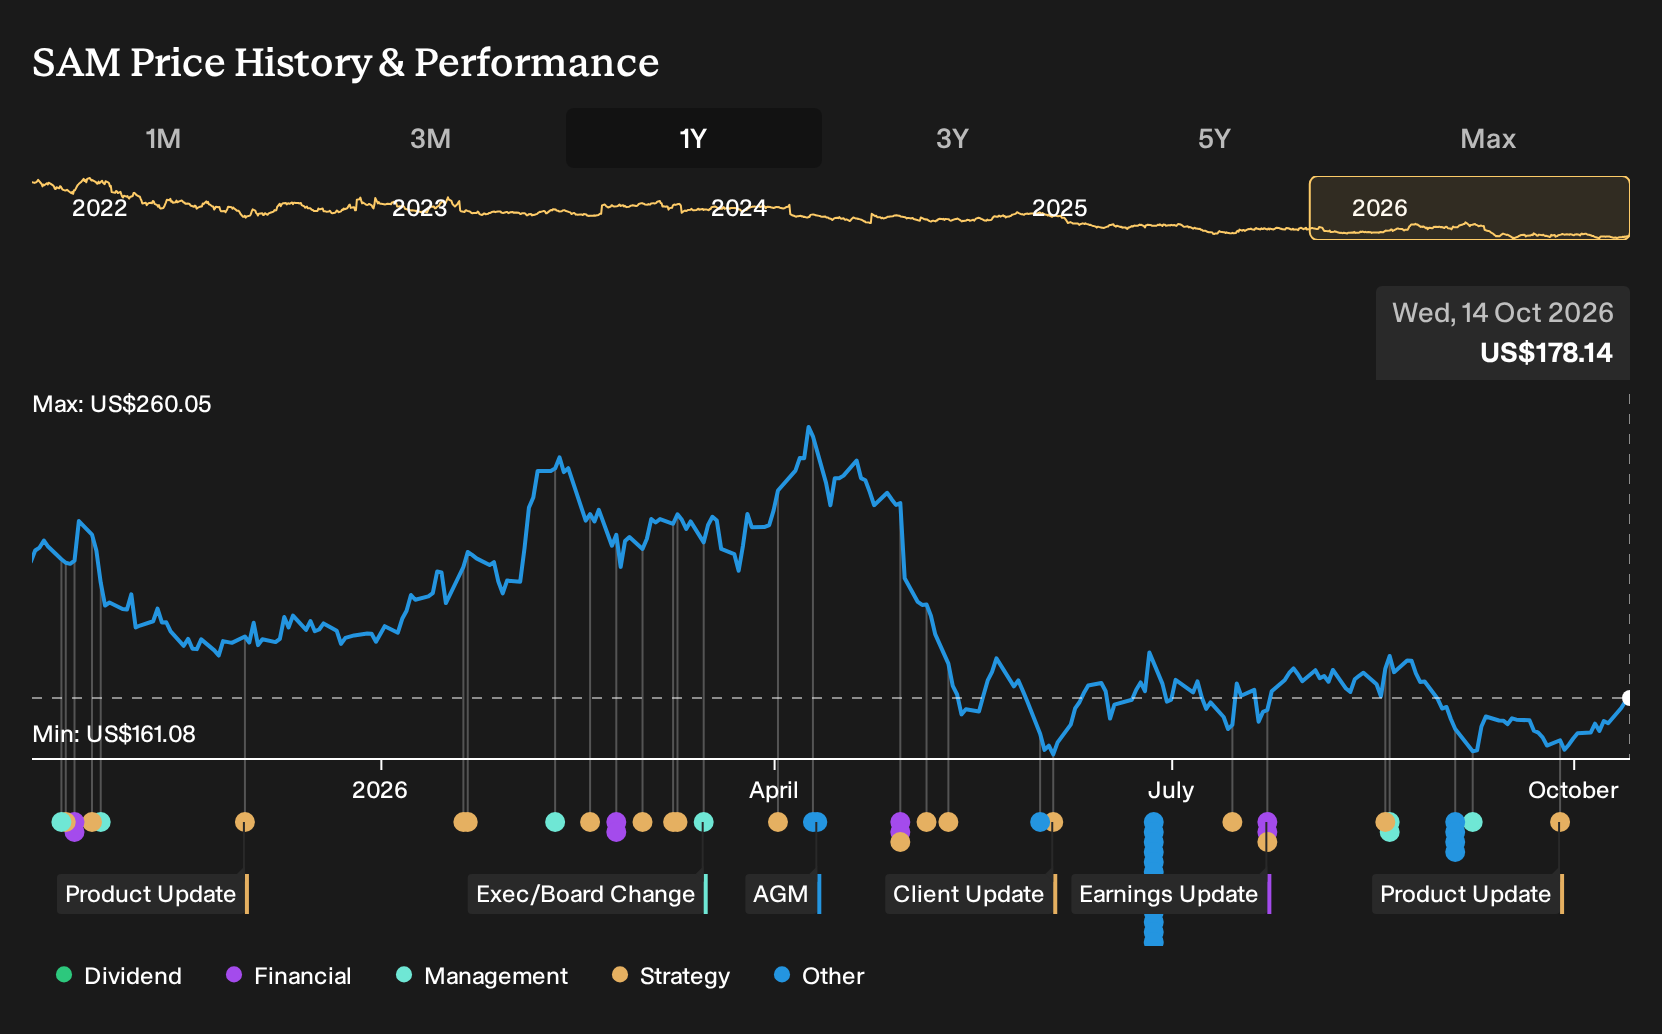
If you had decided to buy Boston Beer on 14 October 2025, trusting that premium drinks and new products would justify analyst optimism, the next twelve months would have felt rough. Investors who held Boston Beer over the past year are down 20.3%, including dividends. Given the bullish and bearish reports already on record that month, which specific warning or assumption about demand, margins, or reliance on new categories most deserved closer scrutiny at the time?
Boston Beer has already moved. See which of 32 high quality undervalued stocks still trade below our estimates.
The Argument Boston Beer Investors Were Balancing
The shares cost US$223 at the start of the period, and Boston Beer holders were weighing two very different stories about where the business could reasonably head next.
The bullish view saw a Fair Value of US$244, a price implied by assumptions that productivity gains and premium brands would lift profit margins from 3.9% to 6.8% by 2028. This camp focused on Beyond Beer products and digital marketing, which were expected to widen distribution and support earnings.
The bearish narrative pointed to a Fair Value of US$187, a level tied to expectations that revenue would decline 2.0% a year even as margins rose to 7.0%. That scenario emphasized demographic shifts toward moderation and tariff driven cost pressure as key risks for Boston Beer.
What The Results Changed For Boston Beer
The key update for Boston Beer was the Q2 2026 report, where revenue fell to US$568.3 million and profit slipped to US$51.4 million. Net margin edged down from 10.2% to 9.0%. That weaker profitability challenged the bullish bet on steady margin expansion, while still not fully confirming the more pessimistic revenue decline story. Overall, the evidence cut both ways.
The whole episode turned on one assumption: that premium brands and productivity would reliably lift margins. For another company with a similar pitch, focus on whether net margin and absolute profit actually move in the promised direction once new categories start scaling.
What Today's Boston Beer Price Is Asking You To Believe
Boston Beer trades at US$178 after a 20.3% loss over the past year, while this Narrative's Fair Value sits above the current price. The argument leans on cost discipline, premium pricing and a broader beyond beer range to support earnings power.
A buyer today would be assuming that mix shift into higher priced RTD and hard tea offerings, combined with sustained cost control, meaningfully lifts profitability in the years ahead.
"A key factor is that Boston Beer Company continues to convert its test and learn product engine, cost reduction program, and premium pricing into sustained share gains in a moderating alcohol market. The current numbers, including high 40s to low 50s gross margin guidance, strong cash and liquidity, and ongoing share repurchases, suggest the share price may not fully reflect Boston Beer Company’s profitability profile and balance sheet strength."
The price and this Narrative do not agree. → Uncover what this Narrative says Boston Beer is actually worth
Where Could You Get There Earlier?
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 41% below our estimate - turns a record backlog of data center and industrial projects into modular buildouts.
- Company 2 - 47% below our estimate - expands an online casino and betting platform as users shift from offline gambling.
- Company 3 - 49% below our estimate - focuses on long-duration e-infrastructure projects tied to mission-critical and AI data centers.
That is three of the list. See every one of the 25 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com