


If you bought into DICK'S Sporting Goods for health and sports tailwinds, the Foot Locker deal has been an uncomfortable surprise. Investors who held DICK'S Sporting Goods over the past year are down 39.9%, including dividends. If you went in expecting 6.2% annual revenue growth, an 8.9% margin and an 18x P/E in three years, what did that thesis miss about integration risk, footwear mix pressure and the limits of omni-channel optimism?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
DICK'S Sporting Goods has already moved. See which of 32 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On DICK'S Sporting Goods
The shares cost US$230 at the start, so any view on DICK'S Sporting Goods began with the question of whether that price matched the story you believed.
The bullish case put Fair Value at US$273, built on 6.2% annual revenue growth and a profit margin pushing toward 8.9%, supported by omni-channel investments, as well as the scaling of GameChanger and DICK'S Media Network.
The bearish view set Fair Value at US$199, assumed only 3.0% top line growth and an 8.5% margin, and focused on the risk that heavy House of Sport expansion and higher inventory could pressure earnings.
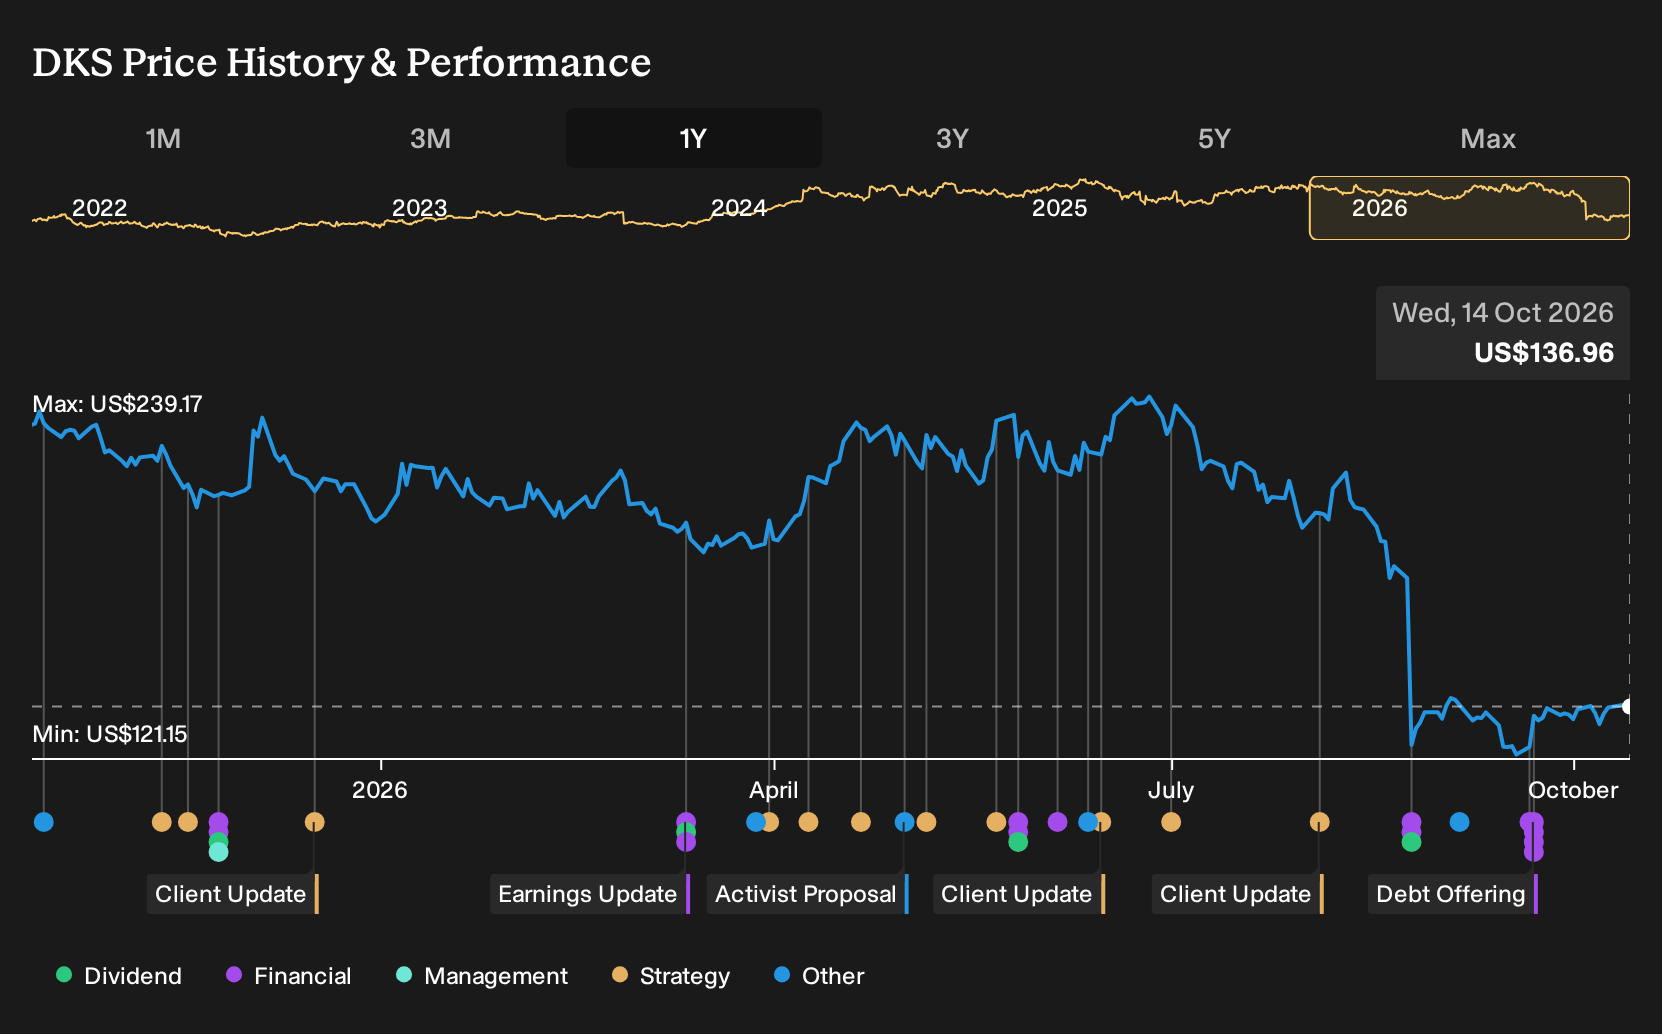
What The Results Changed For The DICK'S Sporting Goods Narrative
The clearest new fact was DICK'S Sporting Goods reporting Q2 2027 revenue of US$5.59b against US$3.65b in Q2 2026, helped by the Foot Locker acquisition, which lent some support to the bullish growth story. Profit told a different story. Net income slipped from US$381.4m to US$315.5m and net margin moved from 10.5% to 5.6%, which backed the cautious view on integration and footwear pressure. Overall, the evidence cut both ways.
The main assumption tested here was that higher sales and omni-channel spend would translate cleanly into richer profitability. When you look at another retailer pitching a similar story, track top line, absolute earnings and net margin together, then compare them with whatever revenue growth and margin targets management talked about at the decision date.
What You Would Be Paying For In DICK'S Sporting Goods Today
DICK'S Sporting Goods trades at US$137 today after a 39.9% loss over the past year. The selected Narrative sees Fair Value above that level, built on a belief that current pricing leans harder on footwear and Foot Locker worries than on newer income streams.
The present question is whether high engagement from GameChanger, media revenue and experiential formats can outweigh ongoing footwear promotions and acquisition drag. A buyer at today's price has to judge that these concepts convert into steadier cash generation without putting the balance sheet or dividend under strain.
"The current valuation implies the share price already reflects Foot Locker's earnings drag, promotional footwear pressure, and litigation risk more than the potential cash flow contribution from experiential stores, higher-margin digital and media businesses, and a broader, higher-priced footwear mix."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Which Company Could Surprise You Next?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 30% below our estimate - targets AI-focused infrastructure customers that integrate its combined compute and software stack.
- Company 2 - 47% below our estimate - scales a proprietary online wagering platform as changing rules permit entry to new markets.
- Company 3 - 42% below our estimate - tackles specialised technical disputes where clients require independent science and engineering expertise.
That is three of the list. See all 25 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com