


Hansoh Pharmaceutical Group (SEHK:3692) has just put two major pipeline assets in the spotlight. Fresh Phase III data for obesity drug Olatorepatide and EU review progress for lung cancer therapy Aumolertinib are now front and center for investors.
At a HK$31.38 share price, Hansoh Pharmaceutical Group has seen mixed momentum, with the 1-day share price return up 2.62% but the 30-day share price return down 7.49%, while the 3-year total shareholder return of 191.68% contrasts with a 10.92% decline over the past year.
Spot 125 healthcare AI stocks that, like Hansoh Pharmaceutical Group, are working to turn complex science into real-world treatments with the potential to change markets.Hansoh Pharmaceutical Group now trades at a sizeable discount to both analyst targets and some intrinsic value models after the recent pullback. Is that simply the market lagging the news flow, or is it a sober check on pipeline risk?
Preferred P/E of 24.3x: Is it justified?
Hansoh Pharmaceutical Group now trades on a P/E of 24.3x, which puts a clear premium on the current HK$31.38 share price relative to many peers.
The P/E ratio compares what investors are paying for each unit of current earnings. For a research driven pharmaceutical business like Hansoh Pharmaceutical Group, that figure often reflects how much faith the market has in its pipeline and the durability of existing cash flows.
Here, the picture is mixed. The stock is considered good value against some intrinsic value models, with one SWS DCF estimate putting fair value at HK$50.54, and the shares trading 37.9% below that level. Analysts are also in solid agreement, with a consensus price target of HK$47.82, which is 52.4% above the last close.
The premium P/E looks less forgiving once you compare it to the Hong Kong Pharmaceuticals industry and peers. The 24.3x multiple is well above the sector average of 13.6x and higher than the peer group average of 16.6x, and it also sits slightly above an estimated fair P/E of 24.1x. That combination suggests the market is already assigning Hansoh Pharmaceutical Group a rich earnings tag that could move closer to the fair ratio over time if sentiment cools or earnings do not keep pace.
Explore the SWS fair ratio for Hansoh Pharmaceutical Group.
Result: Price-to-Earnings of 24.3x (OVERVALUED)
Still, Hansoh Pharmaceutical Group faces real pressure if key trials disappoint or pricing power weakens in its core China portfolio, which could puncture the current premium.
Find out about the key risks to this Hansoh Pharmaceutical Group narrative.
Another View: What Hansoh Pharmaceutical Group Looks Like On Cash Flows
The earnings multiple paints Hansoh Pharmaceutical Group as expensive, yet the SWS DCF model points the other way. On that framework, fair value sits at HK$50.54, which is well above the current HK$31.38 share price, so the stock screens as materially undervalued on future cash flows. Which signal do you trust more: a rich P/E today or a cash flow model looking years ahead?
Look into how the SWS DCF model arrives at its fair value.
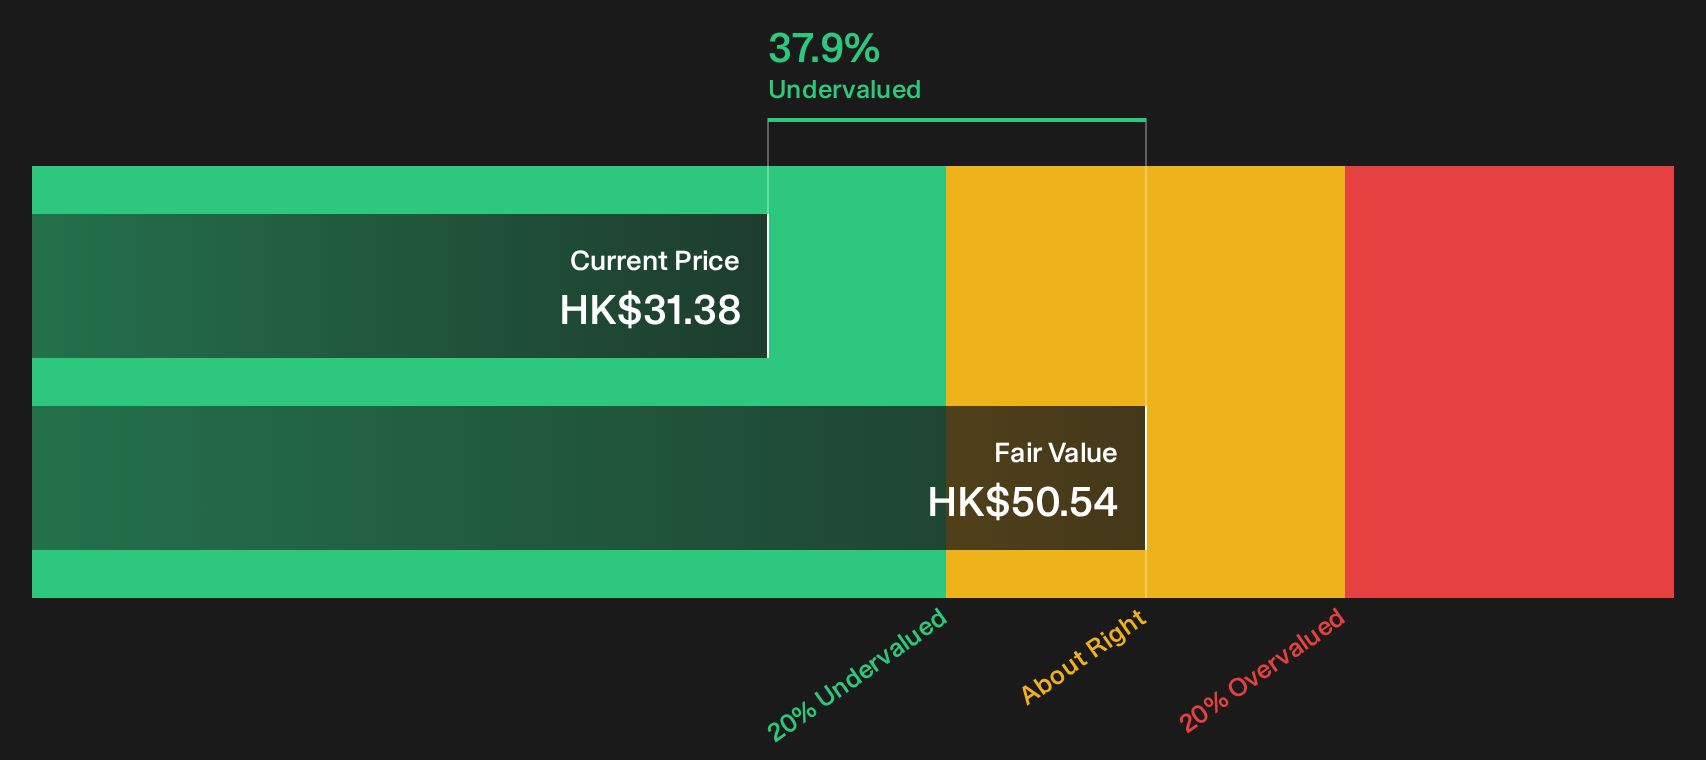
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hansoh Pharmaceutical Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 198 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hansoh Pharmaceutical Group's valuation and pipeline can feel confusing, so move quickly to review the underlying data, then weigh the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Hansoh Pharmaceutical Group?
Hansoh Pharmaceutical Group may already be on your radar, but you give yourself a better shot at solid decisions when you compare it against a wider set of high quality opportunities.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (201 results) that can help anchor a more durable portfolio.
- Hunt for quality at a discounted price by reviewing the 198 high quality undervalued stocks that combine stronger financials with more modest valuations.
- Spot potential up and comers before they are widely followed by checking the 613 high quality undiscovered gems that many investors may still be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com