


Hankyu Hanshin Holdings (TSE:9042) has expanded its share repurchase program, adding 4,500,000 shares for ¥20,000 million and extending the authorization to 12,000,000 shares for ¥50,000 million through March 31, 2027.
The share repurchase announcement comes after a mixed stretch for Hankyu Hanshin Holdings, with a 1-day share price return of 0.33% and a year-to-date share price gain of 12.61% contrasting with a 30-day share price decline of 2.98%. At a latest share price of ¥4,527.0, the stock has delivered a 1-year total shareholder return of 3.23% and a 5-year total shareholder return of 41.08%. This indicates that momentum has cooled recently, while longer term holders have still seen meaningful value creation over time as management now signals renewed confidence through the extended buyback.
Scan how Hankyu Hanshin Holdings compares to other companies returning cash to shareholders by focusing on our curated list of 32 dividend fortresses.
Hankyu Hanshin Holdings is buying back more stock at the same time its shares trade below analyst targets and some intrinsic value estimates. Is that gap pointing to a bargain or a fair warning signal?
Preferred P/E of 12.9x: Is it justified for Hankyu Hanshin Holdings?
Hankyu Hanshin Holdings trades on a P/E of 12.9x, which sits below the broader JP market multiple of 13.9x, even though the stock is above some intrinsic value estimates and below the analyst target of ¥5,220.
The P/E ratio compares the current share price to earnings per share and shows how much investors are paying for each unit of profit. For a diversified group like Hankyu Hanshin Holdings, with urban transportation, real estate, leisure and ICT activities, earnings-based yardsticks often matter more to investors than revenue alone because they capture the profitability of very different business lines in a single figure.
Context around this earnings multiple is mixed. The 12.9x P/E is higher than the JP Transportation industry average of 11.7x, which suggests investors are willing to pay a premium compared with sector peers. At the same time, the P/E sits below both the peer average of 14.5x and the estimated fair P/E of 15.8x. This points to scope for the market valuation to move closer to that fair ratio if profit quality, growth and balance sheet risks remain broadly consistent with current assessments.
Relative to the sector, the stronger recent profit performance helps explain part of that premium. Earnings grew 20.9% over the past year compared with 10.6% for the wider Transportation group, and profits have expanded over the past 5 years as well. Yet the forecast earnings growth rate of 4.8% per year is slower than the wider JP market expectation of 9.6% per year, so the current P/E reflects a balance between solid profitability, moderate growth forecasts, and flagged issues such as weaker coverage of debt and dividends by cash flow.
Explore the SWS fair ratio for Hankyu Hanshin Holdings.
Result: Price-to-earnings of 12.9x (ABOUT RIGHT)
Still, the high exposure to Japan, along with weaker cash coverage of debt and dividends, leaves Hankyu Hanshin Holdings vulnerable if funding costs or domestic demand shift.
Find out about the key risks to this Hankyu Hanshin Holdings narrative.
Another view on Hankyu Hanshin Holdings valuation
Our DCF model paints a very different picture. At a share price of ¥4,527, Hankyu Hanshin Holdings screens as expensive versus an estimated future cash flow value of ¥2,746.14. That gap raises a simple question for you as an investor: Are reported earnings or long term cash generation the better guide here?
Look into how the SWS DCF model arrives at its fair value.
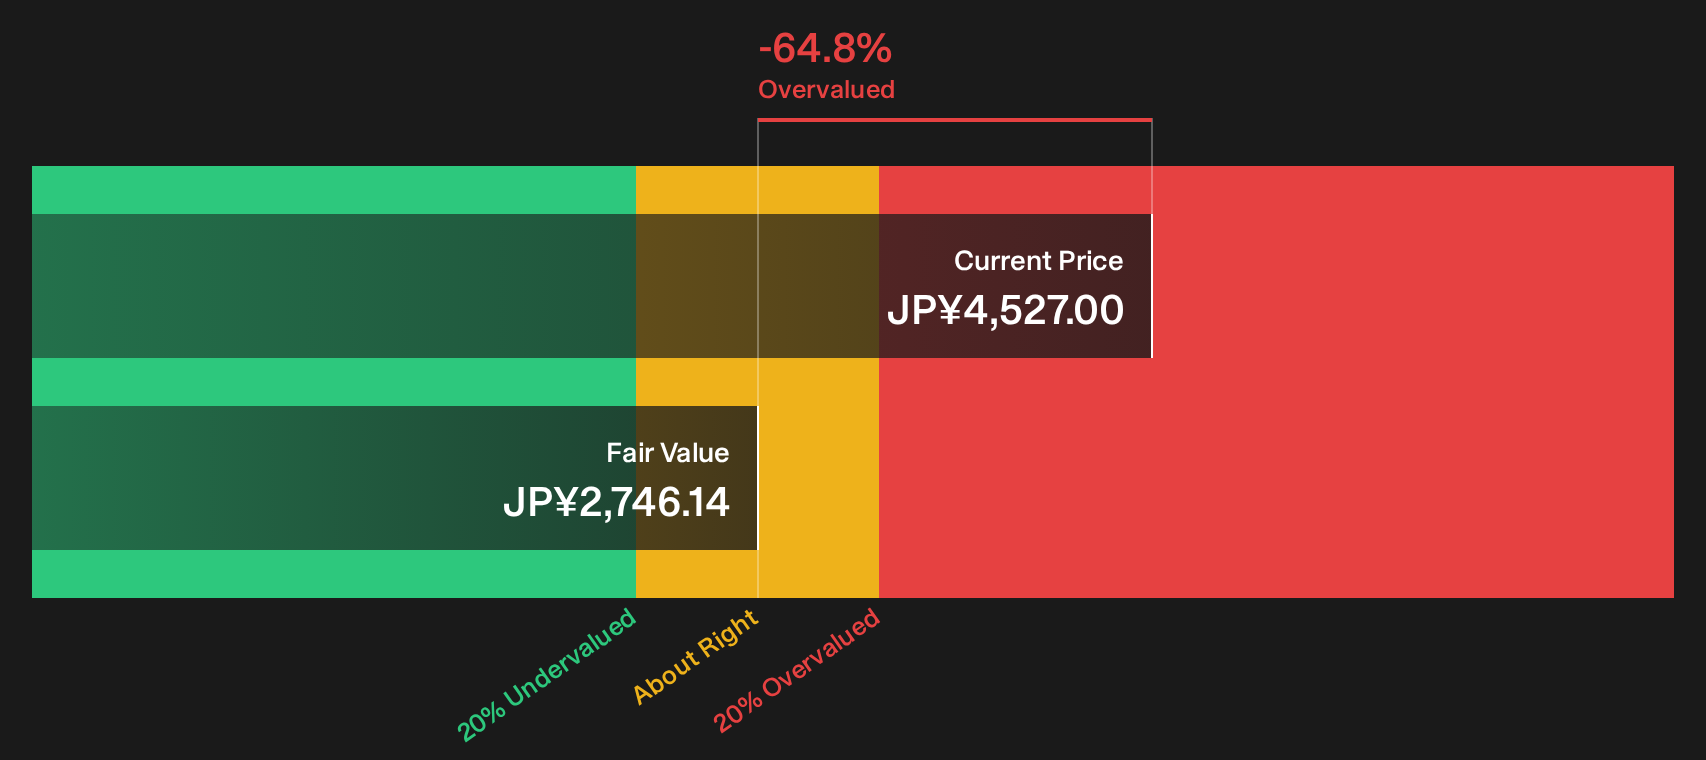
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hankyu Hanshin Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Hankyu Hanshin Holdings can feel confusing, so treat them as a prompt to move quickly. Pull up the underlying numbers and decide what really matters for your time horizon using our breakdown of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Hankyu Hanshin Holdings?
Do not stop with Hankyu Hanshin Holdings. Use the screener to surface fresh ideas that align with your goals before the next move passes you by.
- Target potential mispricing by weighing companies that combine solid fundamentals with appealing valuations through our focused list of 15 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses that pair healthier balance sheets with steadier fundamentals using the curated list of solid balance sheet and fundamentals (21 results).
- Hunt for less crowded opportunities by scanning companies with stronger quality markers that remain off many radars in the 72 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com