


- Mercury NZ reported a 19% year on year lift in trading margin to NZ$445 million for the September quarter, supported by its diversified generation portfolio and new capacity from the completed Kaiwera Downs Stage 2 wind expansion.
- Progress across multiple renewable projects, including full generation at Kaiwera Downs Stage 2 and turbine installation at Kaiwaikawe Wind Farm, indicates that Mercury NZ is actively converting its development pipeline into operating assets. This reduces reliance on hydrology conditions alone.
- We will now look at how Mercury NZ's investment narrative could be influenced by its stronger trading margin and recent wind build out.
Scan the renewable energy space for other utilities building out wind and hydro portfolios with the same intensity as Mercury NZ by starting with our curated 42 power grid technology and infrastructure stocks
Mercury NZ Investment Narrative Recap
To own Mercury NZ, you need to believe the electricity transition in New Zealand rewards large, renewable heavy generators that manage hydrology risk and capital spend carefully. The recent 19% lift in trading margin to NZ$445 million supports that thesis by showing the portfolio can keep earnings resilient even when Waikato hydro inflows are weak.
In the near term, the key swing factor is still hydrology, now partly offset by new wind and geothermal output. The biggest risk is that high and sustained capex for projects and refurbishments, layered on top of existing debt and a dividend that is not well covered by earnings or free cash flow, squeezes financial flexibility.
The clearest operational marker in this update is completion of the Kaiwera Downs Stage 2 wind expansion and its move to full generation. That 155 MW of extra capacity helped Mercury NZ keep trading margins firm despite softer hydro production, and shows the development pipeline turning into cash generative assets rather than staying on slide decks.
For you as an investor, this directly ties into the main catalysts. Progress at Kaiwera Downs and turbine installation at Kaiwaikawe Wind Farm support the plan to diversify away from pure hydro exposure and to meet growing electricity demand from decarbonisation. Execution risk remains around project timing, cost control and how these investments interact with already elevated capital needs and debt levels.
Mercury NZ's current analyst storyline points to revenues of NZ$3.6b and earnings of NZ$378.0m by 2029. That path assumes 2.1% yearly revenue growth and an earnings increase of NZ$290.0m from NZ$88.0m today.
Uncover why Mercury NZ's fair value indicates a 6% potential upside to its current price before other investors narrow that difference.
Exploring Other Perspectives
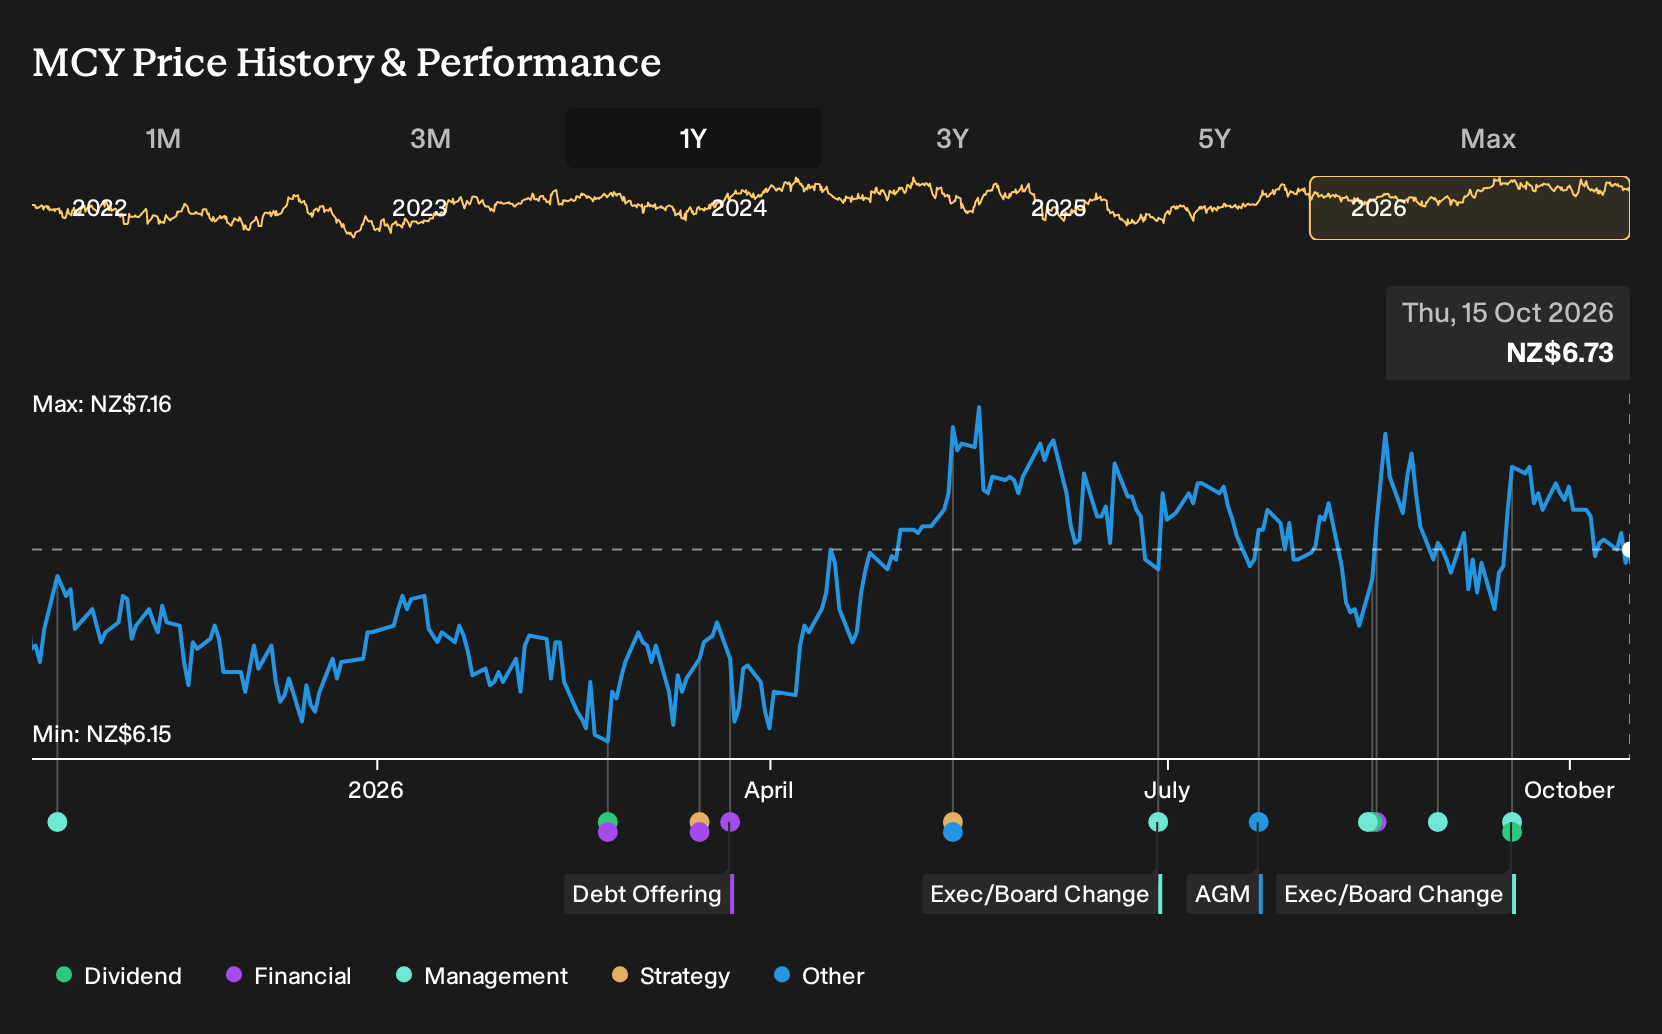
Three fair value estimates from the Simply Wall St Community sit in a wide band between NZ$7.14 and NZ$12.32, so retail investors clearly do not agree on where Mercury NZ should trade. When you also factor in hydrology volatility and heavy, ongoing capex needs, you get a company where opinions can spread out fast. Explore those differing viewpoints before deciding how this profile fits your portfolio.
Explore 2 other Mercury NZ fair value estimates, including one that suggests as much as 83% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Mercury NZ research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Mercury NZ. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mercury NZ's overall financial health at a glance.
Looking For More Investment Ideas Beyond Mercury NZ?
After forming a view on Mercury NZ, it often helps to zoom out and scan a broader watchlist. That way you can compare this utility against other businesses with different balance sheet strength, dividend profiles and valuation setups, then decide where Mercury NZ truly fits in your overall plan.
- If capital preservation sits high on your list, start by reviewing a 224 resilient stocks with low risk scores that have historically kept risk scores on the lower side.
- For investors hunting for quality at a reasonable price, use our curated 198 high quality undervalued stocks that pair robust cash flows with healthier looking balance sheets.
- Income focused readers who care about consistency over headlines can scan a 219 dividend fortresses that combine higher yields with an emphasis on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com