


Amazon (AMZN) is facing another round of workforce reductions, giving investors fresh reason to reassess the e-commerce and cloud giant’s cost structure and growth strategy. The company confirmed that it has cut a small number of jobs, primarily within its Stores business, with less than 1,000 corporate positions reportedly affected across India, the United States, and the United Kingdom.
The latest cuts come after Amazon eliminated roughly 30,000 corporate positions through its larger restructuring that began last year and continued into January 2026. While the newest reduction is relatively small, it reinforces Amazon CEO Andy Jassy’s push to streamline operations, reduce bureaucracy, and redirect resources toward strategic growth areas, particularly artificial intelligence (AI).
It remains to be seen whether the ongoing workforce optimization can translate into stronger margins and efficiency without hurting Amazon’s core retail operations. With the company simultaneously ramping up spending on AI infrastructure and other long-term growth initiatives, here’s how investors can play AMZN stock amid the latest round of Amazon layoffs.
About Amazon Stock
Amazon is a global technology and e-commerce behemoth headquartered in Seattle, Washington. Today, the company operates across a dazzling range of businesses, cloud services via AWS, digital streaming, subscription services, advertising, physical retail, consumer electronics, and more. Its diversified growth model has placed it among the world’s most valuable public companies with a market capitalization of $2.7 trillion, and it has a secure position among the “Magnificent Seven.”
Amazon has delivered significant gains in 2026, although AMZN stock has experienced some volatility in recent sessions. Shares are up 10% year-to-date (YTD) and 18% over the past year, broadly reflecting investor optimism around Amazon’s accelerating AWS growth, AI opportunity, and improving profitability. The latest quarterly results also provided an important fundamental catalyst; second-quarter net sales rose 20% year-over-year (YOY) to $200.6 billion, while AWS revenue jumped 37%, marking the division's fastest growth in 18 quarters.
More recently, AMZN stock declined 2% on Oct. 8 as investors digested the latest round of workforce reductions and broader market volatility. However, shares rebounded more than 3% on Oct. 9, only to plunge again by 1% in the following session. The volatility suggests investors are still assessing the latest layoffs to understand whether this will contribute to broader efforts to streamline operations and redirect resources toward higher-priority growth areas such as AI.
The recent price action highlights the competing forces shaping Amazon — near-term concerns over restructuring and enormous AI-related capital spending versus the longer-term potential of AWS, advertising, and AI-driven businesses. With Amazon’s AI infrastructure investments accelerating alongside strong AWS growth, the stock’s next move will likely depend on whether these investments translate into sustained growth.
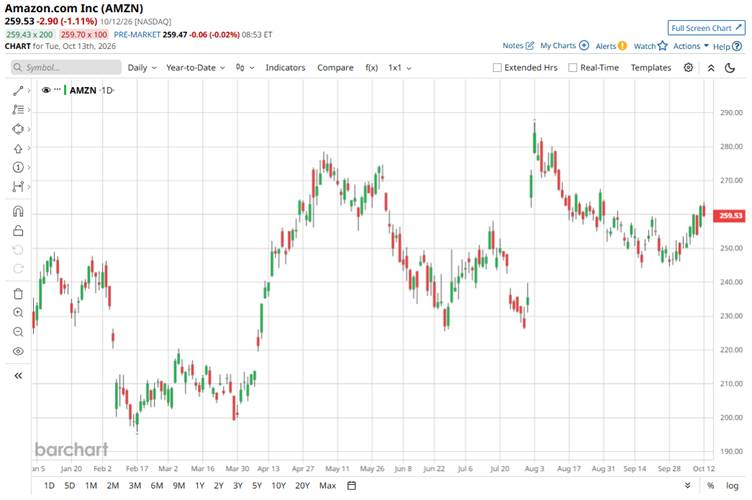
AMZN stock currently trades at a premium compared to the sector median at 32.1 times forward earnings.
Steady Q2 Results
Amazon’s Q2 2026 earnings report, released on July 30, showed a strong acceleration in growth led by AWS and advertising while profitability improved sharply.
Net sales increased 20% YOY to $200.6 billion, compared with $167.7 billion in Q2 2025. North America sales rose 16% YOY to $116.2 billion, while International sales increased 15% YOY to $42.2 billion. The standout was AWS, with sales surging 37% YOY to $42.2 billion. Amazon said this was AWS’s fastest growth rate in 18 quarters, highlighting strong demand for cloud computing and AI infrastructure.
Profitability also improved substantially. Operating income climbed 43% YOY to $27.5 billion from $19.2 billion a year earlier, lifting the operating margin to roughly 13.7% from 11.4%. AWS was the biggest contributor, with operating income jumping 63% YOY to $16.6 billion. Moreover, net income exceeded expectations, soaring to $62.6 billion, or $5.75 per share, compared with $18.2 billion in Q2 2025, or $1.68 per share.
Amazon’s other high-margin businesses remained strong. Advertising revenue rose 26% YOY to $19.8 billion, while the company said its AI business and chips business each surpassed $25 billion in annualized revenue run rates.
Cash flow, however, presents a key consideration for investors. Trailing-12-month operating cash flow increased 33% to $161.4 billion, but free cash flow swung to an outflow of $7.6 billion from an $18.2 billion inflow a year earlier. The deterioration was primarily driven by a $66.1 billion increase in purchases of property and equipment, reflecting Amazon’s aggressive investments in AI and data-center infrastructure.
Additionally, for Q3 2026, Amazon guided net sales of $197 billion to $202 billion, representing 9% to 12% YOY growth. Amazon expects operating income of $22.5 billion to $26.5 billion, compared with $17.4 billion in Q3 2025.
The company also raised its expected 2026 capital spending to approximately $220 billion, up from its previous expectation of about $200 billion, as it accelerates spending on AI chips, data centers, and other infrastructure.
Meanwhile, analysts remain upbeat, projecting EPS to rise 12% YOY to $8.03 in fiscal 2026. Analysts expect a further 32% YOY increase to $10.59 in fiscal 2027.
What Do Analysts Expect for Amazon Stock?
Cantor Fitzgerald remains bullish on Amazon stock despite trimming its price target ahead of the Q3 earnings report. On Oct. 12, analyst Deepak Mathivanan maintained an “Overweight” rating on AMZN stock while lowering the price target to $310 from $320. Meanwhile, Tigress Financial analyst Ivan Feinseth maintained a “Buy” rating on Oct. 6, raising his price target to $385 from $315.
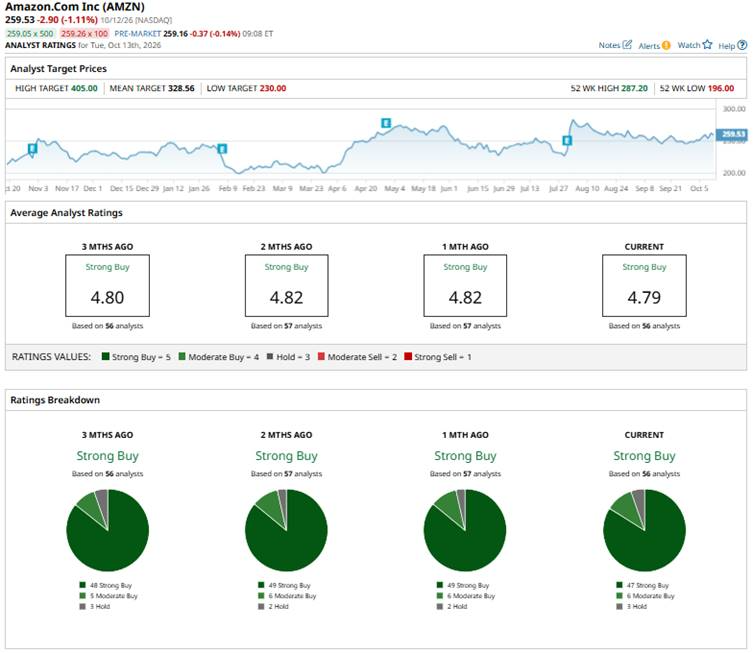
Overall, AMZN stock has a consensus “Strong Buy” rating on Wall Street. Of the 55 analysts covering the stock, 46 advise a “Strong Buy” rating, six suggest a “Moderate Buy,” and three analysts recommend a “Hold” rating.
The average price target for AMZN stock is $329.74, indicating potential upside of 29% from current levels. The Street-high target price of $405 suggests that the stock could rally as much as 59% from here.
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.