


CoStar Group has seen its share price fall sharply over recent years, which puts fresh focus on a simple question for anyone looking at the stock today: is the current market value adequately supported by the sales the business is generating?
- The share price has fallen 67.5% over the past 5 years, so the market is asking tough questions about how its revenue base translates into a fair valuation.
- CoStar Group relies heavily on recurring subscription revenue from data and analytics, which can support more predictable sales streams that investors often weigh closely when assessing what they are willing to pay.
- The analysts covering CoStar Group have run their own numbers. See what analysts think CoStar Group's shares could be worth.
For investors, the debate is whether the present CoStar Group share price is justified by the level and quality of its sales.
If you are questioning whether CoStar Group’s current price lines up with its sales, it can help to compare that debate with a broader set of valuation stories using 32 high quality undervalued stocks
Is CoStar Group Fairly Priced on Sales?
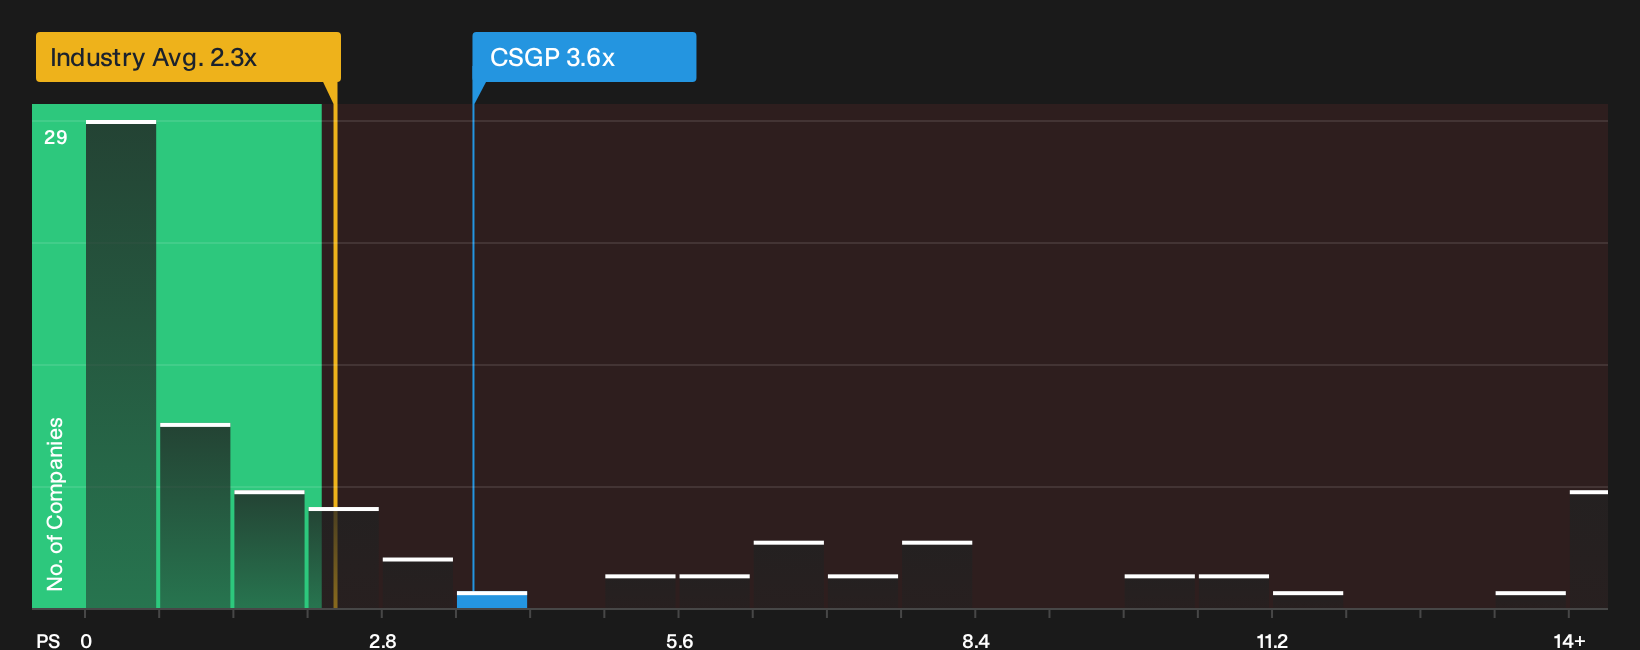
P/S suits CoStar Group because a large share of its income comes from recurring subscription revenue, so the market often anchors on sales rather than near term earnings. On this yardstick, the stock trades on a P/S of about 3.6x, compared with a Real Estate sector average of roughly 2.3x and a peer group level near 1.3x. That places the market value comfortably above broad sector and peer references, which indicates that buyers are willing to pay a premium for each dollar of revenue.
The Fair Ratio model, which blends factors like CoStar Group’s margins, growth profile, size and risk traits, points to a P/S level that sits very close to where the shares change hands now. So the current multiple lines up with what that framework suggests is a reasonable anchor rather than an obvious bargain or an aggressively rich tag. Anyone assessing the stock on this metric is really judging whether the quality and durability of its subscription driven sales stream merit paying roughly this kind of sales multiple. Explore the numbers behind CoStar Group's P/S valuation.
The CoStar Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S discussion for CoStar Group leaves off and explain what kind of growth, margins and earnings profile would need to occur for today's valuation to look either conservative or stretched. They use CoStar Group's Community page as the central hub for those scenarios. Each Narrative presents fair value as a specific, trackable hypothesis about the business that you can watch over time rather than a one off snapshot.
Bulls and bears on CoStar Group are looking at the same subscription engine but reaching very different conclusions about how much execution risk is already in the price.
Bull case: 14% undervalued
"The key thing that has to go right is that CoStar Group turns Homes.com, Apartments.com, Zonda, international portals and AI products into a durable, profitable multi-vertical platform..."
Discover why this Narrative puts CoStar Group at 14% undervalued.
Bear case: 28% overvalued
"Although Homes.com is scaling rapidly with rising awareness and engagement, the residential portal strategy still requires sustained high marketing and sales investment to reach critical share across agents and homeowners..."
Explore why this Narrative puts CoStar Group at 28% overvalued.
The share price is only one chapter in the CoStar Group story
CoStar Group’s current valuation tells you what the market is paying today, but analyst projections for revenue and earnings a few years out offer a separate lens on what could lie ahead. Explore where analysts expect CoStar Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com