


Atmos Energy (ATO) just raised about $697.5 million through senior unsecured fixed rate notes due 2036. This funding move puts fresh attention on its balance sheet and long term financing costs.
Atmos Energy’s latest bond sale comes at a time when the share price has eased over the past quarter, with a 90 day share price return that declined 7.73%. However, the 3 year total shareholder return of 60.15% and 5 year total shareholder return of 98.54% still present a far stronger long run picture of compounding returns.
Scan how Atmos Energy’s bond move compares with peers raising capital and identify regulated utilities with sturdier balance sheets using our hand-picked 32 resilient stocks with low risk scores today.
Bulls see Atmos Energy using this fresh US$697.5 million to support a regulated gas network and a steady compounding record. Bears focus on higher debt costs and a share price that slipped recently. Which story do the current valuation markers back up?
Most Popular Narrative: 12% Undervalued
Against a last close of $163.95, the most followed valuation narrative for Atmos Energy points to a fair value of about $185.55. As a result, the bond raise now gets judged through that lens of an implied discount.
Major multiyear capital investment programs, including about US$4.2b of fiscal 2026 capex with roughly 87% to 89% directed to safety, reliability and modernization, continue to expand the regulated asset base and support future rate filings that can increase regulated revenue and operating income.
See why 14 investors see Atmos Energy as 12% undervalued.
Result: Fair Value of $185.55 (UNDERVALUED)
Still, that upbeat Atmos Energy story can fray if the US$4.2b 2026 capex plan strains free cash flow, or if legal and safety costs rise further.
Find out about the key risks to this Atmos Energy narrative.
Another View: Cash Flows Paint a Tougher Picture
The fair value story for Atmos Energy changes when the focus moves from earnings multiples to cash generation. Our DCF model indicates a future cash flow value of about $133.68 per share, which is below the current $163.95 price and presents the stock as overvalued using this framework. Which lens do you rely on when actual cash must fund that US$4.2b capex plan?
For readers who lean on cash flow models to stress test bond fueled growth stories, Look into how the SWS DCF model arrives at its fair value.
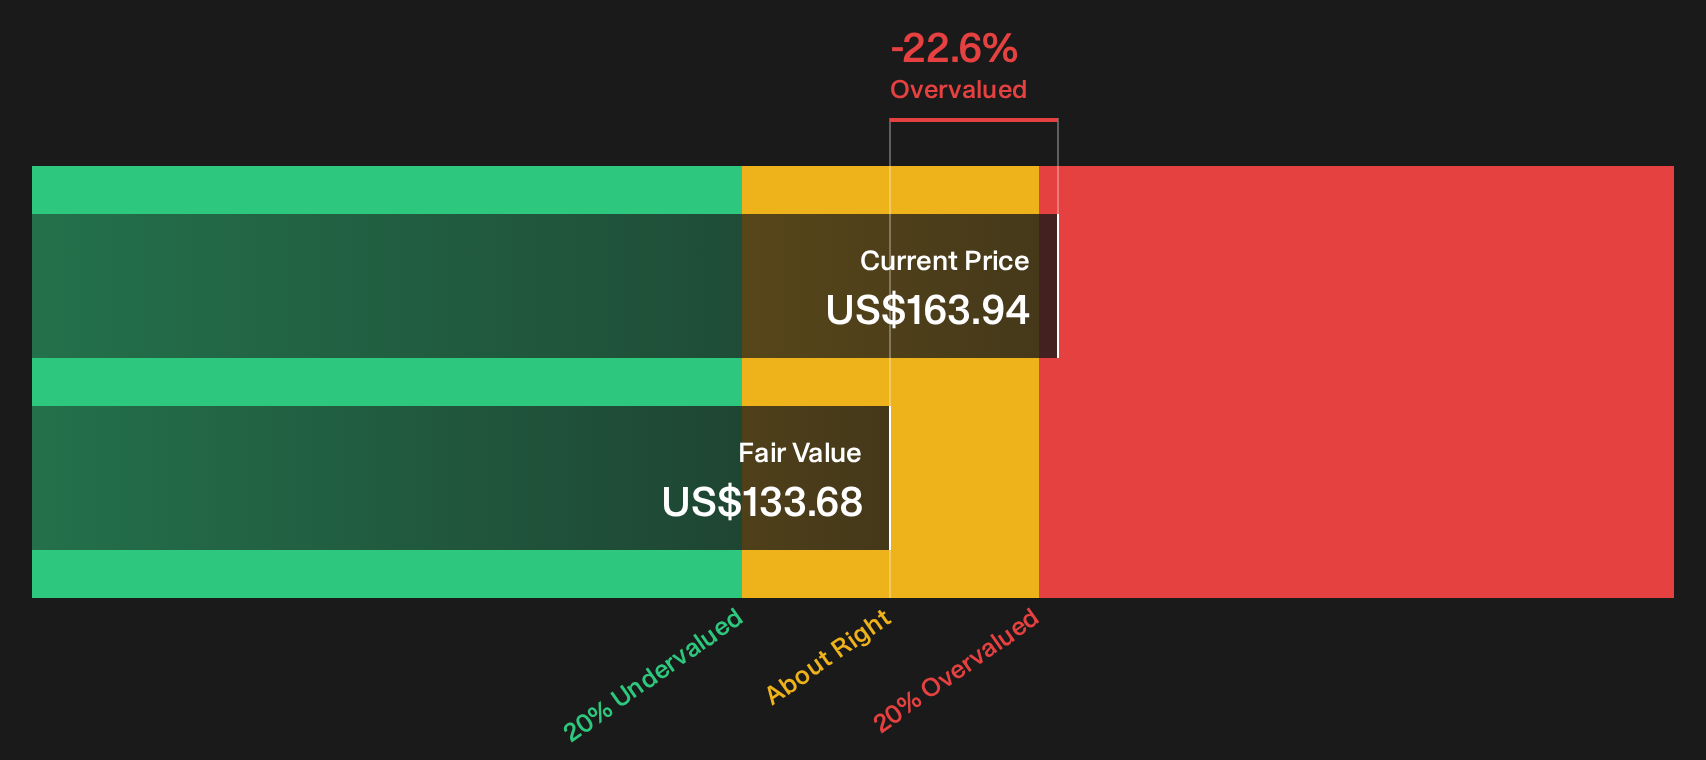
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Atmos Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Atmos Energy so far. Act quickly, review both the upside and the downside, then weigh 2 key rewards and 2 important warning signs carefully.
Looking for more Atmos Energy sized ideas?
Do not stop your research with Atmos Energy. Broaden your watchlist with fresh ideas based on clear criteria so you are not caught reacting late.
- Target potential mispricings early and scan a curated set of quality candidates using the 32 high quality undervalued stocks.
- Build a cash flow focused income stream and assess companies offering robust payouts through the 8 dividend fortresses.
- Strengthen your downside protection and review companies screened for balance sheet resilience via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com