


How the new debt offerings shape the California Water Service Group story
California Water Service Group (CWT) has just priced and completed several fixed income offerings, including senior unsecured notes and first mortgage bonds, aimed at refinancing existing borrowings and funding general corporate purposes.
Across the group and its Cal Water subsidiary, the business is raising a combined $275,000,000 through a mix of senior unsecured notes and secured bonds with maturities stretching from 2031 out to 2056. For equity holders, the headline question is how this extra long term funding changes the risk and reward profile of the stock rather than the bond coupons in isolation.
The unsecured portion includes $75,000,000 of 6.08% senior notes due December 15, 2031 and $50,000,000 of 6.41% senior notes maturing December 15, 2036, both priced at 100% of principal and ranking equally with existing obligations under the group credit agreement. On the secured side, Cal Water is issuing $50,000,000 of 6.49% first mortgage bonds due 2046 and $100,000,000 of 6.54% bonds due 2056, backed by liens on its properties subject to permitted exceptions.
Management plans to use the proceeds to retire existing debt and for general corporate uses permitted under California Public Utilities Code Section 817, rather than to fund a specific acquisition or large one off project. That focus on refinancing means the key issues for you are interest cost, refinancing risk and how this layered maturity schedule interacts with California Water Service Group's regulated utility model and long dated asset base.
Recent trading shows momentum fading. The 90 day share price return is down 11.24%, even though the year to date share price return is up 7.22% and the 3 year total shareholder return is 4.37%. This frames California Water Service Group's new long term debt in the context of a stock that has lagged over the longer term while investors reassess risk around higher funding costs.
Spot fresh opportunities by comparing California Water Service Group's new debt profile with 32 resilient stocks with low risk scores, which combines resilient balance sheets with measured risk.California Water Service Group looks like a solid regulated utility on the surface, yet the share price has lagged and fresh long term debt is now in the mix. Is that combination actually priced fairly today?
Most Popular Narrative: 14.3% Undervalued
California Water Service Group last closed at $46.05 compared to a widely followed fair value estimate of $53.75. This points to a gap that the narrative links to capital recovery and regulatory support rather than short term sentiment.
Accelerating capital investment in water infrastructure and modernization is now backed by a roughly 11% 10 year growth capital CAGR and management expectations for nearly 12% rate base CAGR to around US$3.5b by 2028. This can support higher regulated revenue and earnings capacity for California Water Service Group.
See why 4 investors see California Water Service Group as 14% undervalued.
Result: Fair Value of $53.75 (UNDERVALUED)
Still, the California Water Service Group story can be knocked off course if regulators take a tougher line on cost recovery or if PFAS reimbursements fall short of expectations.
Find out about the key risks to this California Water Service Group narrative.
Another View: What P/E Says About California Water Service Group
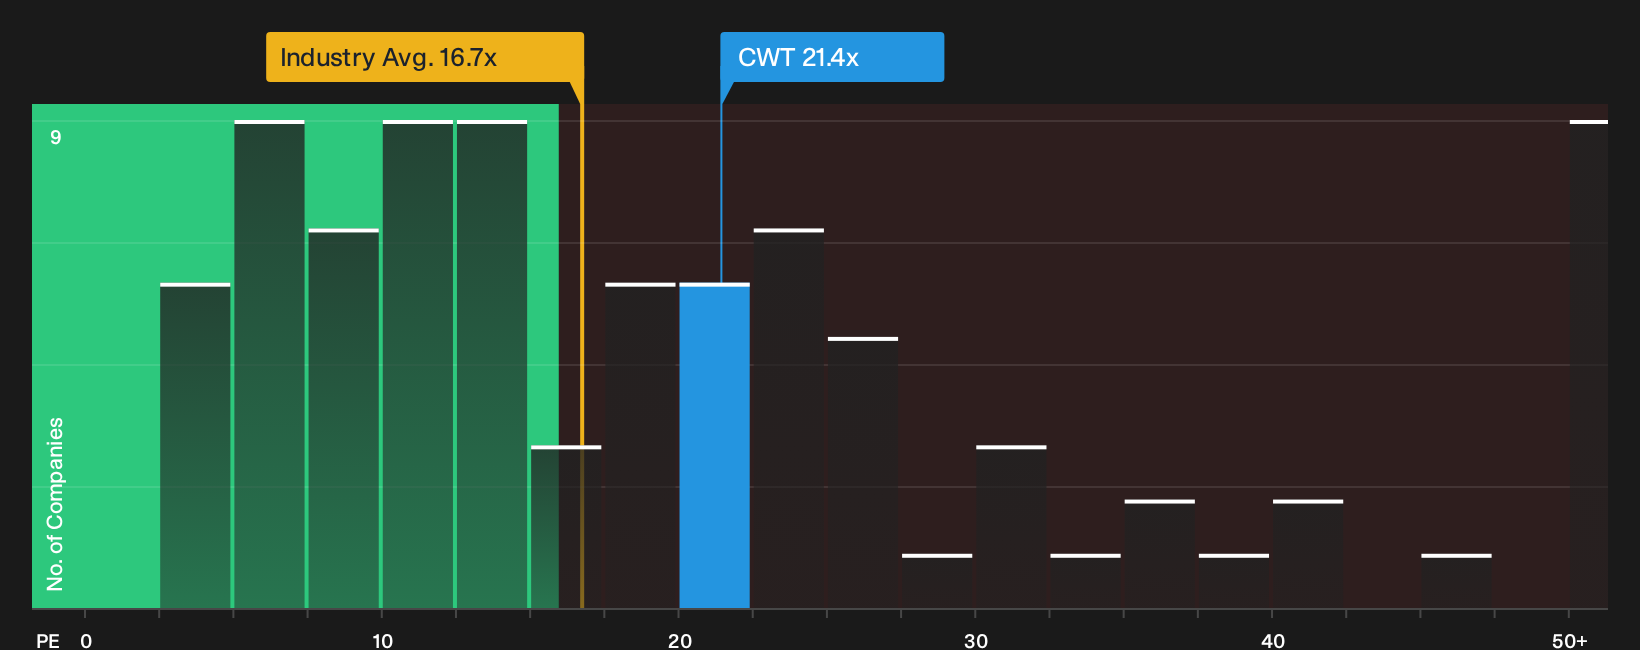
Analysts see California Water Service Group as 14.3% undervalued based on their fair value of $53.75 versus the current $46.05. The P/E ratio tells a different story. At 21.4x earnings, CWT trades richer than the global Water Utilities average of 16.7x and above its own fair ratio of 19.2x, which points to limited margin for error if things do not go to plan.
When a stock screens as undervalued on one model yet looks expensive relative to both its sector and its fair ratio, it raises a simple question for you. Is the gap a genuine opportunity, or just payment upfront for a growth path that still has execution risks attached to it?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals often create the most interesting setups, especially when California Water Service Group carries both flagged issues and clear positives in the background. Act while the information is fresh by weighing those cross currents for yourself with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond California Water Service Group?
Do not stop your research at California Water Service Group when a wider watchlist could reveal opportunities that fit your risk tolerance and income goals even better.
- Target resilient compounding potential by scanning a 32 high quality undervalued stocks that pairs quality fundamentals with prices that may not fully reflect them yet.
- Strengthen your income stream by reviewing 8 dividend fortresses built around higher yield payouts with a focus on staying power.
- Tighten your risk profile by filtering for list of solid balance sheet and fundamentals (25 results) that can better handle shocks and funding pressure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com