


- Grounded Lithium Corp. reported pre feasibility study results for the Kindersley Lithium Project with Denison Mines, including the first mineral reserves declared for the area and confirmation of Denison's option to earn up to a 75% working interest.
- The pre feasibility milestone moves the Kindersley asset further along the development path, giving Denison Mines clearer visibility on resource quality, project scale and potential capital needs for any deeper involvement.
- This development could influence Denison Mines' investment narrative as the Kindersley pre feasibility results provide more detail on the project's potential development pathway.
Scan opportunities across uranium and battery metals by lining up Denison Mines alongside a hand picked field of 16 nuclear energy infrastructure stocks shaping the next phase of energy infrastructure.
What Is Denison Mines' Investment Narrative?
Owning Denison Mines is essentially a call on future uranium production plus optionality in related battery metals. The core thesis still hinges on getting projects like Wheeler River into production, managing high upfront spending and doing it without stretching the balance sheet while the business has limited revenue today at CA$4.1m and continues to report losses. The new Kindersley Lithium pre feasibility study adds another potential avenue for long term cash flow if Denison earns into the project, although near term it does not change that execution and capital access remain central.
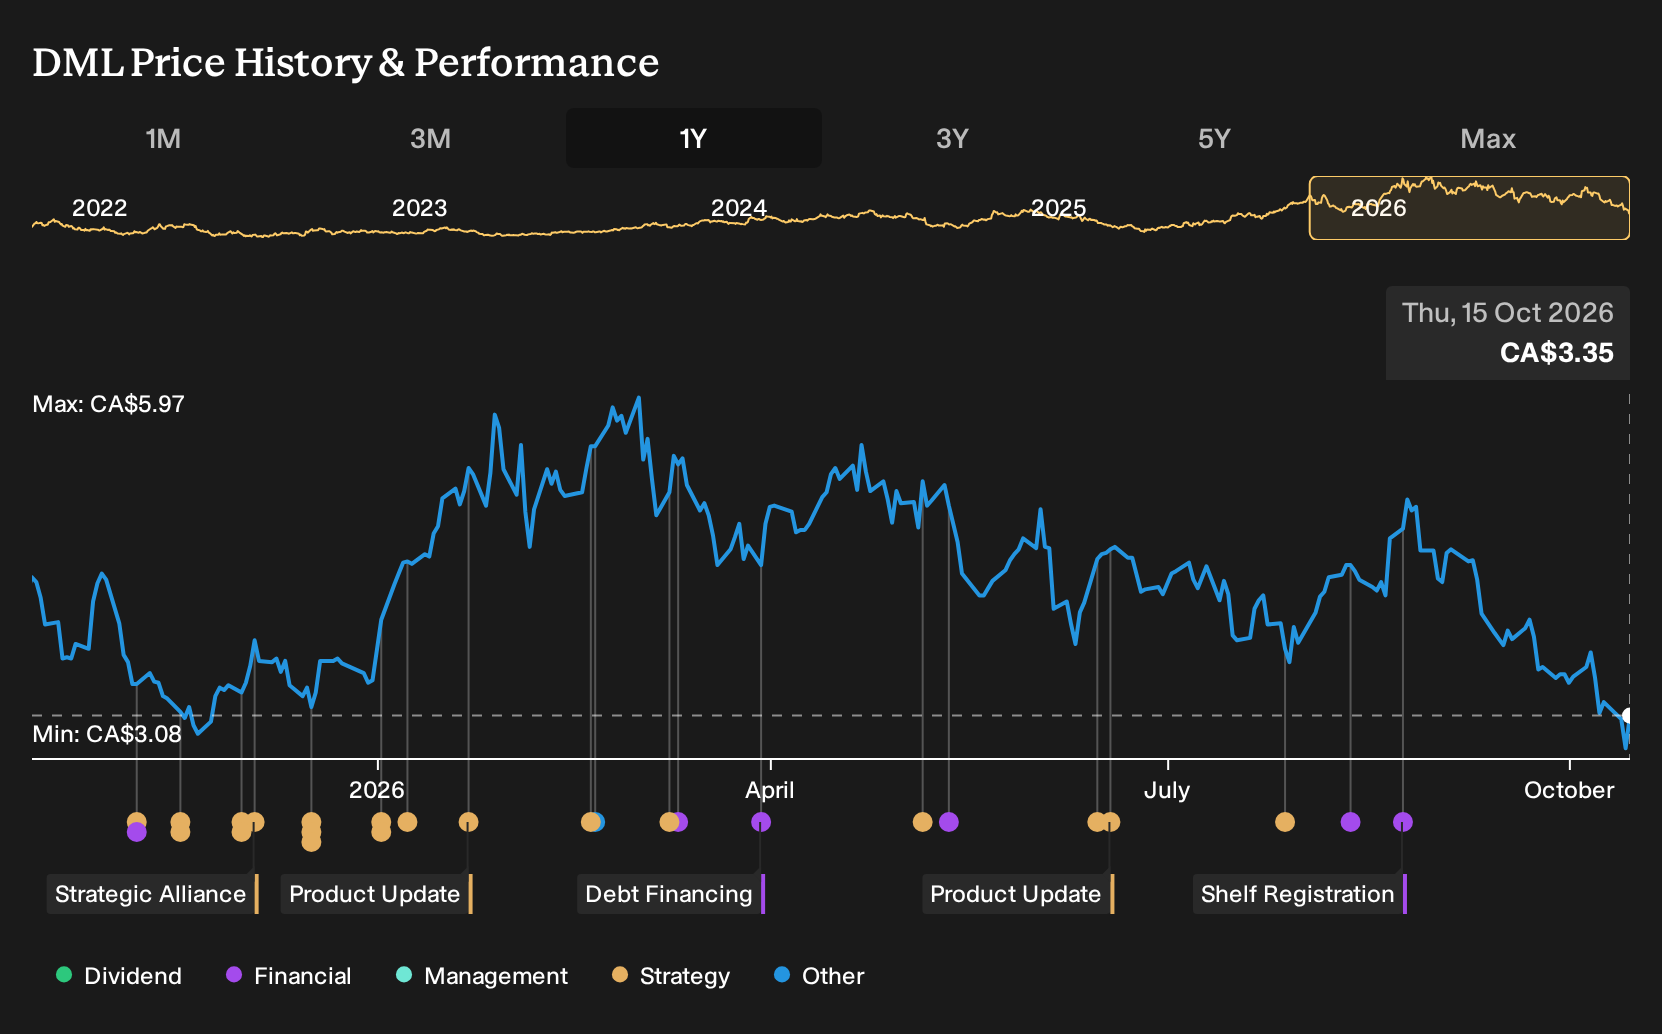
In the short term, the key catalysts are project de risking milestones, funding decisions and any clarity around timing to meaningful cash generation. The Kindersley study gives more technical detail and could help Denison Mines frame future capital allocation. At the same time, it underlines how much spending sits between today and any payoff. Analysts currently see upside and forecast strong revenue and earnings growth, but with the share price down around 19% year to date and one year total return down about 22%, the market is still treating this as a high execution story.
Even so, there is a structural wrinkle in the Denison Mines story once you look closely at how those future projects are likely to be funded...
There's only one way to know the right time to buy, sell or hold Denison Mines. Head to Simply Wall St's company report for the latest analysis of Denison Mines's Fair Value.
Exploring Other Perspectives
Fair value estimates for Denison Mines from the Simply Wall St Community span from CA$0.05 to about CA$13.50 across 3 separate viewpoints, so you are seeing everything from deep pessimism to very optimistic pricing. Those opinions were formed before the Kindersley Lithium pre feasibility milestone, which could prompt you to revisit assumptions and compare several alternative views.
Explore 2 other Denison Mines fair value estimates, including one that suggests as much as 303% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Denison Mines research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Denison Mines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Denison Mines' overall financial health at a glance.
Looking For More Investment Ideas Beyond Denison Mines?
Once you have a view on Denison Mines, it can help to widen the search and compare it with other opportunities that fit different risk and income profiles. A focused screener lets you quickly line up candidates that match the kind of portfolio you actually want to build.
- If you are hunting for potential mispriced opportunities with room for a re rating, line up a field of candidates using 6 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you than chasing the highest return, filter for companies through a 8 resilient stocks with low risk scores and see which ones fit that brief.
- If you want to surface underfollowed stories that still show solid fundamentals, cast a wider net with a 10 high quality undiscovered gems and compare what you find with your thesis on Denison Mines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com