


Lloyds Banking Group (LSE:LLOY) has put long term targets on the table, aiming for mid single digit net income growth and a cost income ratio below 45% by 2030. Investors now have clearer yardsticks for future efficiency progress.
Lloyds Banking Group’s share price has picked up in the near term, with a 7 day share price return of 5.22%, even though the 90 day share price return is down 5.07%. The 1 year total shareholder return of 30.10% and the 3 year total shareholder return of about 19x suggest momentum has built over a longer stretch as investors weigh efficiency targets, higher interest income and recent profit strength against past volatility.
Spot opportunities with similar profitability and efficiency potential by scanning our curated list of 9 high quality undervalued stocks.Lloyds Banking Group now looks like a cleaner, more focused bank with clearer efficiency goals and a recent share price bump. The real issue is whether that progress is already included in today’s valuation.
Most Popular Narrative: 1% Undervalued
Lloyds Banking Group’s most followed narrative pegs fair value around £1.07, which is only slightly above the recent £1.06 close. As a result, the debate is less about mispricing and more about how much of the efficiency story is already in the price.
The run of the Black Horse's bank up until the summer, indeed among the better ones among its European peers, has been stellar no doubt. Together with its decent dividends and buybacks, total return for shareholders that bought into the company at the beginning of the year was a healthy 20 per cent at its top back in early August. For investors in the euro area, there even was an additional return of some 2 per cent due to the strength of Sterling, not bad at all for a presumably stodgy, UK-only High Street bank.
See why 5 investors see Lloyds Banking Group as 1% undervalued.
According to PittTheYounger, this leaves Lloyds Banking Group looking like a solid, income friendly holding where valuation already reflects a lot of the forecast revenue growth and efficiency ambition, rather than a clear cut bargain or obvious sell case.
Result: Fair Value of £1.07 (ABOUT RIGHT)
Still, a bank profits surtax or weaker government support for growth could pressure Lloyds Banking Group’s earnings power and quickly challenge this fair value narrative.
Find out about the key risks to this Lloyds Banking Group narrative.
Another View: Multiples Hint At A Richer Price
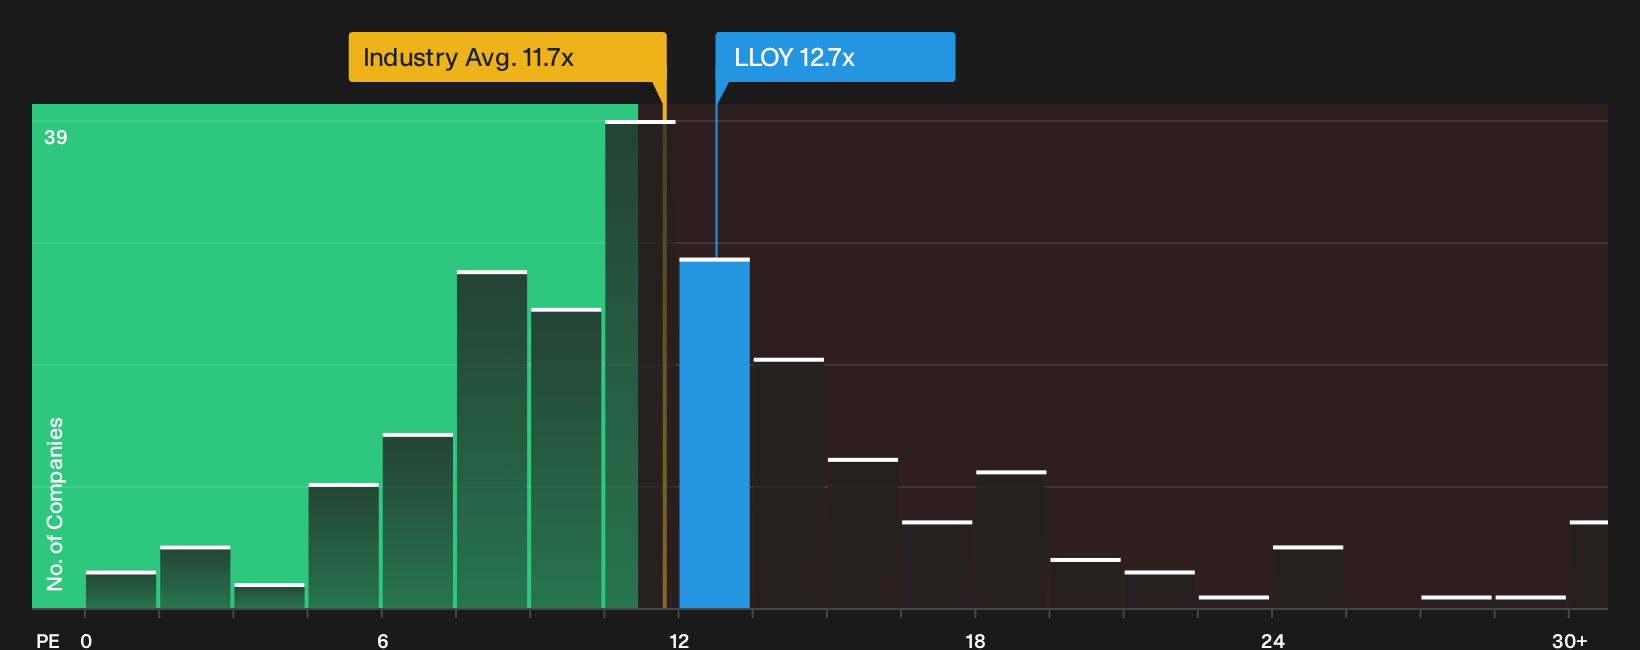
Lloyds Banking Group might look about fairly priced on the £1.07 narrative fair value. However, the current P/E of 12.7x is higher than both UK peers at 11.3x and the European banks average at 11.7x, and also above a fair ratio of 10.1x. This raises the question of how much cushion really exists if sentiment cools.
See what the numbers say about this price, and how the market could shift toward that fair ratio, in our valuation breakdown. Then decide which signal you trust more, the narrative fair value or what the multiple gap is implying for future returns See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Lloyds Banking Group so far. Take a closer look at the underlying numbers, weigh the optimism against the concerns, and decide where you stand with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Lloyds Banking Group?
If you stop with Lloyds Banking Group, you risk missing other strong opportunities. Use the screener to widen your watchlist and sharpen your next move.
- Target reliable cash generators by reviewing companies with robust finances using the list of solid balance sheet and fundamentals (9 results).
- Hunt for mispriced quality by scanning our curated pool of 9 high quality undervalued stocks.
- Build a sturdier income stream by checking out a focused set of 4 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com