


Japan’s economy minister is urging investors to rethink the old deflation story, which shines a fresh light on solid Japanese businesses that already produce healthy cash and carry manageable debt. When sentiment shifts, quality and price often reconnect quickly. This article looks at three high quality Japanese stocks that currently trade at undemanding valuations, and explains why they might appeal to investors hunting for mispriced strength.
The three stocks in this article are only a small sample, and the full screen on Simply Wall St surfaced 12 more high quality Japanese businesses with equally compelling stories that are not covered here. To identify and analyze your own shortlist of candidates that combine strong cash generation, robust balance sheets and appealing value signals, head straight to the High Quality Undervalued Stocks screener
NEXTAGE (TSE:3186)
NEXTAGE runs a nationwide used and new car dealership network in Japan. It earns ¥775.8b from automobile sales and related services such as maintenance, inspections and insurance, which fits the high quality cash flow theme. The group is valued at about ¥203.7b.
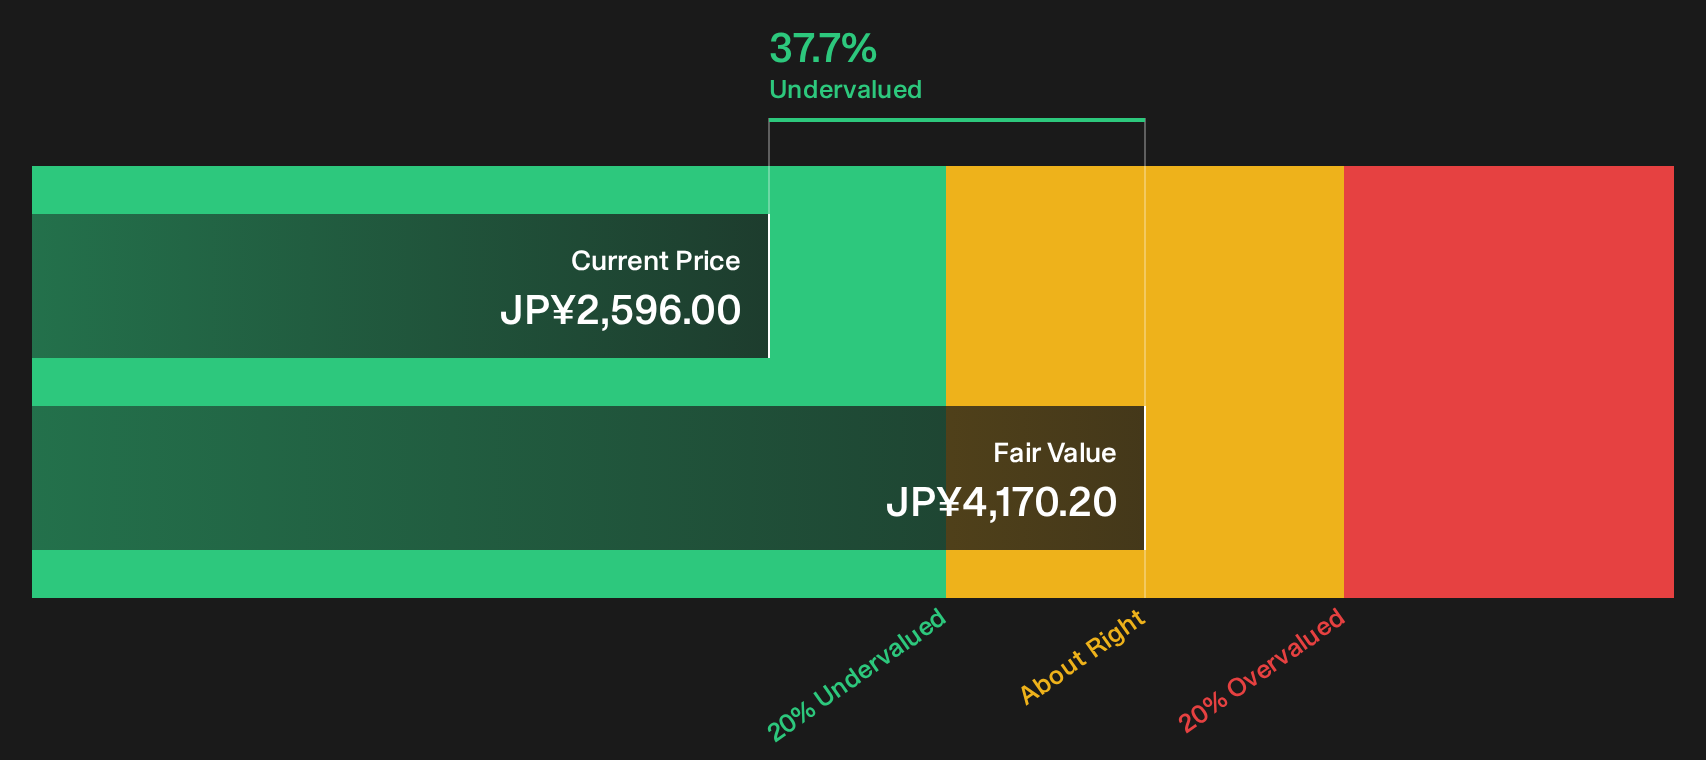
NEXTAGE combines a core used car business that generates steady cash with a P/E of 10.9x against a sector on 13.3x and a price that sits 37.7% below estimated fair value. That mix of earnings characteristics and current pricing is sensitive to any change in a single pressure on its balance sheet.
That pressure point deserves a closer look through the 4 key rewards and 2 important warning signs (1 is major!) so you can see what might be masking or accelerating the NEXTAGE story.
Yokohama Financial Group (TSE:7186)
Yokohama Financial Group runs a commercial bank focused on lending and deposit services for Japanese SMEs and households, a setup that naturally fits a cash flow and balance sheet driven value screen. It generates about ¥399.4b from banking in Japan and carries a market value near ¥1.93t.
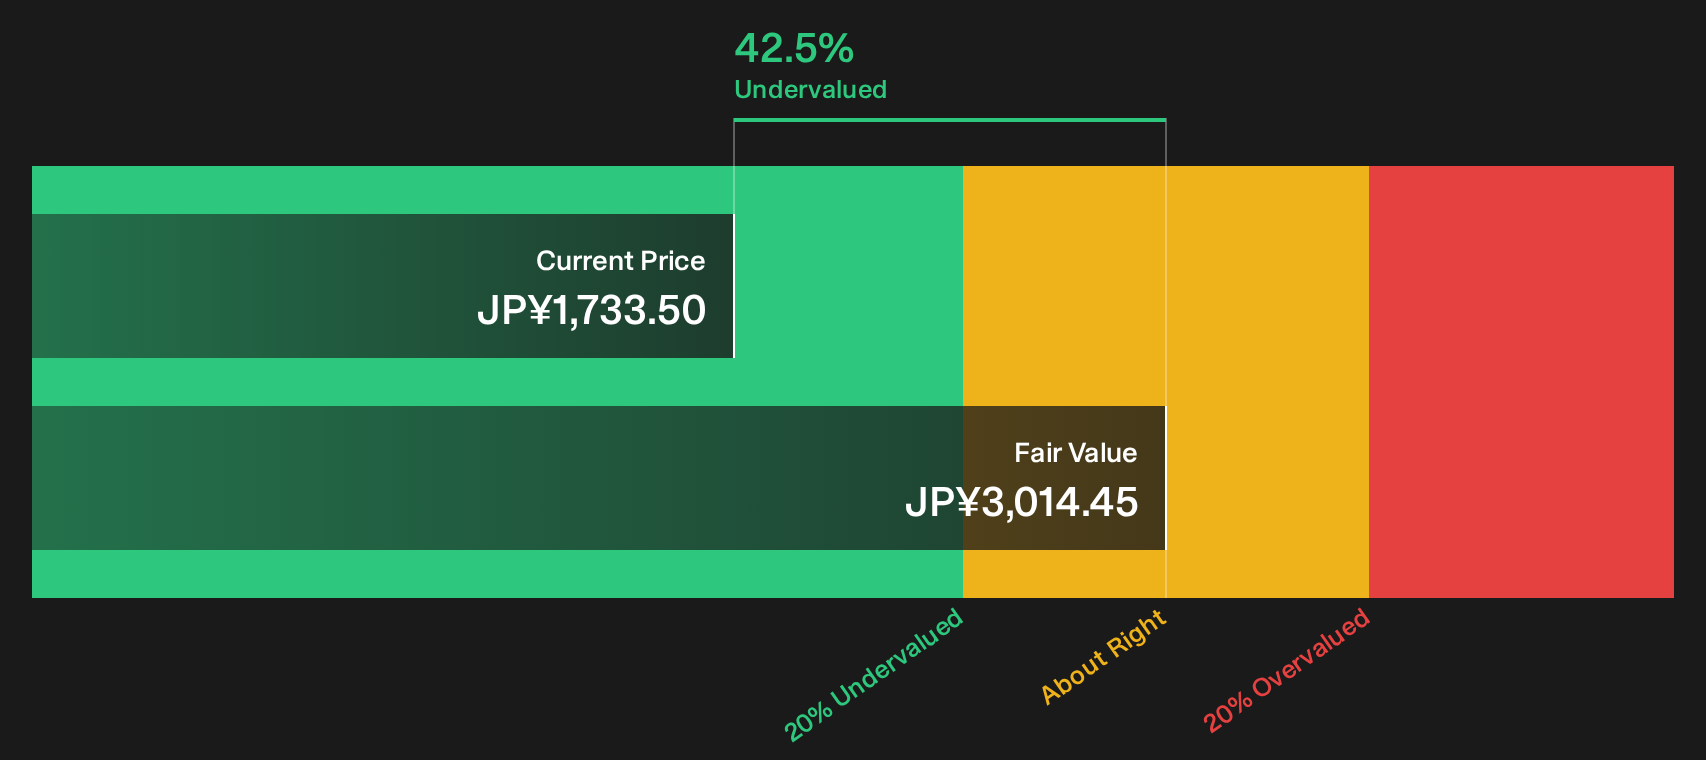
Yokohama Financial Group combines SME focused lending, net profit margins of 27.9% and a 2.71% dividend yield with a share price that trades about 42.5% below estimated fair value. Analysts see earnings growth and a P/E of 17.3x as reasonable, although one unseen balance sheet buffer could heavily influence how that quality story progresses.
That hidden buffer matters for you, so pull up the 5 key rewards and 1 important warning sign to see where Yokohama Financial Group’s quality and valuation could be decoupling.
Kasumigaseki CapitalLtd (TSE:3498)
Kasumigaseki Capital runs a real estate consulting and development platform in Japan, spanning logistics and warehousing projects, apartment hotels and healthcare facilities. It earns ¥163.8b from real estate consulting in Japan, with solar power projects helping underpin cash flows, and carries a market value of about ¥171.2b.
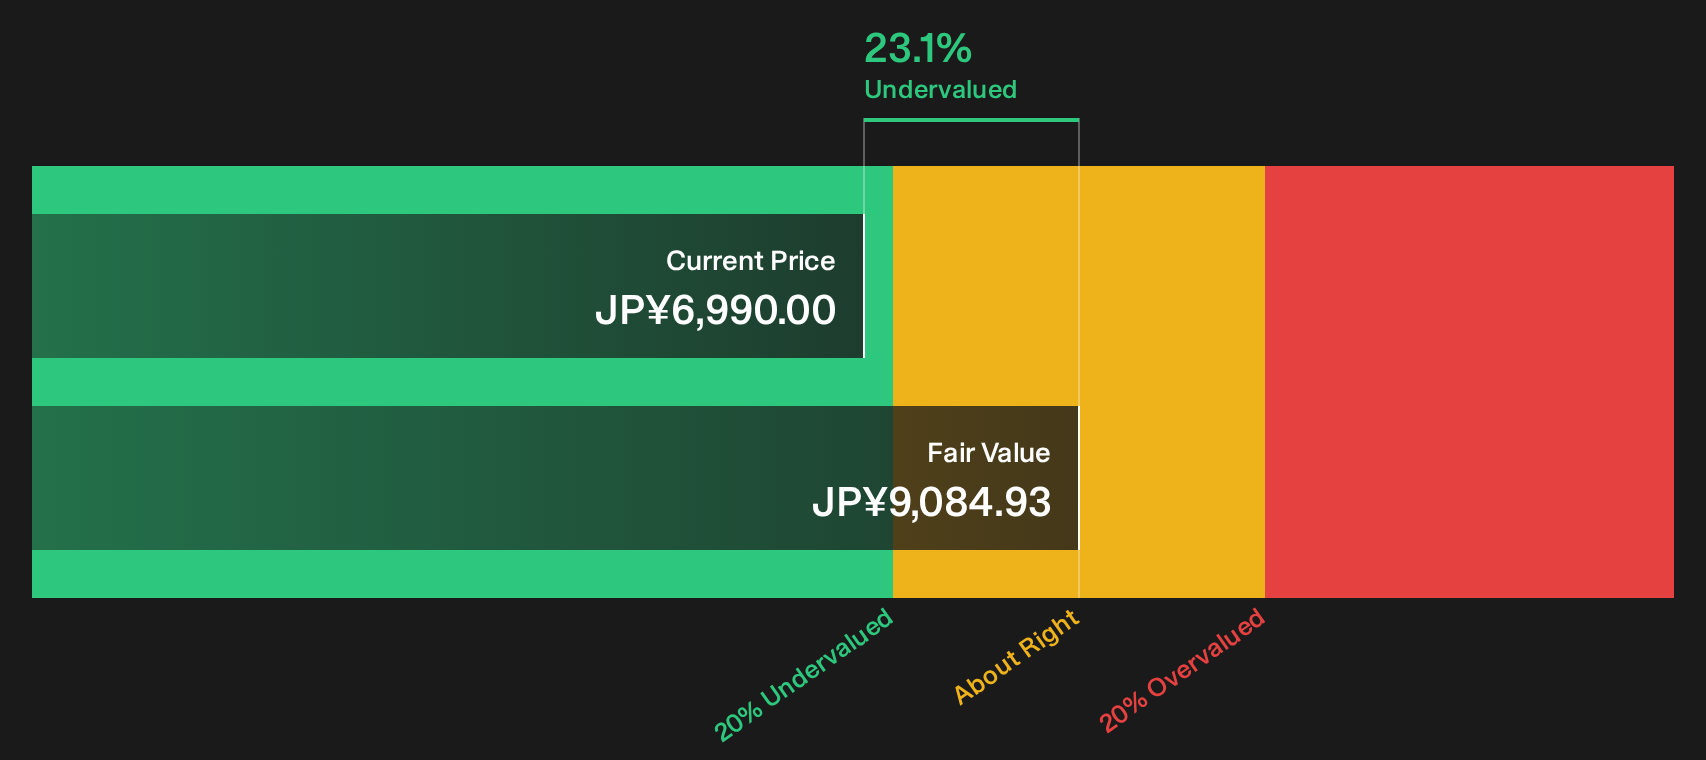
Kasumigaseki Capital links clean power assets with property development, which fits the High Quality Undervalued Stocks theme of solid cash flows and asset backing with valuation support. Earnings and guidance released in October 2026 describe rising profits and dividends, yet everything depends on how one pressure point between debt, cash generation and payouts evolves.
That delicate balance is what you tap into with the 4 key rewards and 5 important warning signs (2 are major!), where Kasumigaseki Capital’s debt, cash and dividend trade offs come into sharp focus.
Seeking Fresh Alternatives Before Others?
Fresh ideas do not stay hidden for long. By the time momentum is flying, the best entry points can be gone. Scan these under the radar lists and consider taking action while they are still developing.
- Explore opportunities for stable income while prices are still catching up by reviewing a curated pool of income plays through the 32 dividend fortresses.
- Review potential infrastructure enablers before the story reaches broader coverage by checking the focused group in the 41 power grid technology and infrastructure stocks.
- Evaluate hardware-related opportunities by scanning a targeted list of chip and data center suppliers in the 94 AI infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com