


If MKS was on your watchlist rather than in your portfolio, the return may sting. Investors who held MKS over the past year are up 66.6%, including dividends. That move now sits alongside upbeat 2026 earnings headlines and capacity expansion plans, which are easy to focus on after the fact. The harder question is this. Back on 15 October 2025, what clues existed that recurring chemistry and services demand might justify treating MKS as more than just another cyclical semiconductor supplier?
The move put MKS in the middle of this trade. Scan 94 AI infrastructure stocks for other companies exposed to it.
The Two Stories Investors Had To Choose Between On MKS
The shares cost US$136 at the start of the period, which left you weighing two very different stories about what MKS could become.
On the upbeat side, the bull narrative pointed to a Fair Value of US$160, a price implied by expectations of strong, recurring chemistry and services demand tied to AI and advanced packaging, along with high switching costs from integrated equipment and consumables.
The more cautious bear case suggested a Fair Value of US$122, built on assumptions of 5.4% annual revenue growth and 10.9% profit margins, while highlighting risks from high leverage and reliance on a concentrated group of semiconductor and electronics customers.
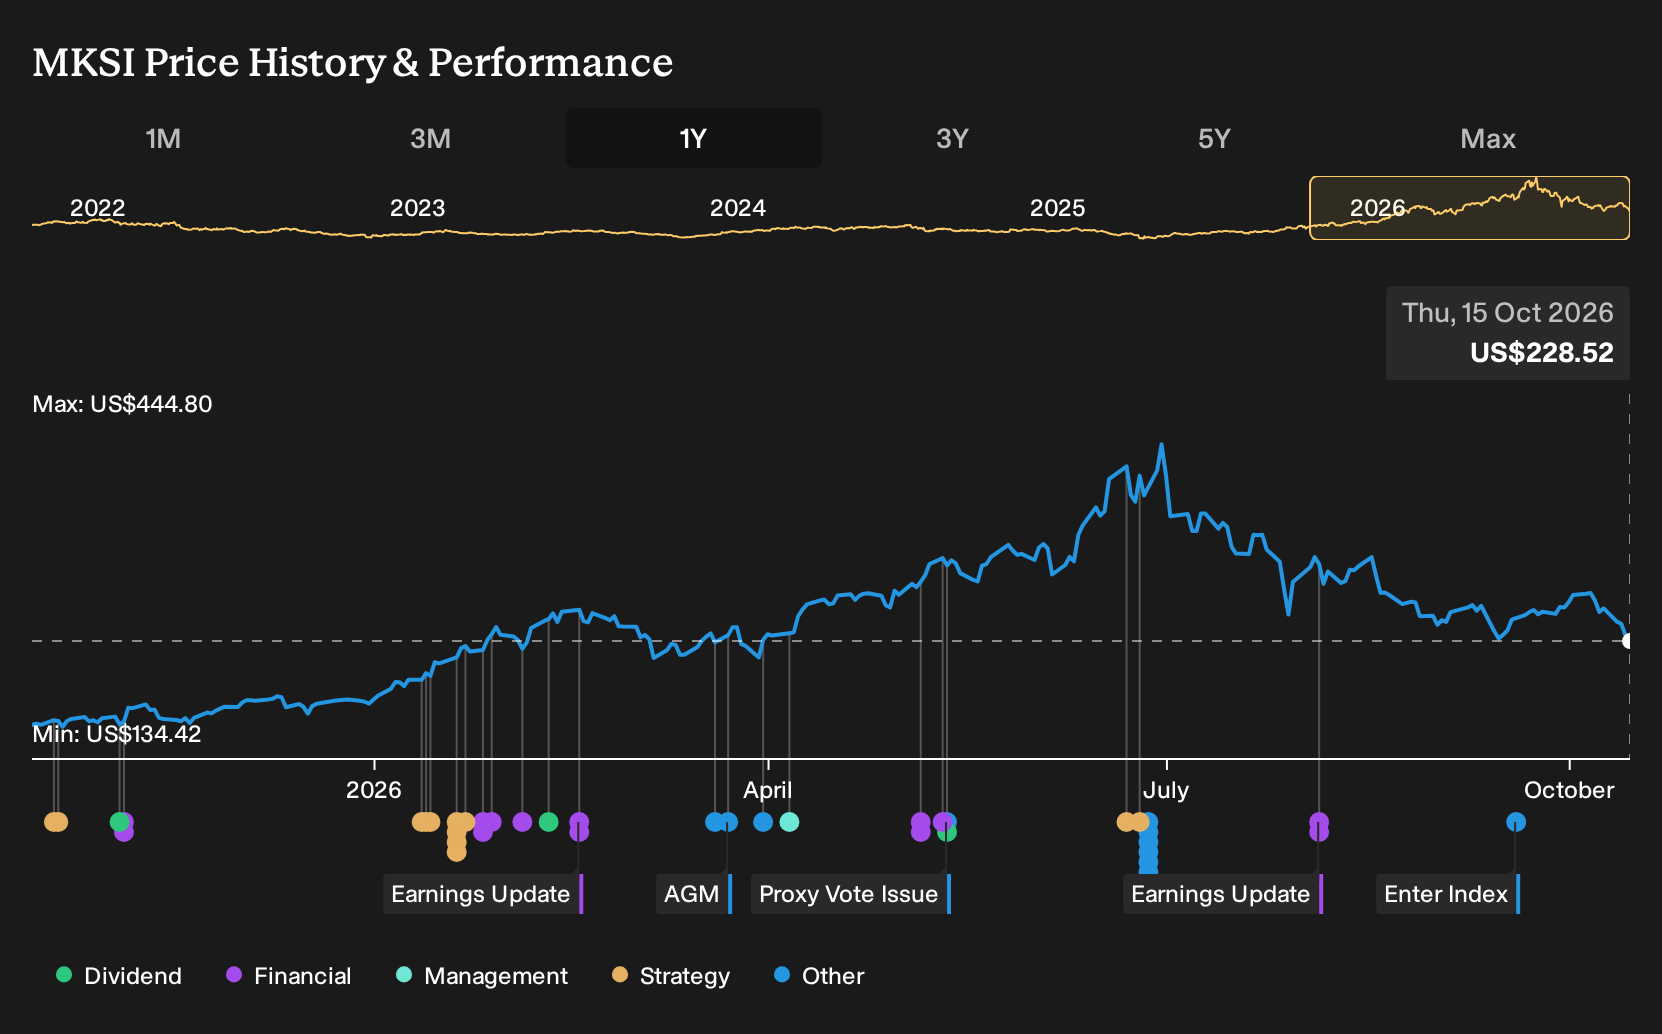
What The Evidence Did To The MKS Story
MKS Inc. reported Q2 2026 revenue of US$1.25b and net income of US$175m, with net margin rising to 14.0% from 6.4% a year earlier. That shift, alongside stronger chemistry and services contributions and new facilities in Malaysia and Guangzhou, leaned toward the optimistic case that recurring demand could support higher profitability. Insider selling and overvaluation flags pointed in the opposite direction, so the evidence cut both ways.
The decision back in October 2025 really hinged on whether recurring chemistry and services would lift margins. For a different stock, track segment mix, reported net margin and the direction of services or consumables as a share of sales to see if that assumption is genuinely playing out.
What MKS Buyers Are Being Asked To Believe Now
With MKS at US$229, the selected Narrative still places its Fair Value above the current price and ties that view to AI linked demand, recurring chemistry and service revenue, and ongoing balance sheet repair.
The argument leans heavily on those new Malaysia and Guangzhou facilities and on chemistry driven repeat sales. A buyer now has to decide whether AI related chemistry and services can keep scaling fast enough to support that higher figure.
"The deepening integration of advanced materials and chemistry equipment within MKS, supported by record chemistry equipment orders for several quarters and a rising share of AI related chemistry revenue, increases the opportunity for tools plus consumables cross selling and can support both revenue growth and higher gross margins."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Another Way AI Demand Shows Up
MKS puts chemistry and services in front of you. One step away, a different kind of plumbing quietly matters just as much.
All that extra computing power still needs to move data, connect devices, and keep workloads running.
One large supplier focuses on the chips and software that handle those jobs.
Its hardware pushes information through networks and into storage. Its software helps big customers manage private clouds, security, and complex mainframes.
If demand for AI infrastructure keeps broadening, that mix of connectivity and software control could quietly shape how this story develops.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 89% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com