


The Zhitong Finance App learned that Wall Street traders were previously caught off guard by US Treasury Secretary Scott Bessent's sudden purchase of old bonds in August, but now they are preparing for more intervention. As the Treasury prepares to update its debt management plan in November, key clues could surface on Friday.
This “treasury twist” (treasury twist) operation introduced by Bezent was originally intended to deal with soaring US yields — a pain point for the Trump administration, which promised to lower borrowing costs — and it did initially work. But by intervening in this way, Bezent actually tore up the Treasury Department's decades-long “routine and predictable” operating guidelines aimed at achieving the lowest cost of debt over time.
From a macro perspective, the move has sparked controversy over whether this fine adjustment, which injects uncertainty, will eventually make the market more volatile. On a more practical level, it alerted Wall Street to the possibility of further intervention by the Treasury Department in November's debt refinancing announcement for the next quarter — the announcement just one day after the midterm elections.
On Friday, major bond traders will receive a questionnaire from the Ministry of Finance before refinancing. Market observers say that the nature of the questions in the questionnaire may be the “Roshach Test” (psychological projection test, which refers to the market interpreting policy signals) to interpret Bezent's tendencies.
“You've already announced to the market that the current yield level is problematic,” said Vishal Kanduja, head of broad market fixed income at Morgan Stanley Investment Management. “This is why we think the next two refinancing operations — in November right after the midterm elections — will be key points.”
Martin Tobias, department strategist at Morgan Stanley Bank, said the Treasury has several options. The most common approach is to maintain the status quo: keep the current auction size unchanged for at least the next few quarters, and do not revise the forward-looking guidelines, as was done in August. Another option is to revise the forward issuance guidelines to exclude an increase in longer-term securities and instead focus on an increase in the variety of two to seven year terms.
Another option — and the most unconventional — is to clearly state how much of the Treasury's share of short-term treasury bills can be. Although the share of short-term treasury notes issued has risen, officials have never stated the upper limit they are willing to tolerate.
For Ed Al Husseini, portfolio manager at Columbia Threadneedle Investments, from a taxpayer's point of view, the best solution is to issue bonds with a term of about 5 years to finance, rather than a 30-year ultra-long bond.
“If your goal is to stop yields from rising, then you have to come up with very innovative measures,” he said.
A Treasury spokesperson did not immediately respond to a request for comment.
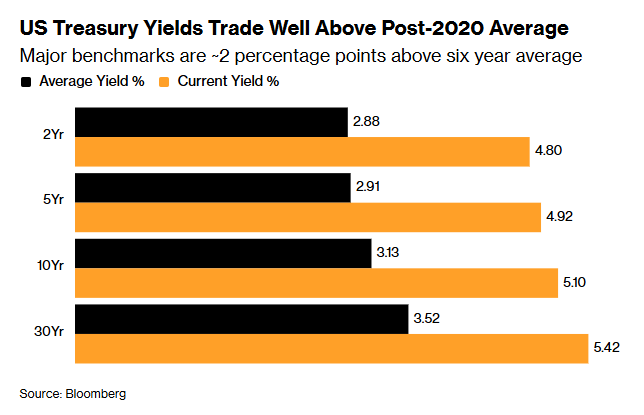
Market participants think every option is possible as long-term benchmark yields in the US and around the world are close to their highest levels in decades. Higher oil prices and the Federal Reserve's resumption of interest rate hikes — reflecting economic expansion accompanied by stubborn inflation — have combined to drive higher yields. At the same time, artificial intelligence (AI) hyperscale enterprises are borrowing heavily to finance their explosive growth, triggering global capital competition.
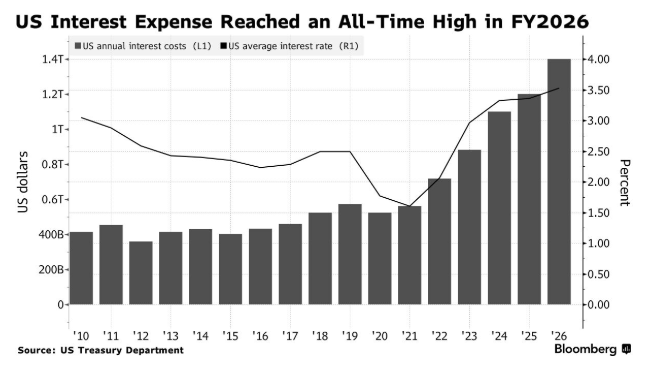
All of this is happening at a time when America's annual interest expenses have broken through the 1 trillion US dollar mark for the first time, and debt repayment costs now exceed the defense budget, making the task of financing the government even more difficult. Although Bezent has limited room to significantly reduce borrowing costs, he said he still has a “huge toolbox” and hinted that he will use every means to curb long-term returns.
Wall Street will also get another chance to express its views: the Treasury Department and a group of traders and investors (known as the Treasury Borrowing Advisory Committee, TBAC for short) will hold quarterly meetings before the announcement in early November. Although Bezent is under no obligation to adopt the group's recommendations — he even claims to be the “final player” — it is still worth listening to market participants before introducing new policies.
“TBAC still has a wealth of expertise and experience, and I think it would be wise for Bezent to listen to their opinions and take their suggestions into consideration,” said Stephen Douglas, chief economist at NISA Investment Advisors and a former Federal Reserve Bank of New York employee. “But the policy goals of the current administration and this finance minister are very different from previous administrations; they will only pursue what they think is right.”
Back in August, the Ministry of Finance made minor adjustments to its guidelines, saying that officials are evaluating potential “changes” in future sales of interest-bearing treasury bonds and floating rate notes, rather than simply “additional issuance” — this leaves room for cutting the supply of 20-year and 30-year treasury bonds. Citigroup said Friday's dealer survey may suggest a decrease in the issuance of long-term bonds, and Beisent may use weak demand for treasury bonds from pension funds (probably due to increased issuance of long-term corporate bonds) as a reason to reduce or cancel 20-year treasury bonds.
Reducing the auctions of longer-term interest-bearing treasury bonds means that the Ministry of Finance will have to further increase the supply of short-term treasury notes, or possibly introduce another product, such as a one-year variable interest rate note linked to a guaranteed overnight financing rate. In the first quarter of this year, Treasury officials asked traders if they should consider issuing such securities.
Wells Fargo strategists said last month that now is the “right time” to re-examine this idea, and said it would provide money market funds — the biggest buyers of short-term treasury notes — an alternative way to invest in shorter-term government debt.
Issuing a large number of short-term treasury notes has been a key part of the Treasury's debt financing strategy, which has continued during Janet Yellen's tenure. But as the share of short-term treasury bills rose above 22%, this dependency did cause Wall Street to worry. Now that the Federal Reserve has resumed interest rate hikes for the first time in three years, the market expects to raise interest rates by at least 0.84 percentage points in the next year, and the cost of issuing short-term treasury notes seems bound to rise.
However, some market participants don't think that additional treasury bills are a bad thing.
“There is still room for more short-term treasury bills,” said Joe Lavornia, chief economist at SMBC Nikko Securities North America. He served as Bezent's adviser during the first year of the Trump administration. “We can reduce the supply of long-term bonds and coordinate actions with the Federal Reserve because they have already discussed investment portfolios that only hold short-term treasury notes. As a result, the impact on the market of additional short-term treasury notes is limited. Because their transaction price is close to the federal funds rate, investors will absorb the issuance of interest-bearing treasury bonds, which can be accepted by all parties.”
Kanduja of Morgan Stanley Investment Management is not opposed to change. He believes that the Treasury should double the scale of repurchases and consider reducing the size of long-term bond auctions in upcoming refinancing. But he cautioned not to create more accidents.
“The predictability of the Ministry of Finance's policies must be greatly improved,” he said. “The Ministry of Finance issues debt on a daily basis. The most taboo is huge supply while policies are erratic and erratic, which annoys bond buyers.”