


Schrödinger (SDGR) is back in focus after its physics-powered platform underpinned new research in Nature on lithium-ion battery electrolytes, revealing multi-lithium ion clusters that challenge long-held battery chemistry assumptions.
Against this scientific backdrop, Schrödinger’s share price has moved sharply over 2026, with a 30-day share price return of 9.59% and a 90-day share price return of 66.32% from a last close of US$25.48. The year-to-date share price return of 41.71% contrasts with a 1-year total shareholder return of 25.46%, pointing to momentum that has picked up more recently than the longer-term record, which still includes a 5-year total shareholder return decline of 54.50%.
Scan other physics and AI driven compound discovery plays that are moving on fresh research by checking the hand picked 38 profitable AI stocks that aren't just burning cash alongside Schrödinger.
Schrödinger has rallied hard while still trading below both its own intrinsic value estimate and the average analyst target. Is that a genuine discount, or is the market correctly pricing in execution risk?
Most Popular Narrative: 14% Overvalued
Schrödinger last closed at $25.48 while the most followed narrative pegs fair value at $22.29. This implies the recent rally sits above that framework and places more weight on the story than on the model.
In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $356.2 million, earnings will be $25.4 million, and the stock would be trading on a PE ratio of 87.1x, assuming you use a discount rate of 8.2%.
Given the current share price of $25.91, the analyst price target of $22.29 is 16.3% lower. Despite analysts expecting the underlying business to improve, they appear to believe the market's expectations are too high.
See why 27 investors see Schrödinger as 14% overvalued.
Result: Fair Value of $22.29 (OVERVALUED)
Still, Schrödinger leans heavily on milestone and royalty income, and margin pressure from the predictive toxicology push could keep profitability further out than the narrative assumes.
Find out about the key risks to this Schrödinger narrative.
Another Take: Cash Flow Signals Undervaluation
The analyst narrative presents Schrödinger as 14% overvalued at $25.48, yet our DCF model points in the opposite direction. On a future cash flow basis, SDGR screens as undervalued, with an estimate of $41.82 per share. Which lens do you trust when those stories clash?
Look into how the SWS DCF model arrives at its fair value.
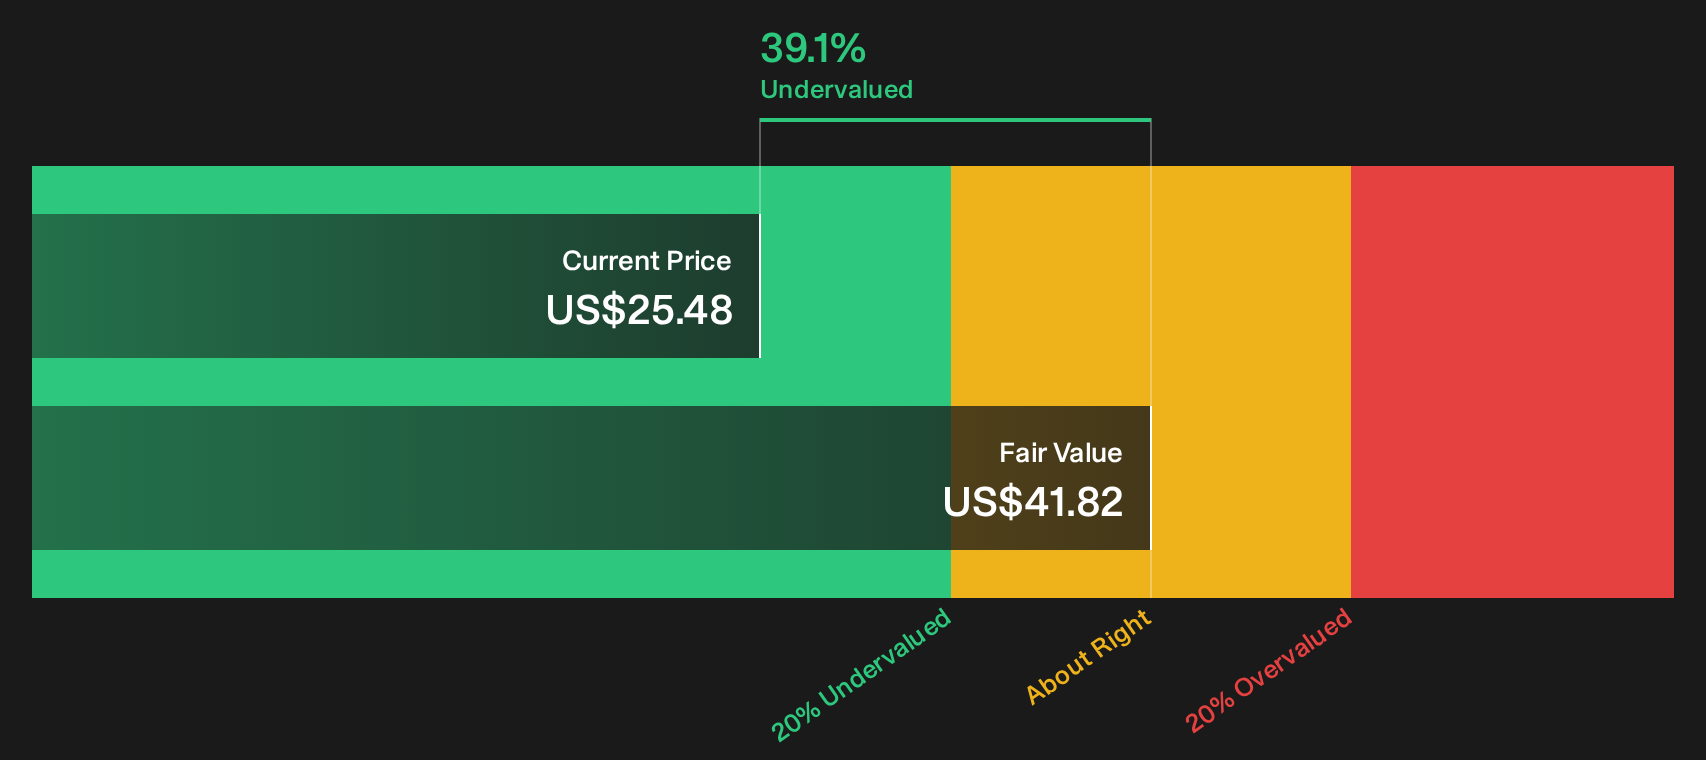
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Schrödinger for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicting stories on Schrödinger’s value can make the picture feel noisy. Move quickly, test the assumptions yourself, then weigh the 1 key reward and 3 important warning signs.
Looking for more Schrödinger-sized ideas?
If you only stop at Schrödinger, you might miss stocks that better match your risk tolerance, income needs, or value focus on the Simply Wall St Screener.
- Target steadier compounding potential by filtering for resilient businesses through the 32 resilient stocks with low risk scores.
- Hunt for mispriced opportunities by scanning the 32 high quality undervalued stocks that pair solid balance sheets with compelling valuations.
- Build a cash-focused watchlist by zeroing in on reliable payers using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com