


If you had been weighing L.B. Foster on 15 October 2025, the picture was already mixed. Government-backed precast concrete and rail projects were building a backlog, while analysts were warning about shrinking margins, funding uncertainty, and underperforming U.K. operations. For L.B. Foster shareholders, the return over the past year was 28.6%, including dividends. If you were deciding whether to buy that day, which mattered more: the infrastructure tailwind or the risk to long-run profitability?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
L.B. Foster has already moved. See which of 32 high quality undervalued stocks still trade below our estimates.
Two Competing Stories Around L.B. Foster
The shares cost US$27.35 at the start of the period, and L.B. Foster sat between two clearly opposed stories about what came next.
On the optimistic side, the bull narrative set fair value at US$29. It relied on heavier government infrastructure funding supporting Precast Concrete and Rail, with assumptions for 7.2% annual revenue growth and a future P/E of 45.8x on lower earnings.
The bear view put fair value at US$25. It focused on dependence on government projects, rail and steel cyclicality, and a smaller 6.0% revenue growth assumption paired with shrinking margins.
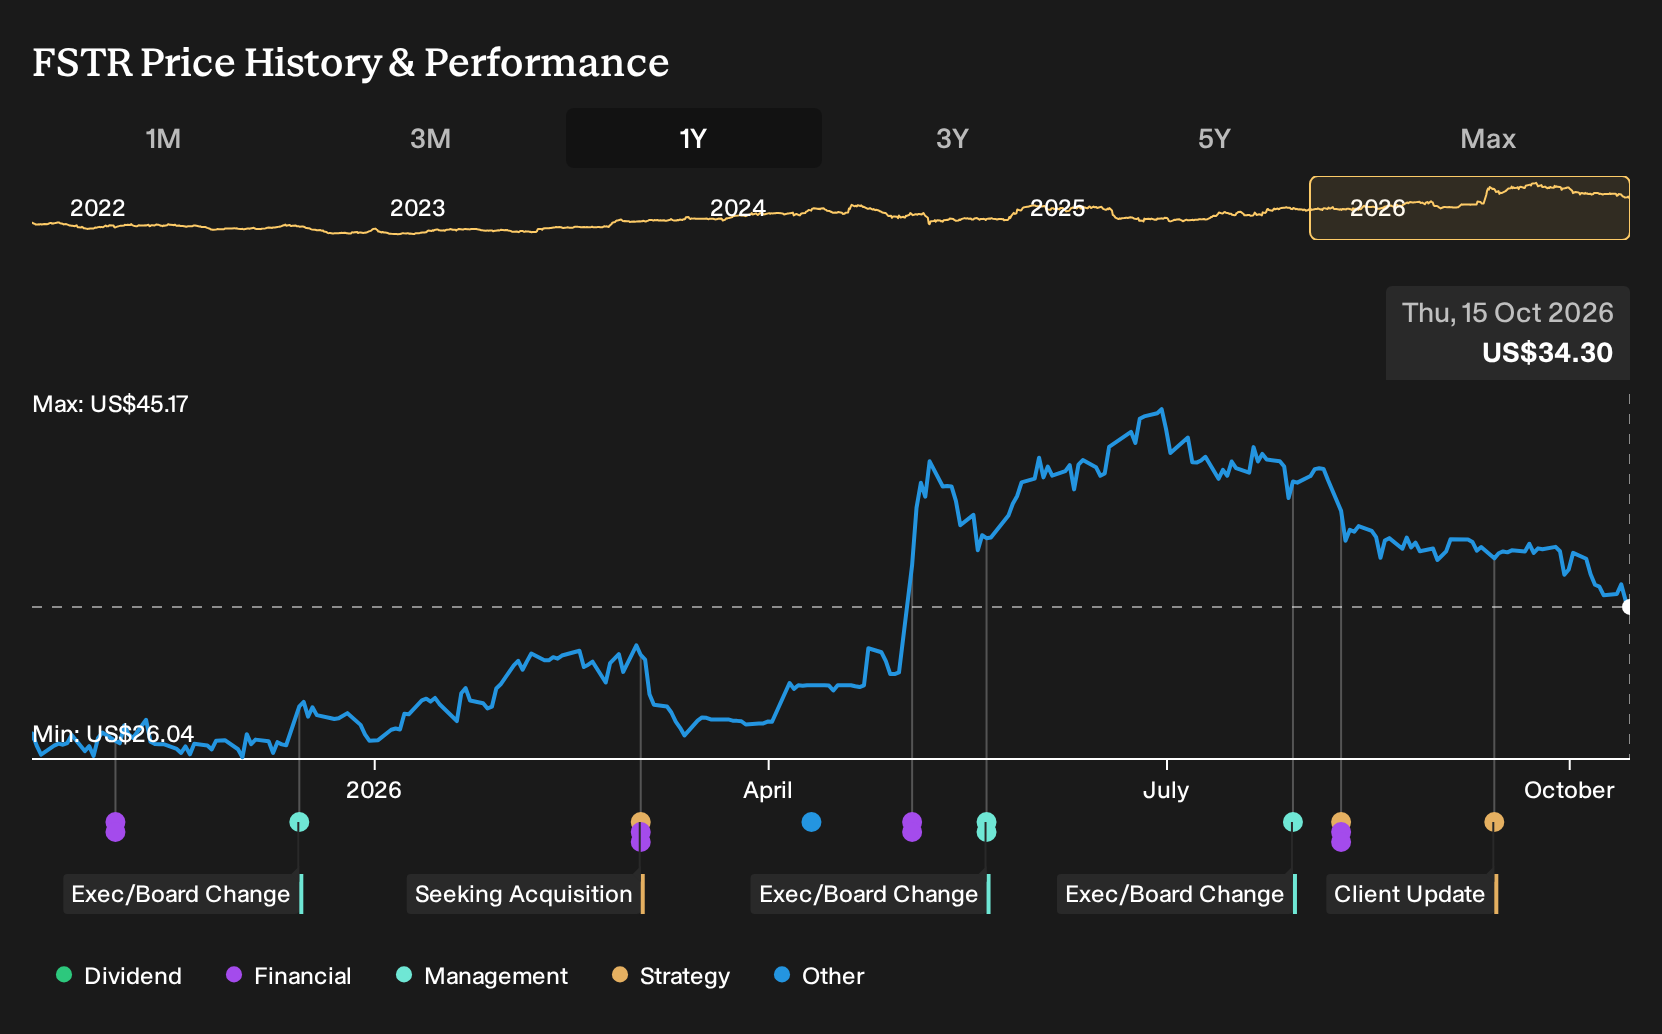
What The Q2 Results Did To The L.B. Foster Story
The clearest new fact on L.B. Foster after the October 2025 decision date was the Q2 2026 report. Revenue slipped from US$143.6m to US$138.6m, yet net income rose from US$2.9m to US$3.1m and net margin edged up from 2.0% to 2.2%. That combination of softer sales with slightly better profitability cut both ways for the original bull and bear cases.
The key assumption this period tested was margin resilience in the face of revenue pressure. When you assess another contractor tied to public projects, track whether small changes in net margin offset weaker top-line volume or simply mask it for a quarter.
What L.B. Foster’s Price Already Bakes In
Today L.B. Foster trades at US$34.3. The selected Narrative places Fair Value above that level and leans on the shift toward higher margin rail technologies, precast assets, and protective coatings to explain the gap.
For that higher figure to hold, a buyer now has to judge whether the portfolio reshaping and U.K. restructuring can actually convert exits and charges into lasting cost savings.
"The main factor that has to go right is successful execution of the portfolio reshaping and U.K. restructuring so that exits and one time charges translate into the targeted cost savings and a cleaner, higher return business."
One Narrative disagrees with today's price. → See where this Narrative says L.B. Foster should trade
Looking Beyond L.B. Foster
L.B. Foster keeps your focus on rails, roads and concrete infrastructure.
Now picture another business chasing a similar mission in orbit instead.
It builds hardware and services that help satellites launch, operate and stay updated.
Those tools support communications, mapping and timing, aiming to make access to orbit feel routine.
If that backbone keeps spreading, more everyday services can build on it, leaving a sharp question about who turns dependable space access into lasting cash generation.
One Narrative has already put a figure on it. → Uncover the company trading 44% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com