


Standard Chartered (LSE:STAN) is back in focus after a twin push into digital assets, marked by a crypto trading launch in the UAE and a leadership reshuffle around its global Securities Services unit.
These moves come after a powerful run for Standard Chartered, with the share price at £21.28 and a year to date share price return of 15.4%, alongside a 1 year total shareholder return of 53.46%, helped by growing interest in its digital asset push.
Scan other banks leaning into digital finance with our curated list of 19 cryptocurrency and blockchain stocks that echo Standard Chartered's push into regulated digital asset trading and custody.
Bulls see Standard Chartered using its digital asset build out to justify a richer multiple. Bears see a mature bank taking on extra risk. Which story do the current valuation markers actually support?
Most Popular Narrative: 25% Undervalued
Against a last close of £21.28, the most followed narrative anchors fair value for Standard Chartered at £28.54. This frames the recent digital asset push inside a much broader earnings and efficiency story built on an 8.4% discount rate.
Record income in Wealth Solutions, strong investment products growth, and consistent affluent net new money of US$42b year to date point to a growing fee based wealth franchise that can support income and earnings resilience even when net interest income is under pressure.
See why 0 investors see Standard Chartered as 25% undervalued.
Result: Fair Value of £28.54 (UNDERVALUED)
Still, this bullish Standard Chartered story hinges on fee engines holding up, and on credit costs not rising sharply in sovereign or commercial real estate exposures.
Find out about the key risks to this Standard Chartered narrative.
Another View: What Standard Chartered's P/E Is Telling You
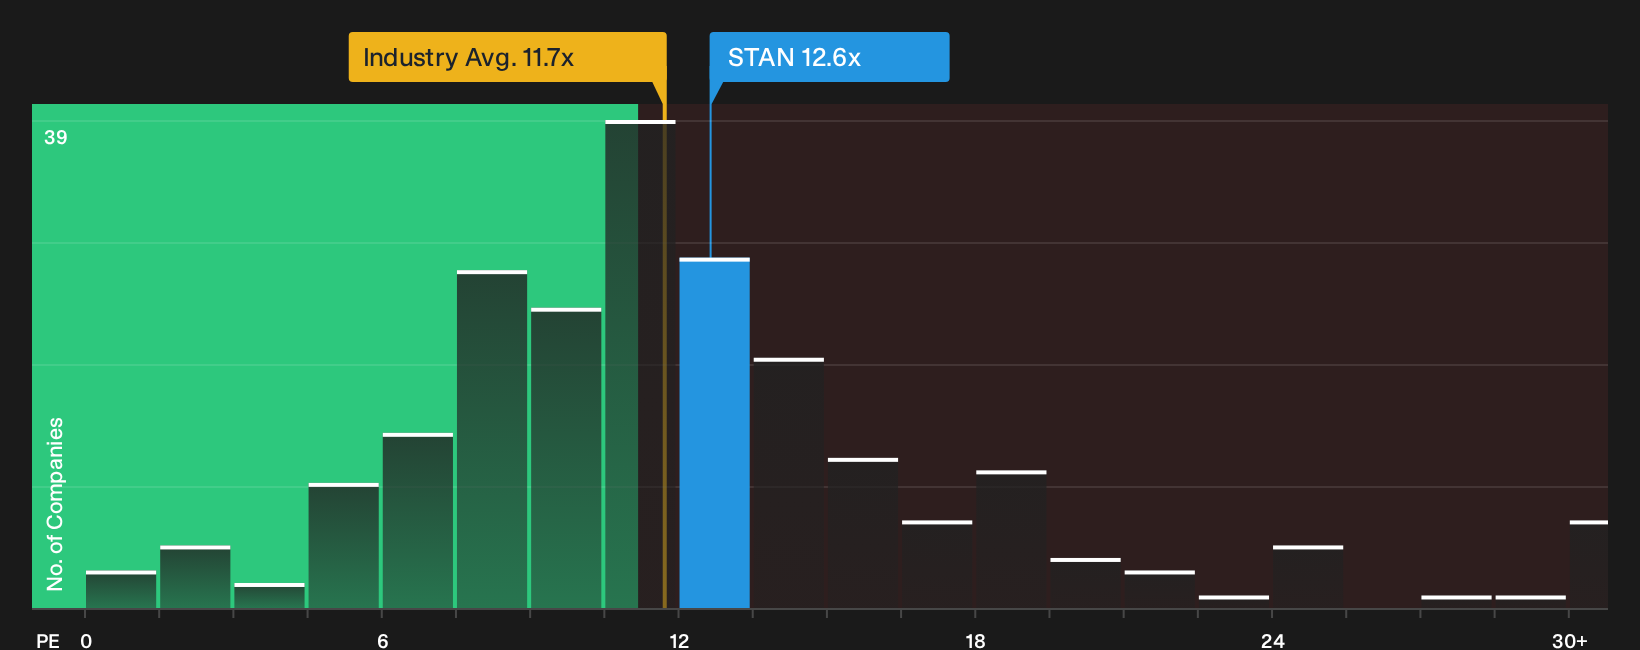
The 25% undervalued story contrasts with a very different signal when you look at the current P/E. Standard Chartered trades on 12.6x earnings, compared with 11.7x for the wider European banks group and 11.3x for closer peers, while the fair ratio is 9.9x.
This richer multiple suggests the market already prices in stronger delivery, leaving less room for error if earnings or credit costs disappoint. Is that premium a comfort, or is it a margin of safety you would rather have on your side?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear message? With both one or more risks and one or more potential rewards on the table, now is the time to review the data yourself and decide whether the current price justifies your conviction. Start with 3 key rewards and 3 important warning signs.
Looking for more Standard Chartered sized ideas?
If you stop with Standard Chartered, you only see one corner of the opportunity set. Cast a wider net now so you do not miss what fits you better.
- Target strong cash generation and quality balance sheets by scanning the 9 high quality undervalued stocks that pair resilient finances with pricing that still looks reasonable.
- Prioritise resilience over drama and review the 4 resilient stocks with low risk scores that keep risk scores in check while still offering meaningful upside potential.
- Hunt for future leaders early and work through the 5 high quality undiscovered gems that combine solid fundamentals with limited market attention right now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com