


Blackstone’s plan to pour capital into AI data centres and power projects shows how quickly money is clustering around artificial intelligence infrastructure. That wave of spending does not only affect global giants; it also shines a spotlight on smaller Australian companies building tools, software and services that plug into the same trend. This article walks through three AI focused small caps worth putting on your watchlist.
These AI small caps in the spotlight are only a sample, and the full screen surfaced 7 more companies with equally compelling narratives that are not covered below. If you want to identify potential front runners early, head straight into the AI Small Caps screener to analyze, filter, and focus on the highest conviction plays.
Pureprofile (ASX:PPL)
Pureprofile is a data and insights group that runs online market research for brands through its own self-service platforms and survey tools. Its AI-enabled Datarubico unit uses machine learning for automated audience insights. The business generates about A$65 million from Data & Insights and carries a market value near A$33 million.
Pureprofile connects with the AI Small Caps theme through Datarubico, an AI-enabled insights engine operating within a broader research business. Investors get exposure to an A$33 million micro-cap focused on audience analytics, where margins and cash generation are influenced by how that single AI platform performs within a still-diversified group.
To see how that AI engine filters through valuation, margins and balance sheet strength, review the 4 key rewards and 1 important warning sign before this micro-cap slips off the radar.

Dicker Data (ASX:DDR)
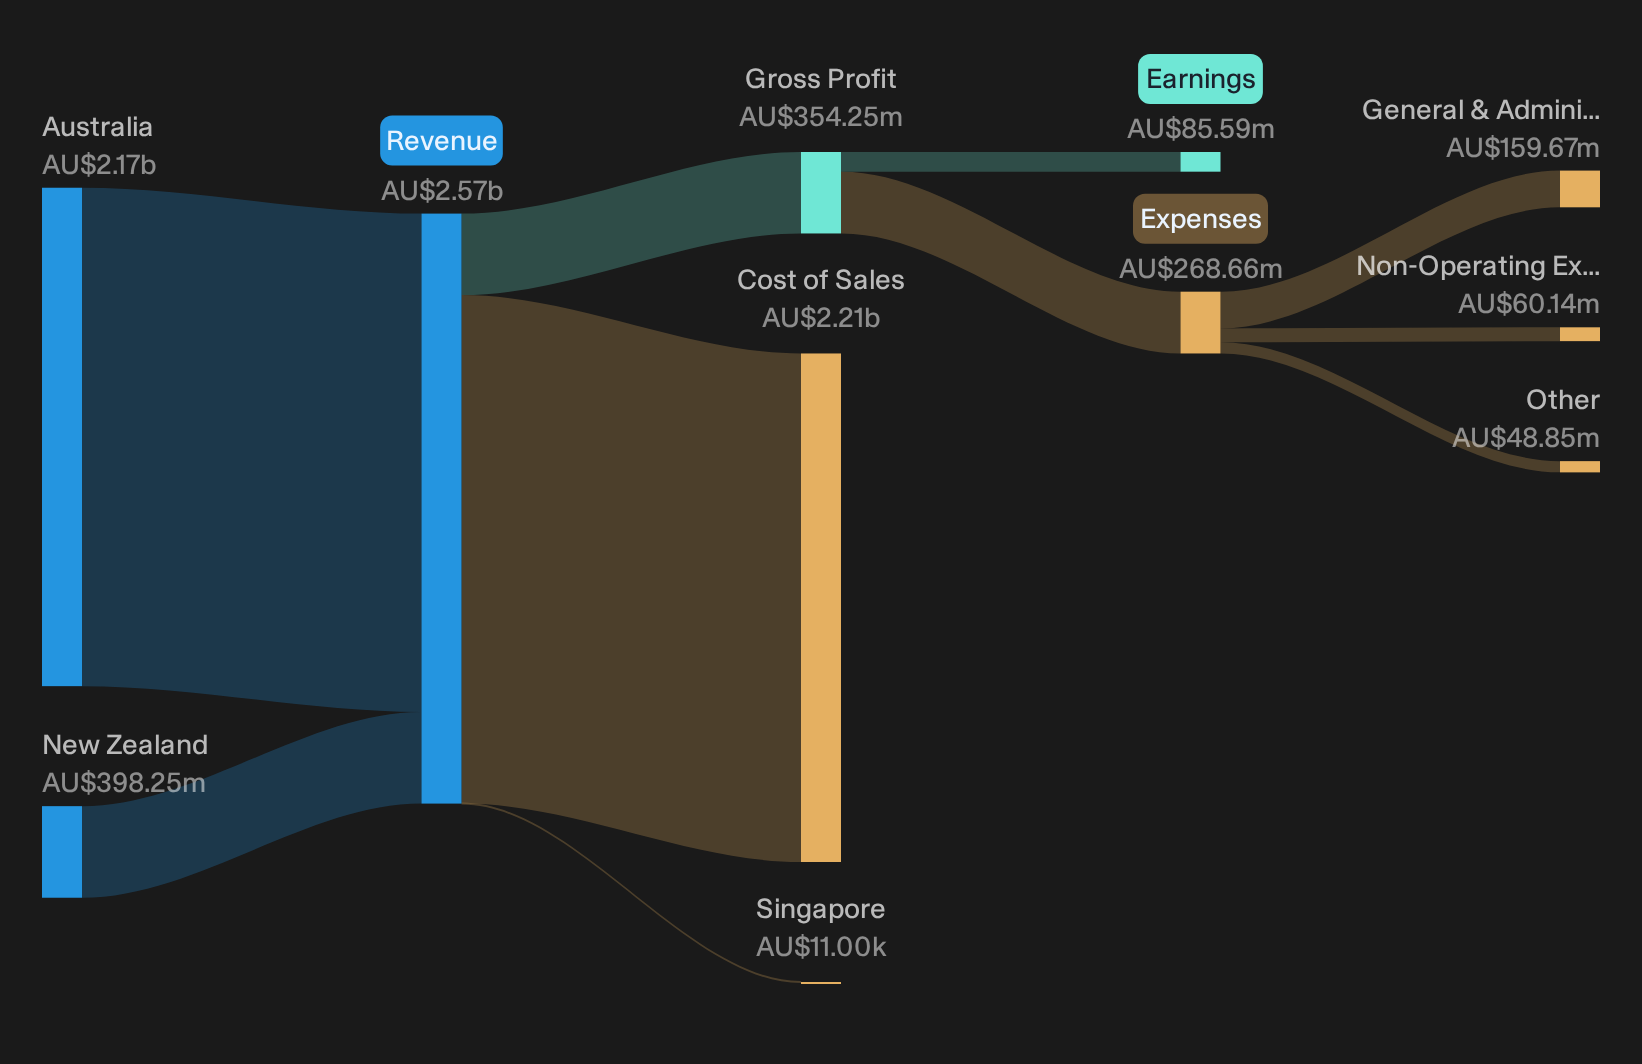
Dicker Data is a wholesale distributor of IT hardware, software, cloud and IoT products, with a key role supplying AI capable gear like Copilot+ PCs, servers and data centre infrastructure. It generated about A$2.57b from wholesale computer peripherals and carries a market value near A$2.72b.
Dicker Data connects the AI Small Caps theme to the practical side of deployment, supplying the servers, Copilot+ PCs and software licenses that let enterprises actually run machine learning workloads rather than just talk about them.
"Expansion into AI infrastructure and solutions, including the delivery of Australia's first AI factory in partnership with Dell and further AI pipeline opportunities, aligns the company with accelerating enterprise digital transformation and creates substantial upside for advanced solutions revenue, especially as AI adoption grows across Australia and New Zealand."
What happens to Dicker Data’s earnings power if a single unseen pressure on AI hardware deal margins shifts in either direction?
If that hidden pressure on Dicker Data’s AI margins interests you, read the full narrative for Dicker Data to see how contract structure and capital intensity could be decoupling.
Data#3 (ASX:DTL)
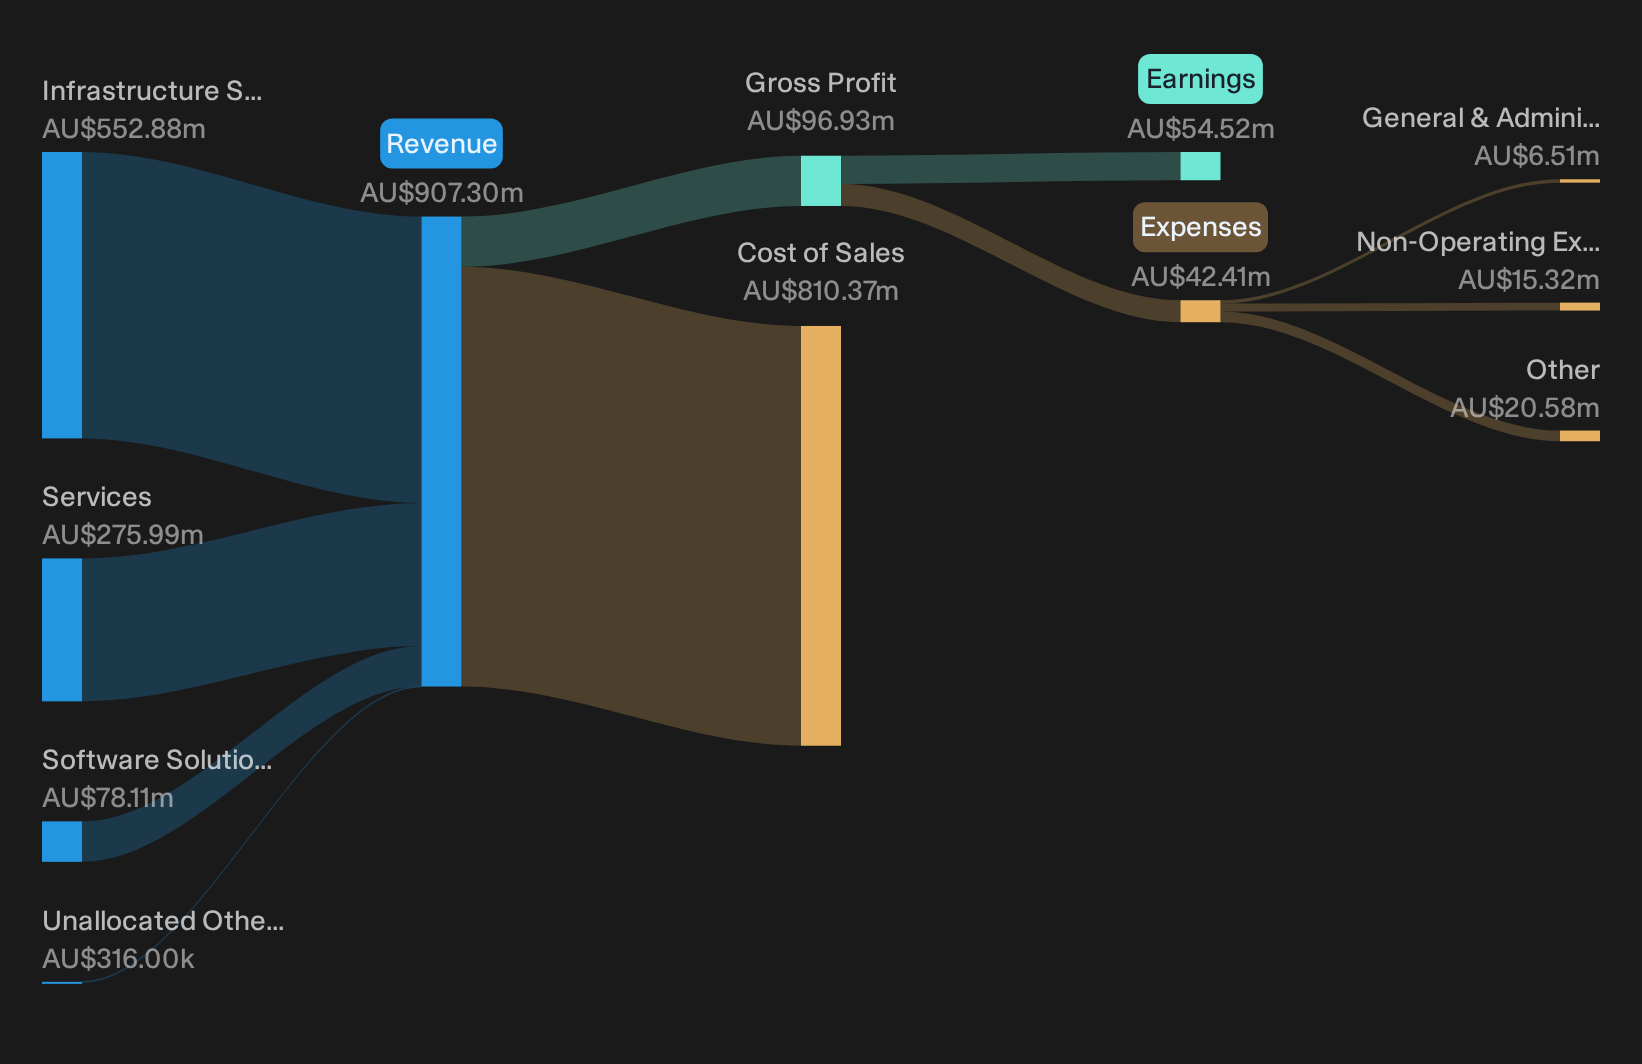
Data#3 is an Australian IT services group that stitches together cloud, security and AI solutions, including Microsoft 365 Copilot and analytics projects, for sectors like healthcare, education and government. It earns about A$553 million from Infrastructure Solutions, A$276 million from Services and A$78 million from Software Solutions on a market value near A$2.1b.
Data#3 plugs into the AI Small Caps theme through its Copilot rollouts and bespoke analytics work, layered on top of a broad IT services engine that already has scale and long relationships with large enterprises.
"The planned increase in staff costs of up to 10% in FY27 to fund growth initiatives could absorb a larger share of that annuity style revenue and limit improvement in operating margins and net profit."
The real test comes if one key assumption about how quickly higher value AI contracts convert into lasting margin expansion proves wrong or right.
If that margin story is what matters to you, the full narrative for Data#3 shows how Data#3’s AI contracts, staff costs and annuity work could still accelerate earnings quality.
Curious About Alternative Stock Paths?
Fresh opportunities can move quickly as sentiment shifts, breakout stories build momentum and under the radar ideas gain attention once they start performing. Scan the next wave and consider your options promptly.
- Identify resilient compounders before they become widely followed by running the list of solid balance sheet and fundamentals (12 results), which filters for durable cash generation while it remains less noticed for now.
- Explore potential yield and price momentum by reviewing the 3 dividend fortresses before income-focused investors respond to these payouts.
- Prepare for possible changes in the resource cycle by scanning the 16 top copper producer stocks while sentiment is still mixed and entry points may be more flexible.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com