


Insiders who bought HK$178.5m worth of E&P Global Holdings Limited's (HKG:1142) stock at an average buy price of HK$0.15 over the last year may be disappointed by the recent 40% decrease in the stock. Insiders buy with the expectation to see their investments rise in value over a period of time. However, recent losses have rendered their above investment worth HK$21.4m which is not ideal.
While we would never suggest that investors should base their decisions solely on what the directors of a company have been doing, logic dictates you should pay some attention to whether insiders are buying or selling shares.
The Last 12 Months Of Insider Transactions At E&P Global Holdings
Over the last year, we can see that the biggest insider purchase was by insider Yang Zhang for HK$179m worth of shares, at about HK$0.15 per share. So it's clear an insider wanted to buy, even at a higher price than the current share price (being HK$0.018). It's very possible they regret the purchase, but it's more likely they are bullish about the company. We always take careful note of the price insiders pay when purchasing shares. Generally speaking, it catches our eye when an insider has purchased shares at above current prices, as it suggests they believed the shares were worth buying, even at a higher price. Yang Zhang was the only individual insider to buy shares in the last twelve months.
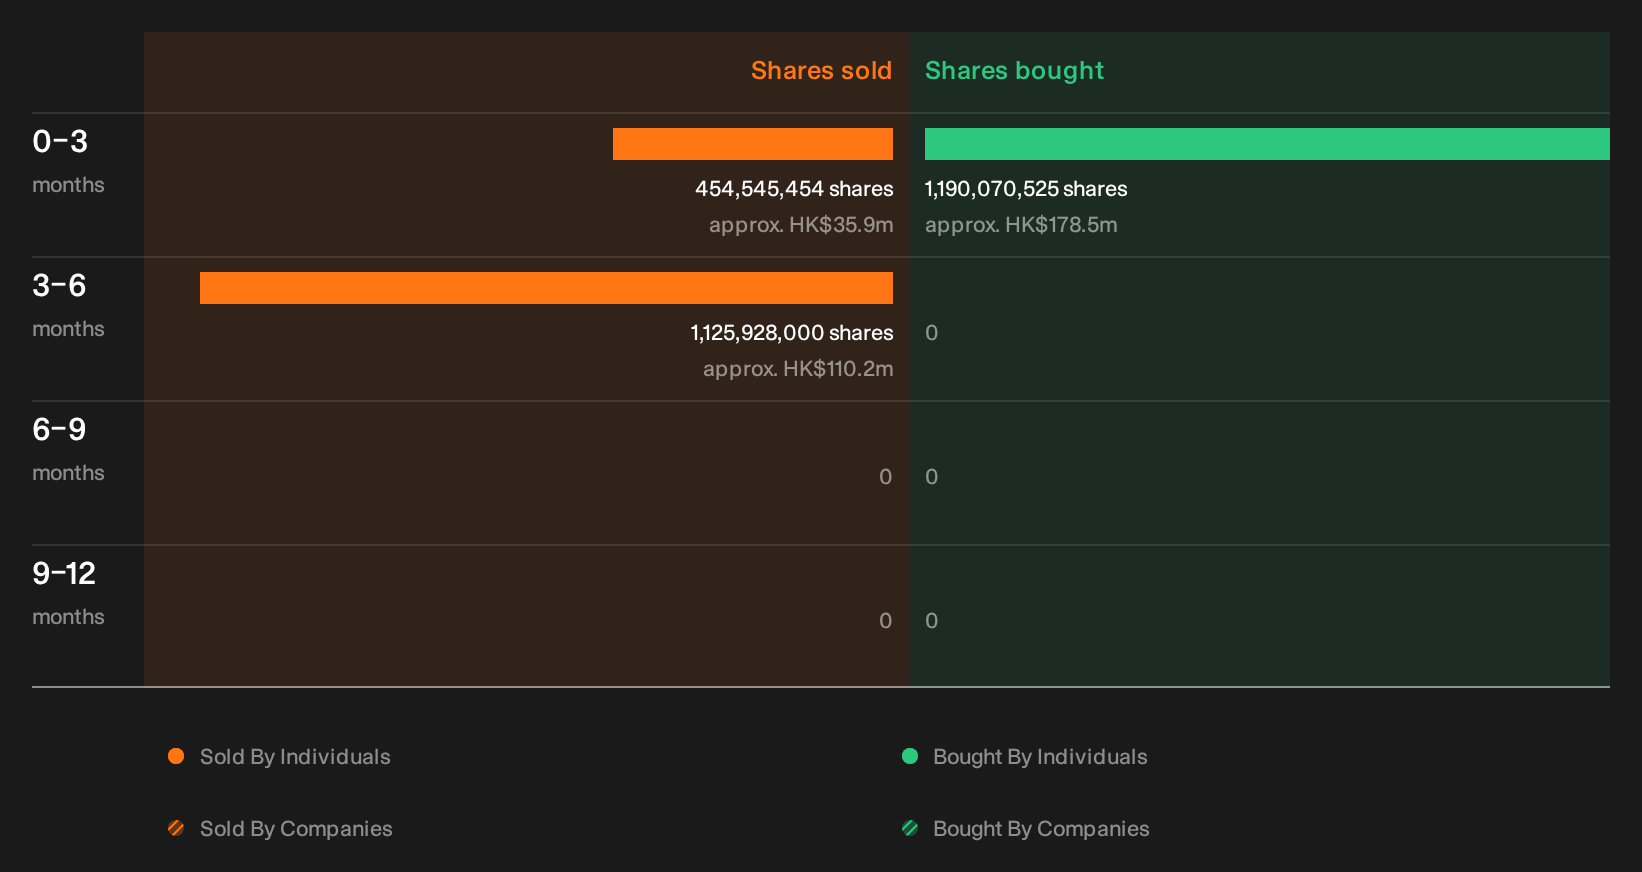
You can see the insider transactions (by companies and individuals) over the last year depicted in the chart below. If you click on the chart, you can see all the individual transactions, including the share price, individual, and the date!
Check out our latest analysis for E&P Global Holdings
E&P Global Holdings is not the only stock that insiders are buying. For those who like to find small cap companies at attractive valuations, this free list of growing companies with recent insider purchasing, could be just the ticket.
E&P Global Holdings Insiders Bought Stock Recently
There has been significantly more insider buying, than selling, at E&P Global Holdings, over the last three months. In total, insider Yang Zhang bought HK$179m worth of shares in that time. But insider Yang Zhang sold shares worth HK$36m. We think insiders may be optimistic about the future, since insiders have been net buyers of shares.
Insider Ownership Of E&P Global Holdings
Another way to test the alignment between the leaders of a company and other shareholders is to look at how many shares they own. Usually, the higher the insider ownership, the more likely it is that insiders will be incentivised to build the company for the long term. E&P Global Holdings insiders own 69% of the company, currently worth about HK$177m based on the recent share price. Most shareholders would be happy to see this sort of insider ownership, since it suggests that management incentives are well aligned with other shareholders.
So What Do The E&P Global Holdings Insider Transactions Indicate?
It's certainly positive to see the recent insider purchase. And an analysis of the transactions over the last year also gives us confidence. But on the other hand, the company made a loss during the last year, which makes us a little cautious. When combined with notable insider ownership, these factors suggest E&P Global Holdings insiders are well aligned, and quite possibly think the share price is too low. One for the watchlist, at least! So while it's helpful to know what insiders are doing in terms of buying or selling, it's also helpful to know the risks that a particular company is facing. When we did our research, we found 4 warning signs for E&P Global Holdings (3 can't be ignored!) that we believe deserve your full attention.
Of course E&P Global Holdings may not be the best stock to buy. So you may wish to see this free collection of high quality companies.
For the purposes of this article, insiders are those individuals who report their transactions to the relevant regulatory body. We currently account for open market transactions and private dispositions of direct interests only, but not derivative transactions or indirect interests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.