


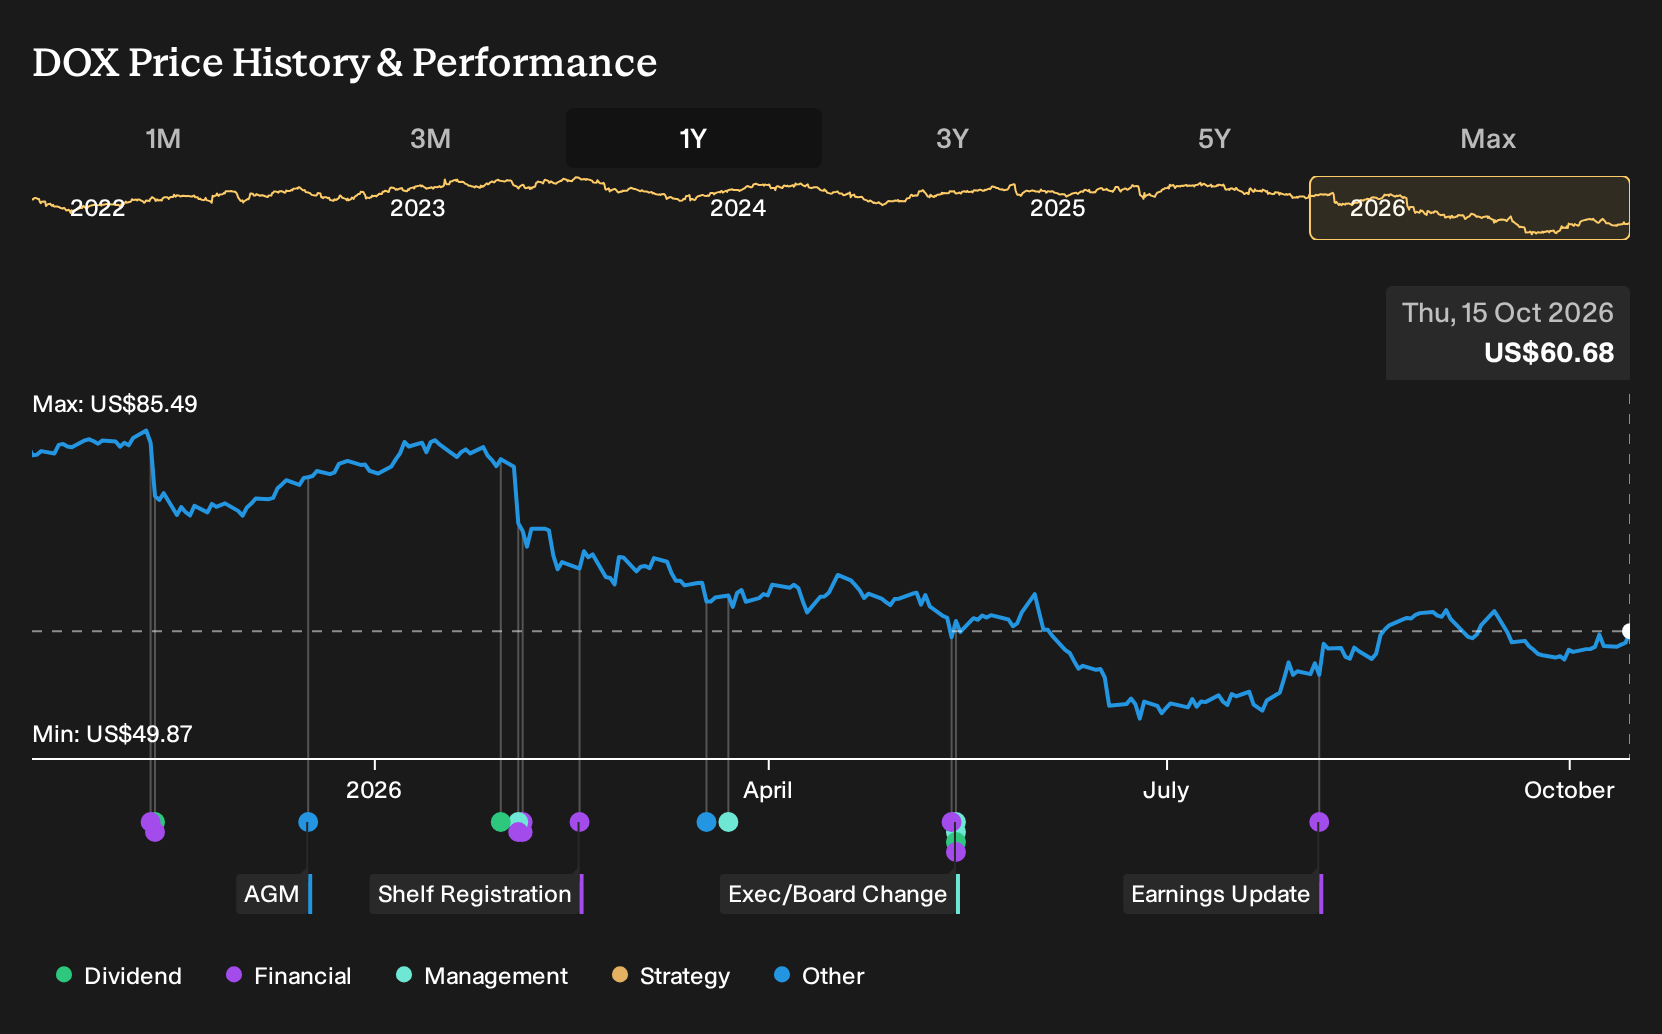
- Amdocs has shifted its focus toward its aOS and AI-led software platform after signing a new 10 year VEON contract and selling Vubiquity, tightening attention on recurring telecom software and services.
- This refocus concentrates capital and management effort on higher visibility software earnings and long contracts, which can reshape how investors judge Amdocs' earnings durability and risk profile.
- We will now explore how Amdocs' renewed AI platform focus, highlighted by the VEON deal, could reshape its broader investment narrative.
Scan beyond Amdocs and explore other potential rebound stories in telecom and AI platforms with our hand picked 32 high quality undervalued stocks.
Amdocs Investment Narrative Recap
A shareholder in Amdocs needs to believe that telecom and media customers keep leaning on its aOS and GenAI software to modernize billing, customer experience and networks, and that its long contracts translate into steady earnings. The recent slide in the share price puts more attention on whether those recurring projects actually turn into cleaner, less lumpy profit over time.
The key short term swing factor is how quickly aOS and AI deployments move from pilots to wider rollout with existing clients, especially as telecom IT budgets look cautious. The main risk is that guidance or new bookings do not keep pace with these expectations, which would keep pressure on both the business momentum and investor confidence.
The 10 year VEON agreement is the clearest recent proof point for that thesis. It ties Amdocs deeper into a large operator’s BSS and AI roadmap and gives the software platform a long window to show it can handle complex, real world workloads rather than just small trials.
For you as an investor, the VEON deal matters because it echoes prior aOS wins and adds to a roughly US$4.28b 12 month backlog, while Amdocs refocuses around telecom software and managed services after selling Vubiquity. Execution risk remains, since slower IT spending or weaker AI traction at key accounts could blunt the benefit of these long dated contracts.
Amdocs' analyst narrative points to revenues of US$5.2b and earnings of US$945.9m by 2029, built on an assumed 3.6% yearly revenue growth rate and an earnings increase of about US$490m from current earnings of US$455.7m.
Uncover why Amdocs' fair value points to a 31% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternative lens is AI execution risk. Some of the most optimistic Amdocs analysts were modeling revenue of about US$5.2b and earnings of roughly US$842.2m by 2029, assuming broad GenAI adoption. Those forecasts came before the VEON contract and Telco Days 2026, so readers should expect these views to evolve and should compare several angles independently.
Explore 5 other Amdocs fair value estimates, including one that suggests as much as 116% potential upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Amdocs research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amdocs. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amdocs' overall financial health at a glance.
Looking For More Investment Ideas Beyond Amdocs?
Once you have a view on Amdocs, it can help to compare that thesis against a broader watchlist of companies with different risk and income profiles. The Simply Wall St Screener lets you filter by fundamentals, balance sheet strength, or dividend profile so you can build a list that actually fits your own approach.
- If you want potential upside combined with fundamentals, start with a focused set of undervalued opportunities in the 32 high quality undervalued stocks.
- For income focused portfolios that prioritize cash returns, scan through the 8 dividend fortresses and see which businesses line up with your yield and payout preferences.
- If capital preservation sits high on your checklist, build a shortlist from the 32 resilient stocks with low risk scores and compare their risk profiles with what you see in Amdocs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com