


- Lowe's Companies updated its fiscal 2026 outlook with projected sales of US$92b and adjusted EPS of US$12.25, while also extending Black Friday and holiday promotions that now run from late October through Christmas Eve with added loyalty perks.
- The combination of a more conservative sales forecast and heavier reliance on extended discount periods highlights how Lowe's is balancing margin discipline with efforts to support demand in a competitive home improvement market.
- We will now look at how Lowe's refreshed sales guidance and longer Black Friday calendar could influence the broader investment narrative.
Scan how Lowe's Companies compares with other retailers leaning on promotions and loyalty economics by reviewing the 32 high quality undervalued stocks that currently combine solid cash flows with balance sheet strength.
Lowe's Companies Investment Narrative Recap
To own Lowe's Companies, you need to believe the retailer can turn its large US home improvement footprint and Pro focus into steadier earnings power even with flattish housing turnover. The updated fiscal 2026 outlook of about US$92b in sales and US$12.25 in adjusted EPS points to management running the business with tight cost control and cautious expectations.
The most important near term swing factor is how effectively Lowe's executes on Pro growth, digital tools and productivity programs while promotions run longer and deeper. The key risk remains margin pressure, especially with higher leverage and negative shareholders equity, if discounting and commercial mix weigh more heavily than planned.
The extended Black Friday and holiday calendar is the announcement that ties closest to this setup. Deals starting October 29 and running through Christmas Eve, plus loyalty perks such as early access and free same day delivery, push more traffic into a longer peak season and lean on digital and fulfillment capabilities that Lowe's has been building.
For catalysts, this elongated promotional window intersects directly with management's focus on omnichannel performance and Pro engagement. Execution quality around inventory, logistics and service will influence how well the business converts that demand into profitable volume, which matters given guidance now sits at the lower end of prior operating margin and EPS ranges.
Lowe's Companies' current analyst narrative points to revenues of US$99.5b and earnings of US$7.8b by 2029, based on revenue growing about 3.2% a year and earnings rising by roughly US$1.2b from about US$6.6b today to the 2029 consensus level.
Uncover why Lowe's Companies' fair value indicates a 29% potential upside to its current price, a gap that could close sooner than many expect.
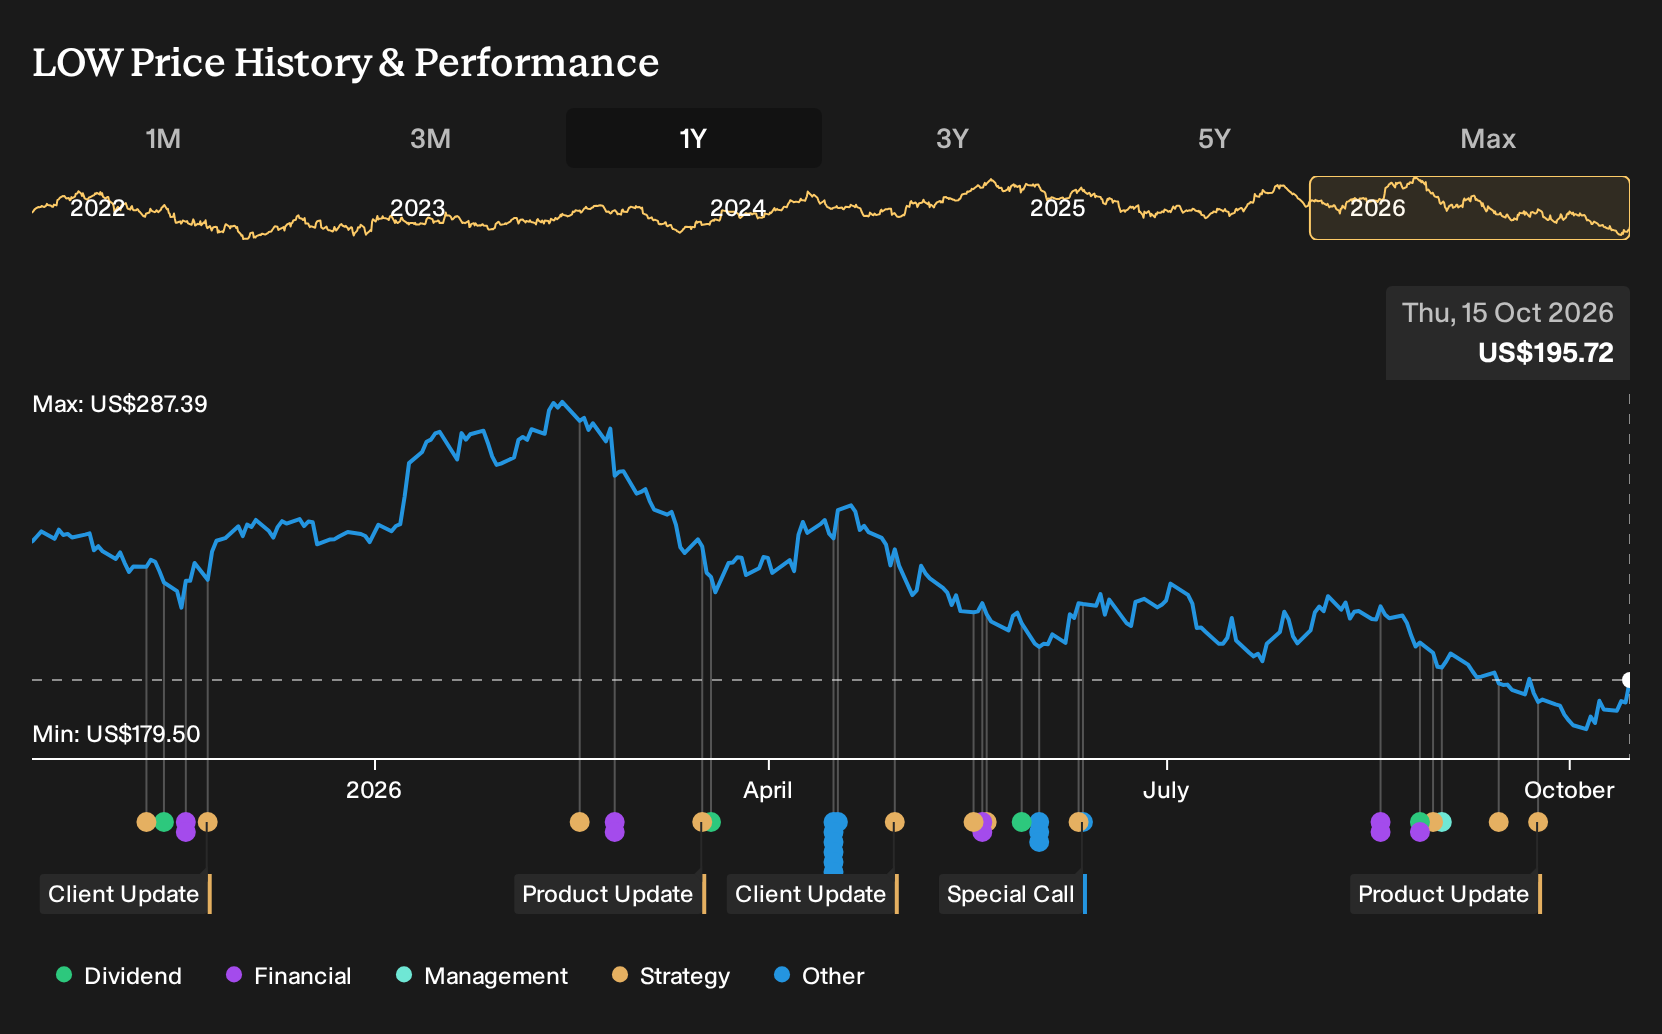
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between about US$231 and US$252 a share, with the widest gap near US$22. Private investors are weighing Lowe's Companies' dividend record and Pro focus against risks from elevated leverage and acquisition integration, so treat these as starting points and compare several contrasting opinions.
Explore 2 other Lowe's Companies fair value estimates, including one that suggests potential upside of up to 29% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lowe's Companies research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lowe's Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lowe's Companies' overall financial health at a glance.
Looking For More Ideas Beyond Lowe's Companies?
If you want to test your thesis on Lowe's Companies against other opportunities, the Simply Wall St Screener can help you line up similar profiles and spot very different setups side by side.
- For investors who care about valuation support and balance sheet quality, scan a curated 32 high quality undervalued stocks that share a blend of dependable cash flows and financial resilience.
- If income is your priority, check out companies screened as potential yield candidates through the 8 dividend fortresses that may align with a long term dividend focus.
- For a focus on resilience first, filter for defensively positioned names in the 32 resilient stocks with low risk scores that aim to keep overall risk scores in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com