


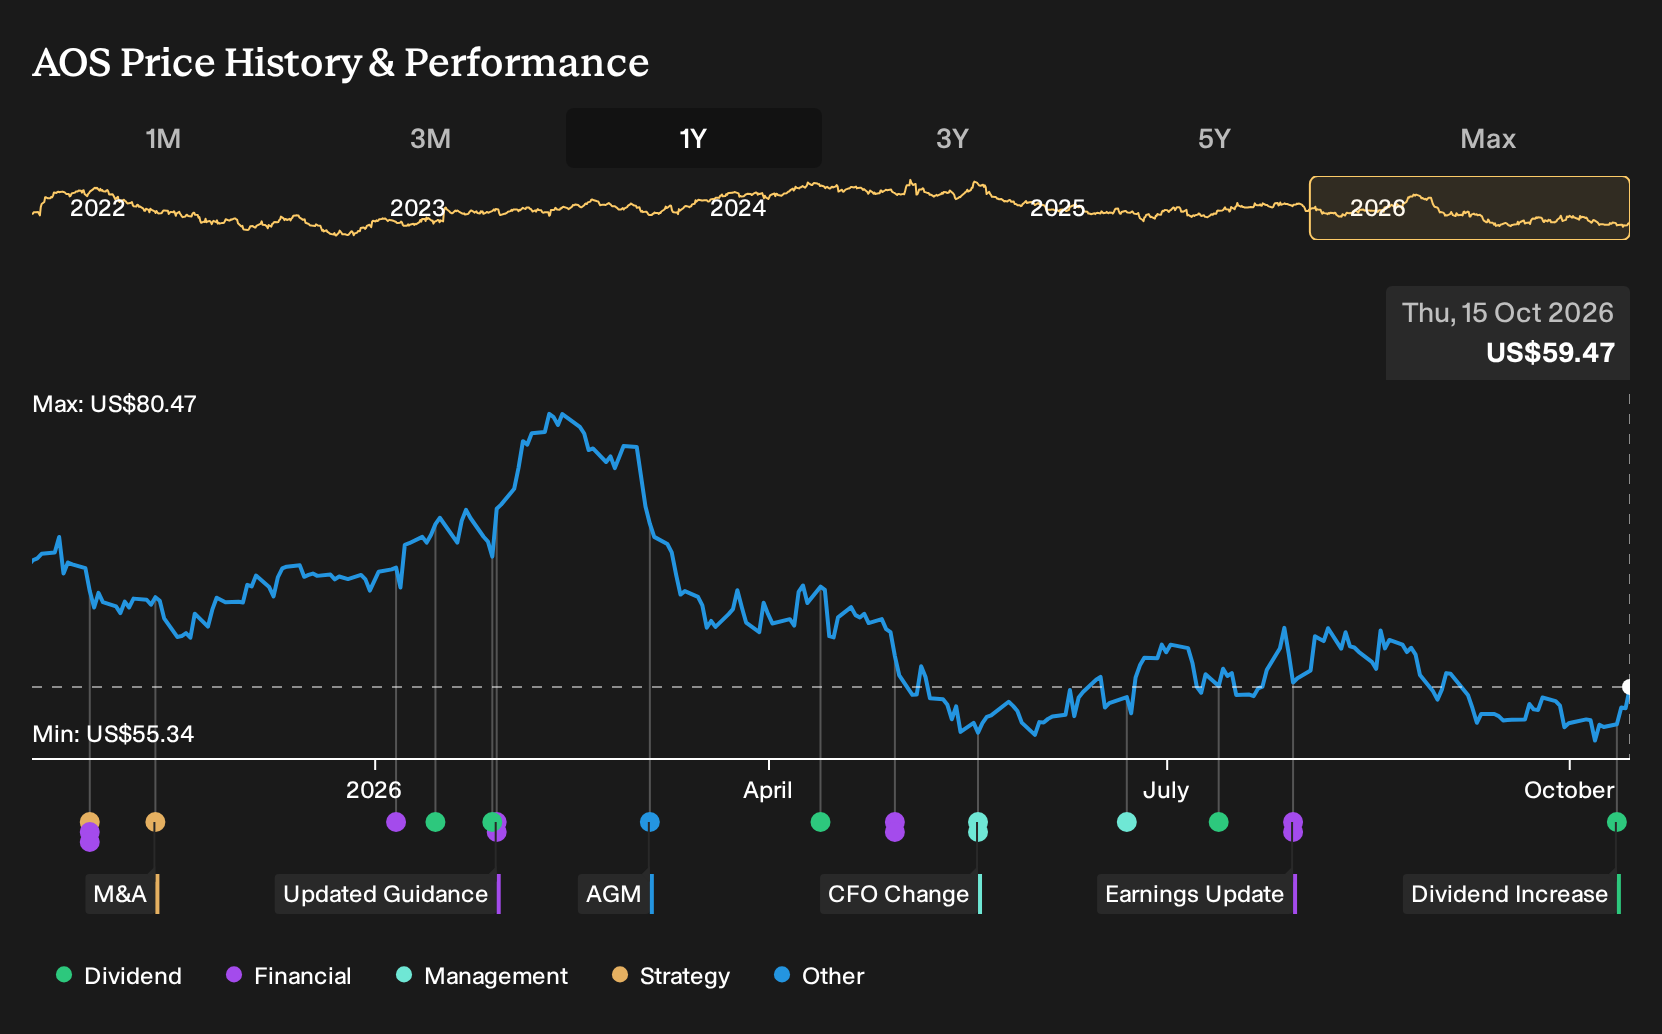
- A. O. Smith recently approved a 6% increase in its quarterly cash dividend to $0.38 per share on both Common and Class A Common Stock. It will be payable on November 16, 2026 to shareholders of record on October 30, 2026.
- This higher dividend commitment reflects that A. O. Smith is continuing to return cash to investors while it invests in water management, energy efficient heating and digital products amid ongoing cost and demand pressures.
- We will now look at how A. O. Smith's higher quarterly dividend could influence the investment narrative for this water technology business.
Scan how A. O. Smith's higher dividend stacks up against other income-focused opportunities by comparing it with 8 dividend fortresses in today's market.
A. O. Smith Investment Narrative Recap
A. O. Smith appeals to shareholders who believe efficient water heating and treatment can compound value over time as the product mix tilts toward higher efficiency, connected systems and water management platforms. The higher dividend signals management confidence in cash generation but does not change the near term swing factor, which remains execution on product mix, pricing and productivity while end markets are uneven.
The biggest near term risk still sits in softer North America residential heaters, combined with already weak China demand and higher steel and input costs. If those pressures deepen or pricing and cost programs underperform, net margins and free cash flow could stay tight, which would matter more to the thesis than this dividend move.
The dividend decision sits alongside earlier commentary about using free cash flow to fund water management and higher efficiency products, while still returning cash through dividends and buybacks. With first half 2026 free cash flow at US$233 million and debt at about 25% of total capital, A. O. Smith has room to keep that balance between reinvestment and payouts if operations stay on track.
For catalysts, the key link is that a higher regular dividend relies on the same drivers analysts focus on, namely premium product mix, digital and IoT capable heaters and ongoing channel realignment that targets US$6 million to US$8 million of annual savings from 2027. If those projects hit their operational targets, they could support both the higher dividend and any future capital returns, subject to how China, North America demand and raw material costs develop.
A. O. Smith's narrative projects US$4.3b revenue and US$605.5 million earnings by 2029. This implies 4.2% yearly revenue growth and an earnings increase of about US$105 million from US$500.3 million today.
Uncover why A. O. Smith's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into A. O. Smith’s push into high efficiency heaters and water treatment. They were already modeling revenue reaching about US$4.4b and earnings of roughly US$646.3 million by 2029. You can now ask how this dividend increase might reshape those upbeat assumptions.
Explore 4 other A. O. Smith fair value estimates, including one that suggests there may be as much as 44% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your A. O. Smith research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for A. O. Smith. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate A. O. Smith's overall financial health at a glance.
Looking For More Investment Ideas Beyond A. O. Smith?
If A. O. Smith has sharpened your focus on quality, income and balance sheet strength, broaden that watchlist by scanning a wider set of opportunities that share similar traits but play in different corners of the market.
- For income seekers who want yield with an eye on durability, review a curated set of payout opportunities through the 8 dividend fortresses.
- If value is your priority and you prefer solid fundamentals at a reasonable entry point, sort candidates using the 33 high quality undervalued stocks.
- When capital preservation matters as much as upside potential, narrow your search to resilient businesses with healthier finances through the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com