


- Fortuna Mining reported fresh drilling results from the Southern Arc and Kassasoko deposits at Diamba Sud in Senegal and began a 51,000 meter exploration campaign at Kabewest on the nearby Bambadji properties, with multiple holes intersecting high grade gold over meaningful widths and mineralization remaining open in several directions.
- The combination of open mineralized zones, the Kabewest drilling ramp up, and an expected initial Inferred Mineral Resource estimate in early 2027 directly affects how investors think about Fortuna Mining’s future reserve base and potential production pipeline.
- The focus now turns to how Fortuna Mining’s investment narrative is influenced by these Diamba Sud and Bambadji drilling advances.
Fortuna Mining Investment Narrative Recap
To own Fortuna Mining, you need to believe that higher quality ounces from Séguéla and Diamba Sud can offset the loss of San Jose and Yaramoko while bringing all in sustaining costs under better control. The fresh Diamba Sud and Kabewest drill results mainly reinforce that long term resource story rather than changing the near term picture.
For the next year or so, the key swing factor remains execution at the existing mines and cost discipline, with 2026 guidance of 281,000 to 305,000 GEO framing expectations. The biggest risk is still concentration in a smaller group of assets in challenging jurisdictions, combined with elevated capital spend and exposure to permitting or project delays.
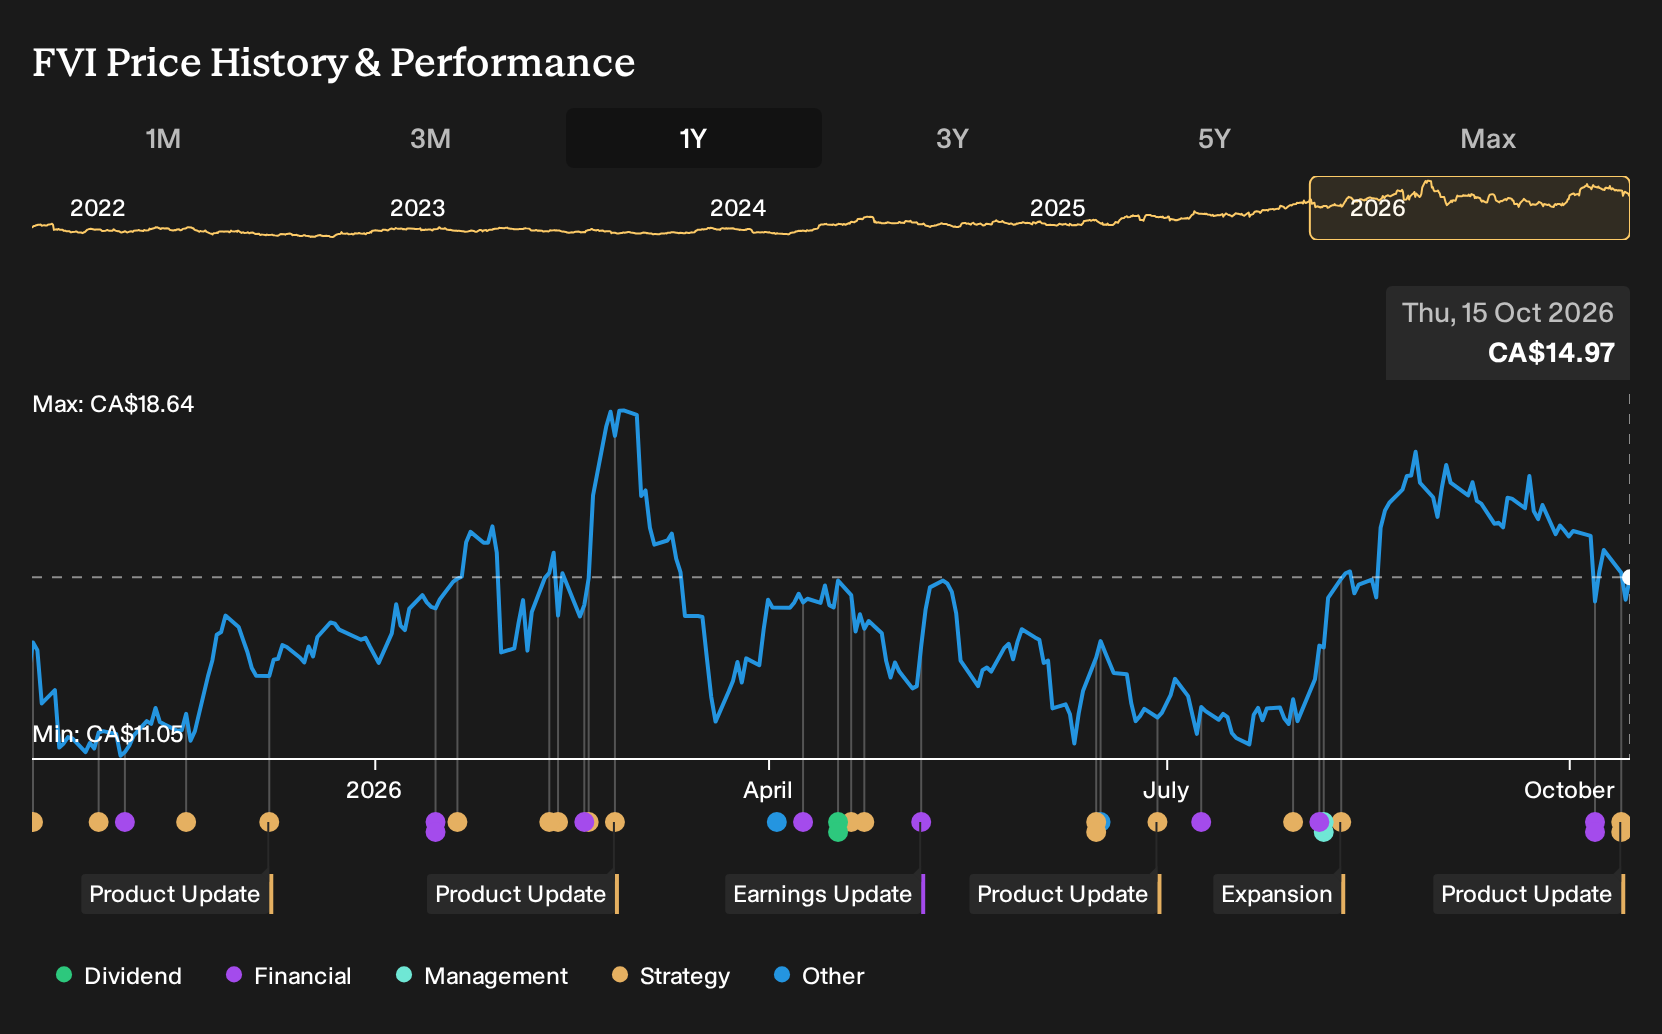
The October 7 production and guidance update is the announcement that really anchors this Diamba Sud news. Q3 output of 69,665 GEO and 214,754 GEO for the first nine months sets a clear operational base, while reiterated 2026 guidance indicates that management is not using exploration headlines to distract from current performance.
Against that backdrop, the Southern Arc, Kassasoko, and Kabewest drill campaigns look like an early pipeline feeding into the 2027 Diamba Sud and Bambadji resource update. The operational question for investors is whether Fortuna Mining can keep hitting its production and cost targets while funding this work without stretching the balance sheet or slipping on project execution.
Fortuna Mining's current earnings of $378.2 million are forecast to reach $771.8 million by 2029, implying roughly a 2x earnings increase. This outlook sits alongside analyst expectations for 24.1% yearly revenue growth and projected 2029 revenue of $2.3b.
Discover why Fortuna Mining's fair value indicates a 30% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts exploration execution risk front and center. The most pessimistic analysts already assumed Fortuna Mining would reach about $2.4b in revenue and $817.6 million in earnings by 2029, yet still applied a lower 5.5x P/E. That more cautious stance could shift again once these Diamba Sud and Kabewest drill results are fully reflected in models, so consider this an active debate and review several viewpoints before deciding where you stand.
Explore 4 other Fortuna Mining fair value estimates, including one that suggests it could be worth just CA$19.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fortuna Mining research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fortuna Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fortuna Mining's overall financial health at a glance.
Looking For More Ideas Beyond Fortuna Mining?
If the Fortuna Mining story has sharpened your thinking on risk, reward, and balance sheet strength, it can help to line it up against a wider field of potential opportunities using the Simply Wall St Screener.
- For investors who want quality first and a margin of safety second, scan through 6 high quality undervalued stocks that pair stronger fundamentals with what the market may be pricing too cautiously.
- If capital preservation matters as much as upside, focus on steadier businesses through a 8 resilient stocks with low risk scores that filters for sturdier financial profiles and lower risk scores.
- When you are hunting for less crowded opportunities, widen your search to a 10 high quality undiscovered gems that filters for solid fundamentals where investor attention still looks limited.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com