


- Mitsui Fudosan and The Ascott Limited previously agreed that Ascott will manage Oakwood Premier YAESU CORE Tokyo, a hotel and serviced residence scheduled to open in 2029 within the YAESU CORE mixed use project in front of Tokyo Station.
- The property will be the fifth collaboration between Ascott and Mitsui Fudosan in Japan, signaling the continued execution of Mitsui Fudosan’s mixed use development approach anchored by international hospitality operators.
- We will now examine how Mitsui Fudosan’s investment narrative could be shaped by Ascott’s role in the YAESU CORE Tokyo project.
Scan how Mitsui Fudosan fits into Japan's property and infrastructure story by comparing it with a curated list of solid balance sheet and fundamentals (21 results) that is also positioned for long-term real asset themes.
Mitsui Fudosan Investment Narrative Recap
An investor in Mitsui Fudosan needs to be comfortable with a long build out of premium mixed use projects and a balance sheet carrying sizeable interest bearing debt of ¥4,632.5b that is projected to rise to ¥4.8t. The Ascott partnership around YAESU CORE Tokyo fits that story but does not change the near term picture. In the short term, focus still sits on office leasing resilience, domestic housing pricing power, and fee income from the Management segment.
The bigger risk right now is that higher interest costs, weaker overseas assets, or thinner gains on property disposals weigh on net profit and earnings per share. Debt is not well covered by operating cash flow, and profit margins already sit below last year. In contrast, earnings are forecast to grow 8.6% per year with help from existing projects and capital recycling, not from this single hotel agreement.
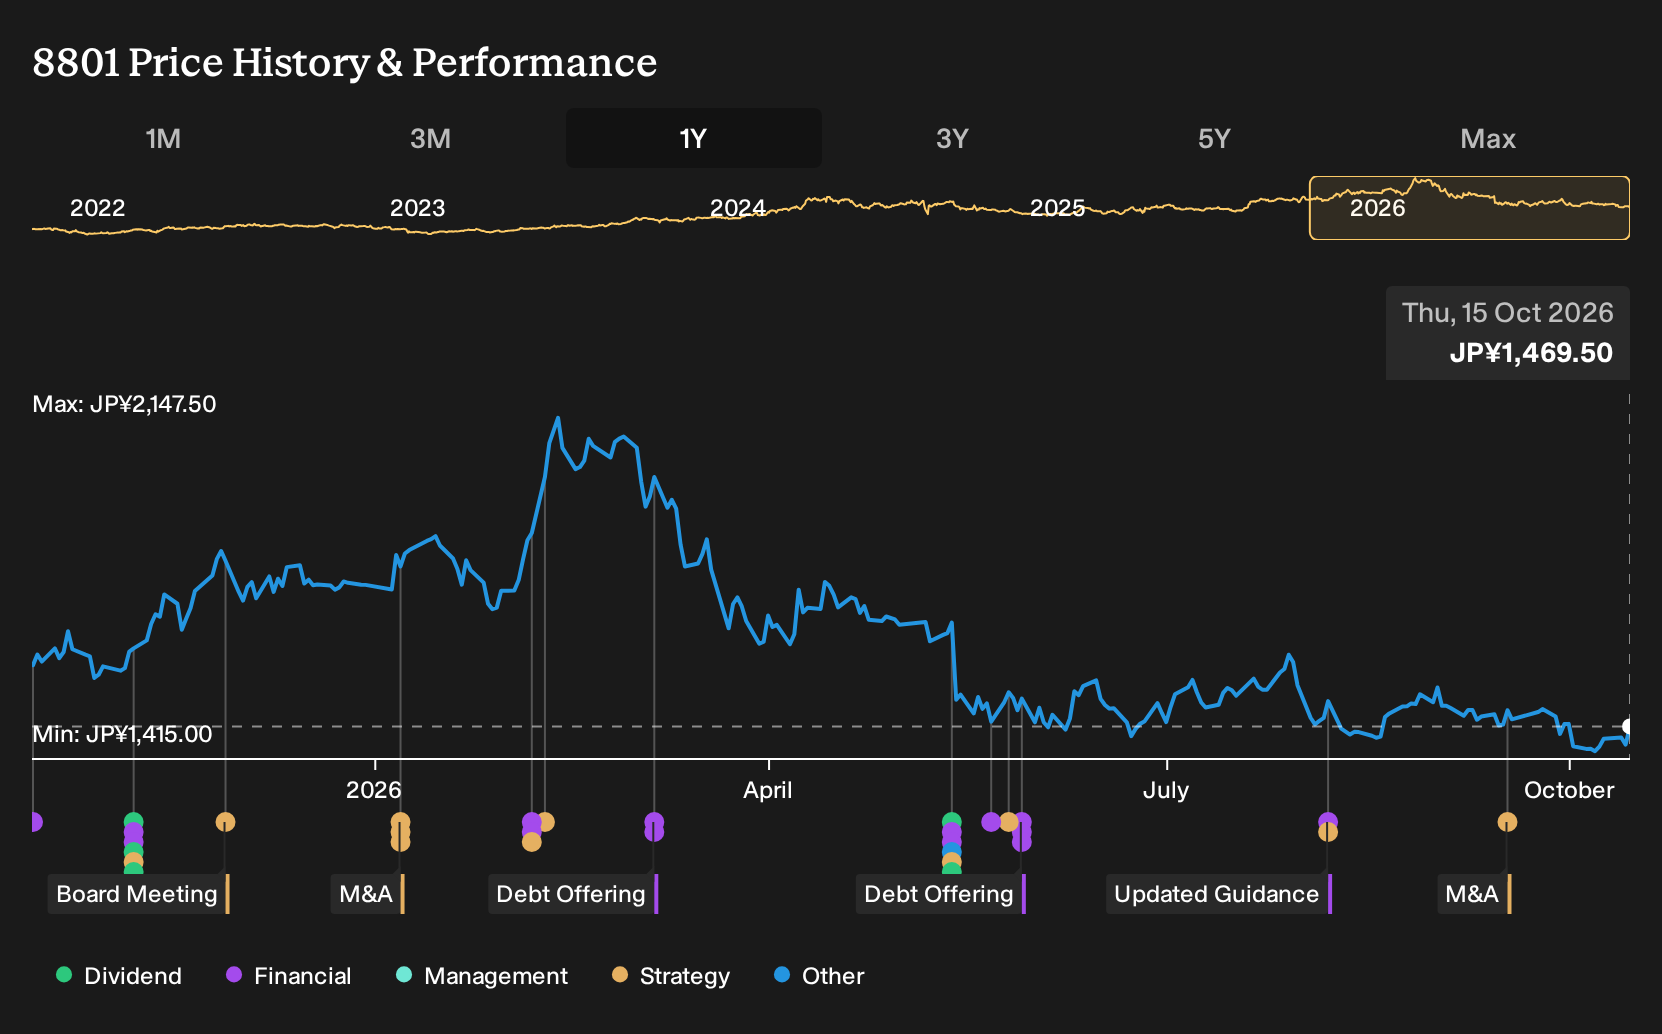
In the context of this Ascott deal, the most relevant backdrop is Mitsui Fudosan’s plan to keep recycling capital out of assets with large unrealized gains, which currently total ¥3,985.1b on rental properties. Management has already cut strategic equity holdings by more than 40%. Gains from disposals and investment securities have been supporting recent profit, even as one off items and overseas headwinds complicate the picture.
For you, the link is simple. YAESU CORE Tokyo looks like another asset that could either feed recurring rental and fee income into the Leasing and Facility Operations segments, or eventually be recycled if conditions suit. The key execution questions remain the same. Can recurring income grow enough to rely less on property sales gains, while servicing higher borrowings and maintaining shareholder returns through dividends and a ¥40b buyback program?
Mitsui Fudosan’s current analyst narrative points to revenues of ¥3,027.5b and earnings of ¥331.2b by 2029, built on 6.2% yearly revenue growth and an earnings increase of about ¥100.9b from earnings today of ¥230.3b.
Discover why Mitsui Fudosan's fair value indicates a 40% potential upside to its current price, which could be realized far more quickly than the build out of YAESU CORE Tokyo.
Exploring Other Perspectives
You might read the YAESU CORE Tokyo news as a test of the bearish view that Mitsui Fudosan leans too hard on asset sales. The most cautious analysts were already working with slower revenue expectations of ¥2,825.5b and earnings of ¥316.7b by 2029. Their stance is more conservative than consensus, and fresh hotel agreements like this could eventually push that story in a different direction.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Mitsui Fudosan research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Mitsui Fudosan. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mitsui Fudosan's overall financial health at a glance.
Looking for more Mitsui Fudosan investment ideas?
If the Mitsui Fudosan story has you thinking about how to position your wider portfolio, it can help to scan other opportunities with resilient balance sheets, income potential, or mispriced quality. The Simply Wall St Screener lets you line up candidates side by side so you can judge which ones actually fit your risk tolerance and time horizon.
- If you want to put stability first, start with a 21 resilient stocks with low risk scores and see which businesses line up best with your comfort level.
- For investors hunting for quality at a fair price, compare Mitsui Fudosan with a curated 15 high quality undervalued stocks that combines fundamentals with valuation checks.
- Income focused readers can round out their watchlists by scanning a 32 dividend fortresses that targets higher yielding payouts with robust underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com