


G7 finance leaders are now preparing joint war games for AI driven cyber attacks. That kind of focus on digital risk puts Canadian technology companies back under the spotlight. When governments and banks worry about AI security, software, semiconductor and hardware providers linked to that world can attract fresh attention. This article walks through three Canadian tech stocks that currently screen as undervalued based on publicly available valuation metrics.
These three stocks are only a starting sample, since the wider screen flags 13 more undervalued tech companies with equally grounded stories that are not covered here.
If you want to quickly identify and analyze the broader opportunity set, head straight to the Undervalued Tech screener.
Lightspeed Commerce (TSX:LSPD)
Overview: Lightspeed Commerce provides a cloud-based commerce platform that helps retailers and restaurants run omni-channel sales, manage operations, and process payments.
Operations: The business generates about $1.24b in revenue primarily from Software & Programming, reflecting its focus on subscription tools and payments.
Market Cap: CA$1.90b
Lightspeed Commerce matters for the Undervalued Tech theme because its subscription software and payments engine sit at the centre of how smaller retailers and hospitality operators digitize sales, operations, and data. However, the stock still trades as if that model carries far more risk than potential reward.
"Although Lightspeed Commerce is targeting higher payments penetration with transaction revenue and Lightspeed Capital, the recent hardware gross margin turning negative due to heavy discounting and freight costs risks offsetting those gains."
What happens to earnings power depends heavily on how one less-visible pressure affects the balance between higher-margin software and lower-margin transactions.
That mix can either compress or accelerate earnings leverage for Lightspeed Commerce, and the full narrative for Lightspeed Commerce unpacks how software, payments, and hardware are really pulling against each other.

Celestica (TSX:CLS)
Overview: Celestica builds and manages complex hardware platforms and supply chains for hyperscalers and other technology and industrial customers, including AI focused data center infrastructure.
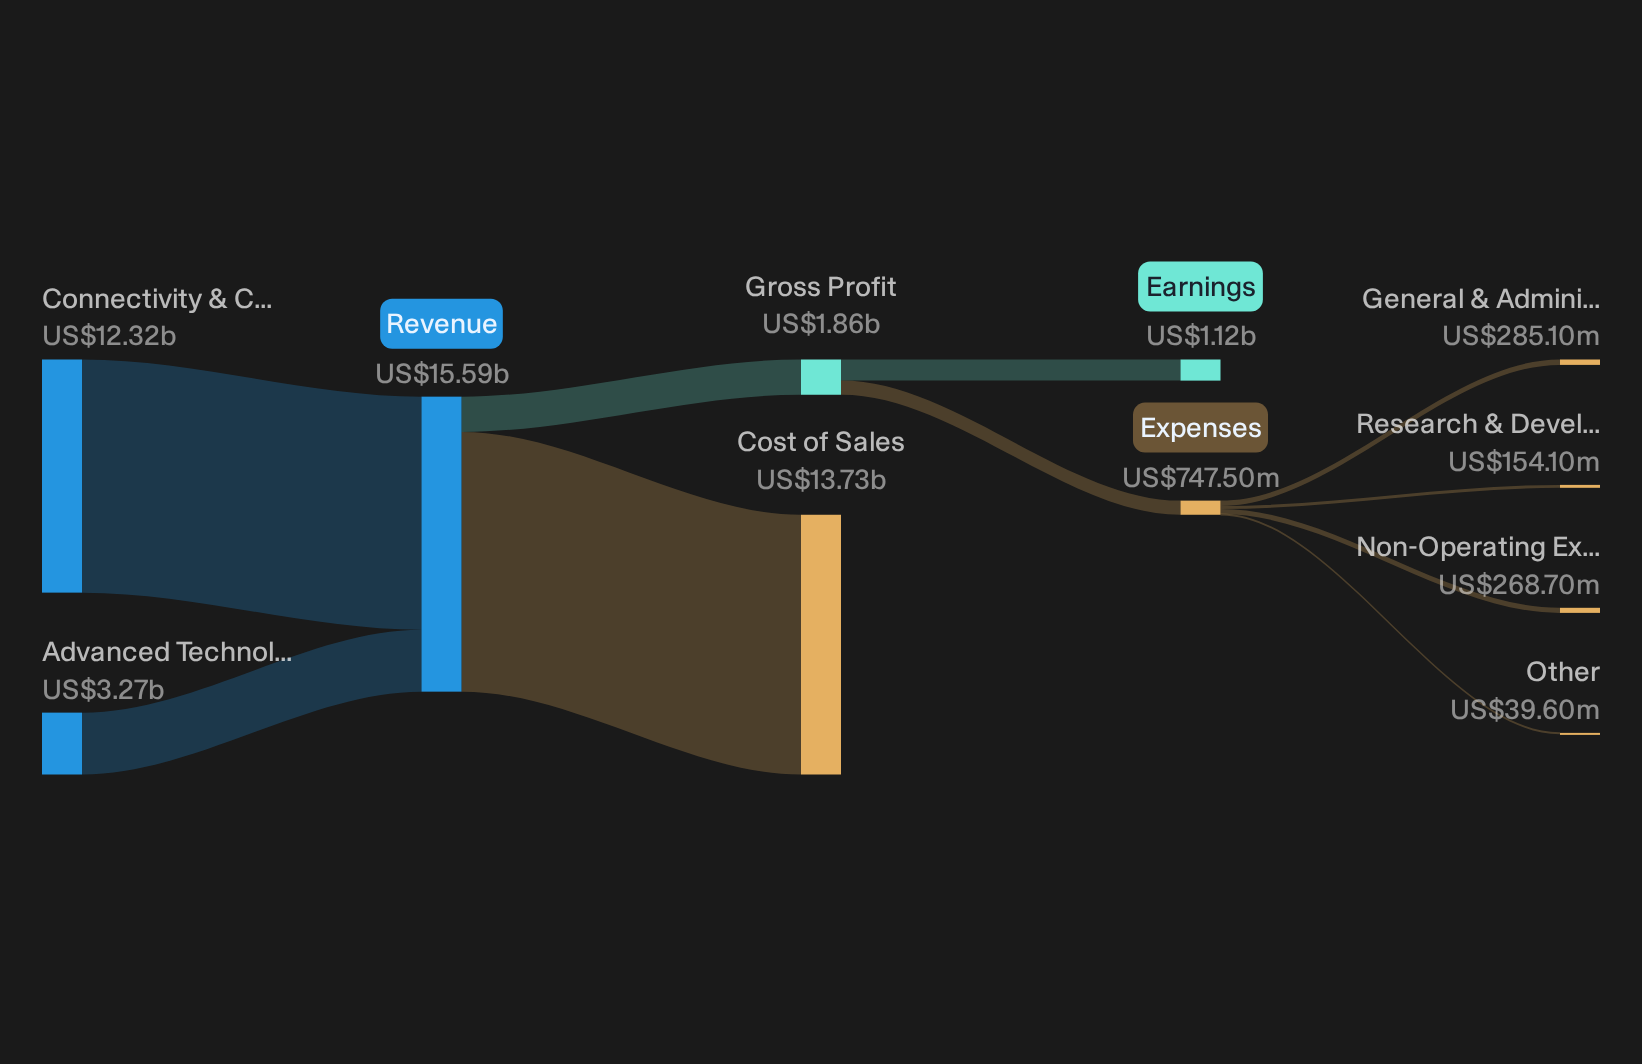
Operations: Celestica generates about US$3.27b from Advanced Technology Solutions and US$12.32b from Connectivity & Cloud Solutions, with CCS as its largest contributor.
Market Cap: CA$53.02b
Celestica matters for the Undervalued Tech theme because its hardware platforms, AI oriented rack systems, and cloud infrastructure services plug directly into how hyperscalers scale compute capacity.
"Accelerated demand for advanced networking and AI infrastructure by hyperscaler customers is driving rapid growth in Celestica's CCS segment, with multiple new 800G and upcoming 1.6T program ramps, supporting robust revenue expansion and greater operating leverage over the next 12 to 24 months."
The real swing factor is how one concentrated pocket of demand ultimately filters through to long term pricing power and margin stability.
That pricing question is exactly what the full narrative for Celestica unpacks, separating short term AI rack demand from longer term earnings power and potential cyclicality risk.
CGI (TSX:GIB.A)
Overview: CGI provides end to end IT and business process services, with a strong focus on cloud migration, AI automation, and application modernization for public and private sector clients worldwide.
Operations: CGI generates around CA$21.4b in revenue, led by Western and Southern Europe at CA$3.0b and U.S. Commercial and State Government at CA$2.5b.
Market Cap: CA$21.1b
CGI matters for the Undervalued Tech theme because its cloud, AI, and modernization work turns complex IT overhauls into long term service relationships.
"The ongoing acceleration in digital transformation initiatives, particularly in cloud migration, AI-driven automation and data analytics, continues to boost client demand for CGI's managed services and proprietary IP across both public and private sectors."
What investors really need to watch is how one subtle shift in contract mix ultimately feeds through to margins and long term cash generation.
That contract shift is exactly what the full narrative for CGI lays out in detail, showing how accelerating AI and cloud work could reshape CGI's long term earnings profile.

Seeking Alternatives Before The Crowd?
Fresh opportunities move fast. Breakout momentum, dropping mispricings, and under the radar stories rarely stay quiet for long. Scan the next wave of ideas before the window closes.
- Target income-oriented opportunities by running the 3 dividend fortresses to help identify high-yield candidates that may have overlooked payouts and balance sheets.
- Explore early-stage potential with the 18 elite penny stocks with strong financials and look for smaller companies that combine higher risk with more disciplined financial profiles.
- Follow AI-related activity with the 94 AI infrastructure stocks and focus on infrastructure and tools supporting compute demand instead of headline-driven narratives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com