


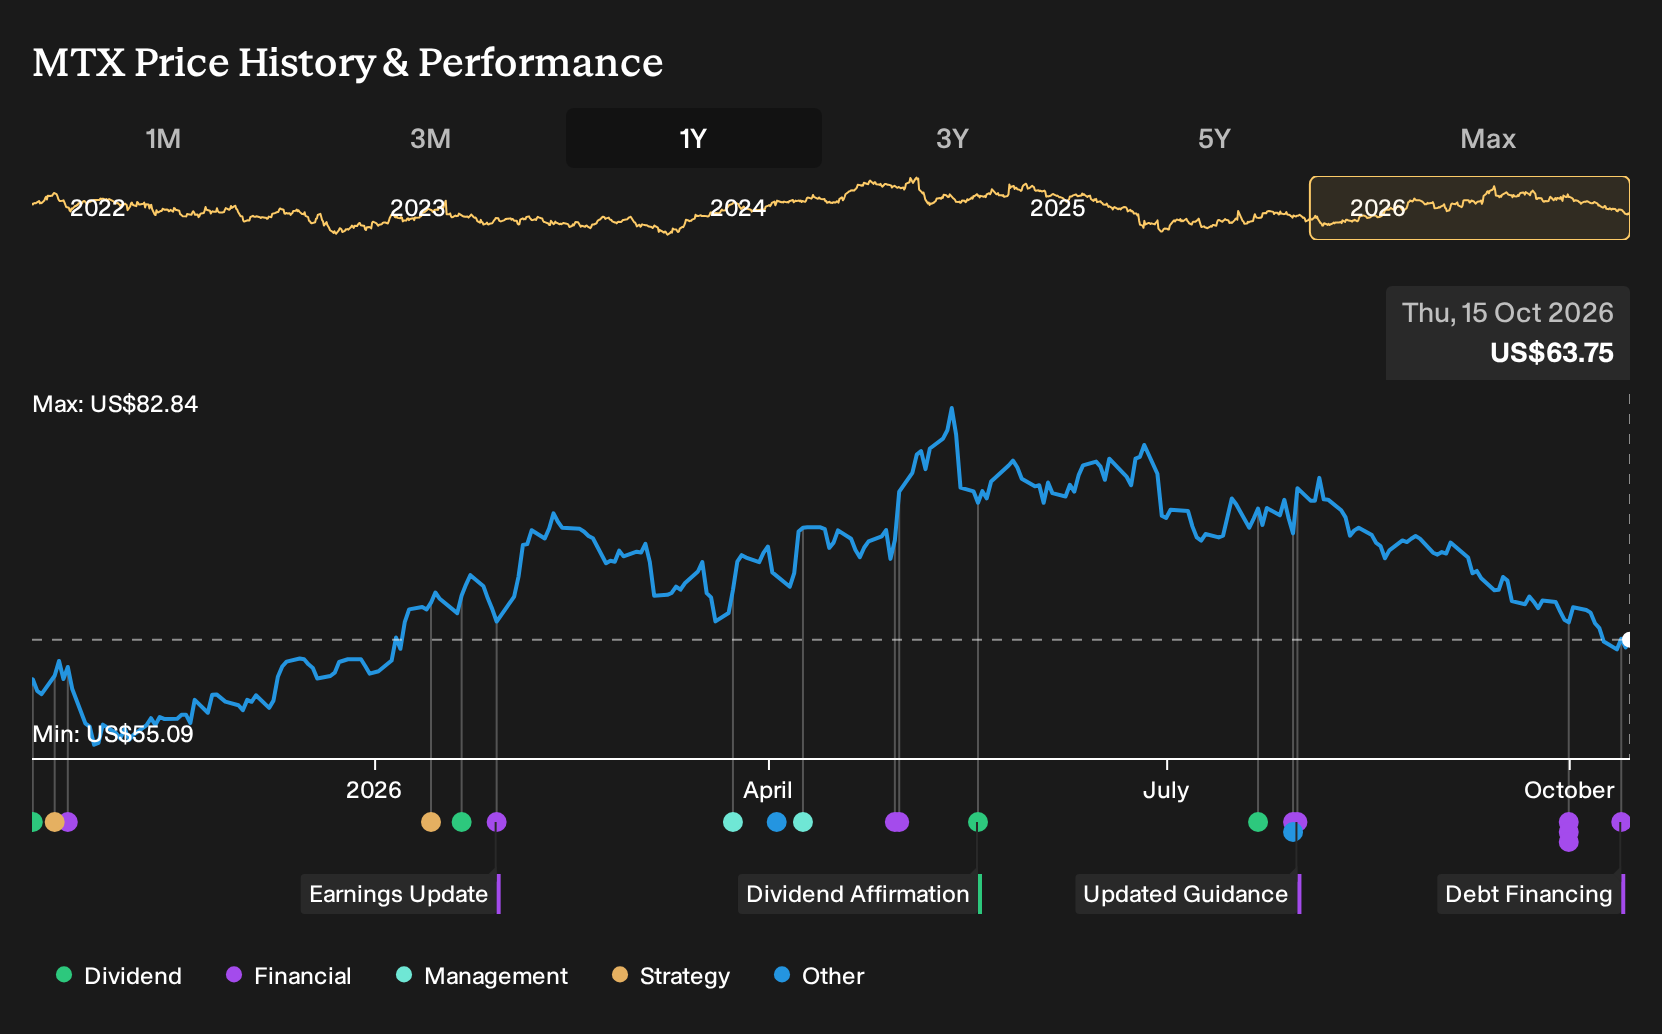
- Minerals Technologies recently issued US$400,000,000 of 7.500% senior notes due 2032 and put in place a new US$500,000,000 revolving credit facility maturing in 2031. The company used the bond proceeds and cash to redeem its 5.000% senior notes due 2028 and cover related fees.
- The refinancing shifts Minerals Technologies' funding mix toward longer dated, higher coupon debt. This can influence future interest expense and the financial flexibility available to support its specialty minerals, sustainability, and critical minerals projects.
- Attention now turns to how Minerals Technologies' investment narrative around specialty minerals and sustainability aligns with this higher coupon 7.500% bond refinancing.
Minerals Technologies Investment Narrative Recap
To own Minerals Technologies, you need to believe the shift toward specialty minerals, sustainability linked products, PFAS remediation and critical minerals can gradually matter more than mature paper related volumes and current losses. The refinancing itself mostly changes how that effort is funded. The higher 7.500% coupon can lift interest costs, but the longer maturities help planning and give management time to push projects toward scale.
In the near term, the key swing factor is still execution on that US$1.4b innovation and sustainability pipeline, especially in areas like PFAS solutions and renewable fuel purification. The biggest risk remains pressure on margins from energy costs, pricing lags and talc related legal exposure, which the new debt structure does not directly resolve.
The most relevant piece of recent news for this debt move is the refinancing facility agreement and incremental amendment to Minerals Technologies' long running credit agreement. The business replaced a US$400m secured revolver with a US$500m facility maturing in 2031, while leaving the existing term loan maturity in 2031 untouched and on the same terms.
For you as a shareholder, the practical question is how this extra committed liquidity and longer revolving tenor interact with the project slate. A larger revolver can support working capital swings as PFAS, sustainability and critical minerals projects scale up. However, it also sits on top of a balance sheet already funded entirely by higher risk borrowing, so disciplined use and consistent cash generation remain central to the Minerals Technologies investment case.
Minerals Technologies' analyst narrative points to forecast revenue of US$2.4b and projected earnings of US$600.8 million by 2029, built on expected yearly revenue growth of 4.3%, with that profit figure representing an earnings increase of about US$668 million from earnings today of a US$67.2 million loss.
Uncover why Minerals Technologies' fair value indicates a 43% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span a wide band, from US$60 up to about US$192 per share, so retail views on Minerals Technologies are far from aligned. You are weighing those optimistic forecasts against risks like ongoing talc legal exposure and energy cost pressure, which can reshape how this refinancing feeds through to future resilience.
Explore 3 other Minerals Technologies fair value estimates, including one that suggests up to 6% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Minerals Technologies research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Minerals Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Minerals Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Minerals Technologies?
Once you have formed a view on Minerals Technologies, it can help to compare that thesis against other opportunities with different balance sheet profiles, income potential, and risk levels using the Simply Wall St Screener.
- For investors who care most about resilience and lower financial risk, start by scanning a 32 resilient stocks with low risk scores that keeps a close eye on balance sheet strength and consistency.
- If you want income to play a bigger role in your portfolio, focus on opportunities offering meaningful yields and stable cash flows through a curated 8 dividend fortresses.
- When the goal is to find mispriced quality, cast a wider net across a 33 high quality undervalued stocks that filters for financial robustness combined with attractive valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com