


Latin American exporters sit at a crossroads as the IMF warns on rising public debt, softer growth forecasts and less friendly global tailwinds. That mix can reshape how markets treat commodity producers tied to metals, energy and agriculture, and it can reward investors who separate resilient exporters from more fragile stories. This article breaks down three stocks from the screener that appear relatively better positioned in light of this IMF backdrop.
The companies highlighted below are just a sample from this idea, and the full screen surfaced 10 more Latin American exporters with equally detailed stories that are not covered in this article. To go deeper, head straight into the Latin American Export-Oriented Commodity Producers screener to identify, filter and analyze the higher conviction commodity plays that best fit your own approach.
Vale (BOVESPA:VALE3)
Overview: Vale is a Brazilian mining group that supplies iron ore, nickel and other metals globally, tightly linked to export driven commodity demand.
Operations: Vale generates about R$167b from Iron Ore Solutions and R$51b from Basic Metals Valley, with China its single largest export market.
Market Cap: R$282.7b
For this Latin American exporter screen, Vale matters because its iron ore and nickel flows depend far more on global appetite for steel and batteries than on Brazil’s fiscal backdrop.
"The ramp-up of key copper and nickel expansion projects like Bacaba (in New Carajás), Voisey's Bay, and Onça Puma is materially increasing Vale's exposure to fast-growing demand from electric vehicles and renewable energy, positioning the company to benefit from global efforts to decarbonize. This should support medium-to-long-term revenue and EBITDA growth."
What really shapes Vale’s potential is how one emerging pressure on future iron ore profitability interacts with that growing base metals platform.
That tension between future iron ore pricing and a bigger base metals engine is exactly what the full narrative for Vale unpacks, including how Vale’s mix could be quietly decoupling risk.

Cresud Sociedad Anónima Comercial Inmobiliaria Financiera y Agropecuaria (BASE:CRES)
Overview: Cresud Sociedad Anónima Comercial Inmobiliaria Financiera y Agropecuaria runs a broad Latin American agribusiness, producing exportable grains, sugarcane, oilseeds and cattle.
Operations: Cresud generates ARS 508,571 million from agricultural and livestock production plus ARS 368,822 million from Argentine shopping malls, with most revenue booked in Argentina and Brazil.
Market Cap: ARS 1.27t
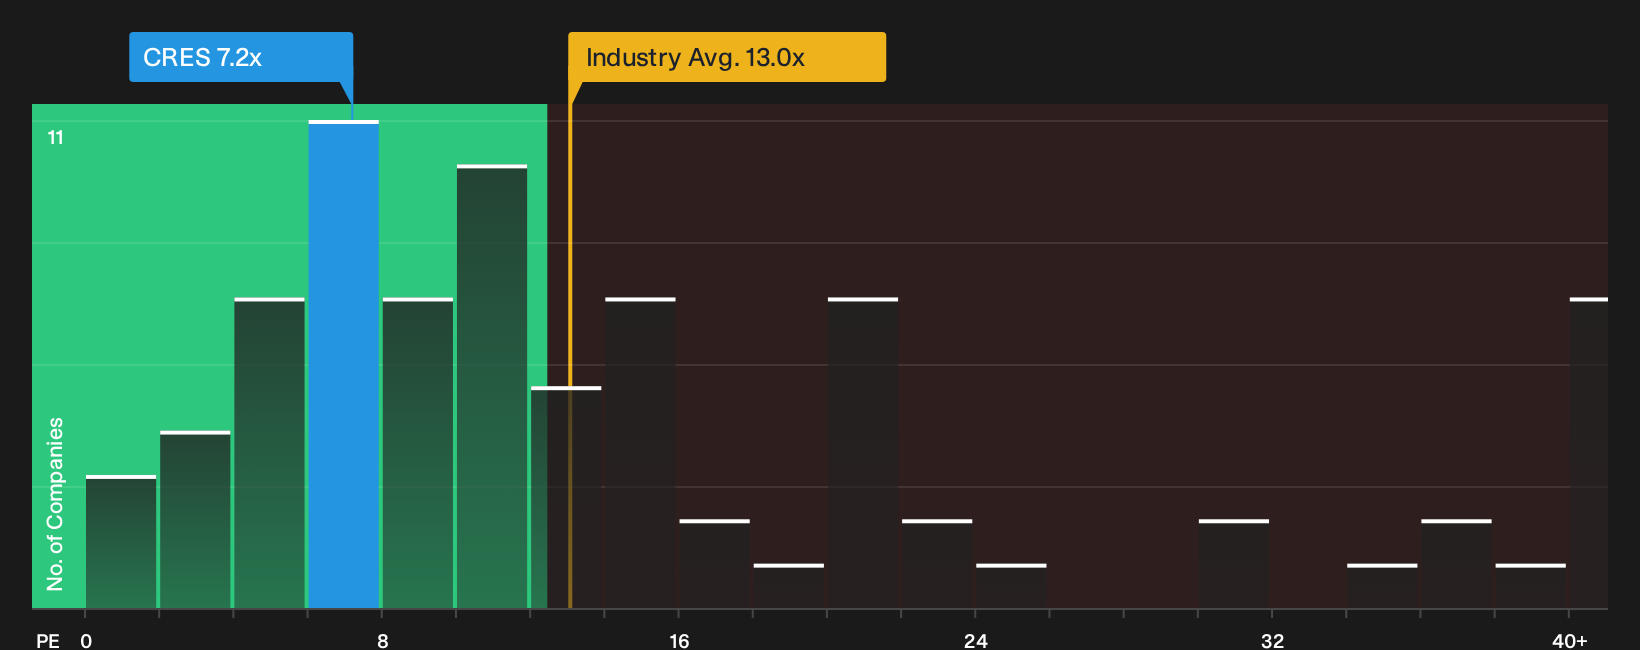
Cresud provides direct exposure to Latin American agricultural commodities at a time when sales of ARS 1,379,363 million and a 12.9% net margin indicate meaningful scale in export-linked farming. A P/E of 7.2x and 5.79% yield indicate value; however, the heavy use of external debt and recent insider selling mean a great deal depends on how pressure on future cash generation is resolved.
That cash flow question hangs over Cresud Sociedad Anónima Comercial Inmobiliaria Financiera y Agropecuaria, so tap into the 3 key rewards and 4 important warning signs to see what might tip the balance.
Prio (BOVESPA:PRIO3)
Overview: Prio is a Brazilian offshore oil and gas producer focused on developing and operating crude fields that supply export driven global energy demand.
Operations: Prio generates R$21.4b from oil and gas exploration and production, with revenue currently reported entirely from foreign markets.
Market Cap: R$54.6b
Prio matters for this exporter screen because it converts Brazilian offshore reservoirs into barrels priced off global crude benchmarks. As a result, shifts in worldwide demand and IMF flagged macro tailwinds feed directly into its realized economics.
"Ramp-up of production at the Wahoo field is now contributing roughly 40,000 barrels per day from four producing wells, and management expects this to help lift Prio’s consolidated output above 200,000 barrels per day by the end of 2026."
The real swing factor is how one unseen pressure on unit costs and balance sheet leverage shapes the sustainability of those export backed margins.
That cost pressure is the real hinge, so read the full narrative for Prio to see how Prio’s expansion, leverage and export pricing could be quietly decoupling from headline macro risks.

Curious About Your Next Investing Alternatives
Fresh ideas move fast. Some themes build quiet momentum, then break out before most investors notice. Scan these under the radar for now, and consider them as part of your early research.
- Target reliable income streams by reviewing the 219 dividend fortresses that focuses on companies aiming to pair hefty yields with balance sheets built to handle rough patches.
- Track structural demand for metals through the 16 top copper producer stocks and identify producers positioned around long-term infrastructure and electrification trends while the crowd is still looking elsewhere.
- Explore potential capital rotation into cleaner baseload energy with the 16 nuclear energy infrastructure stocks and find infrastructure plays that could benefit if nuclear spending accelerates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com