


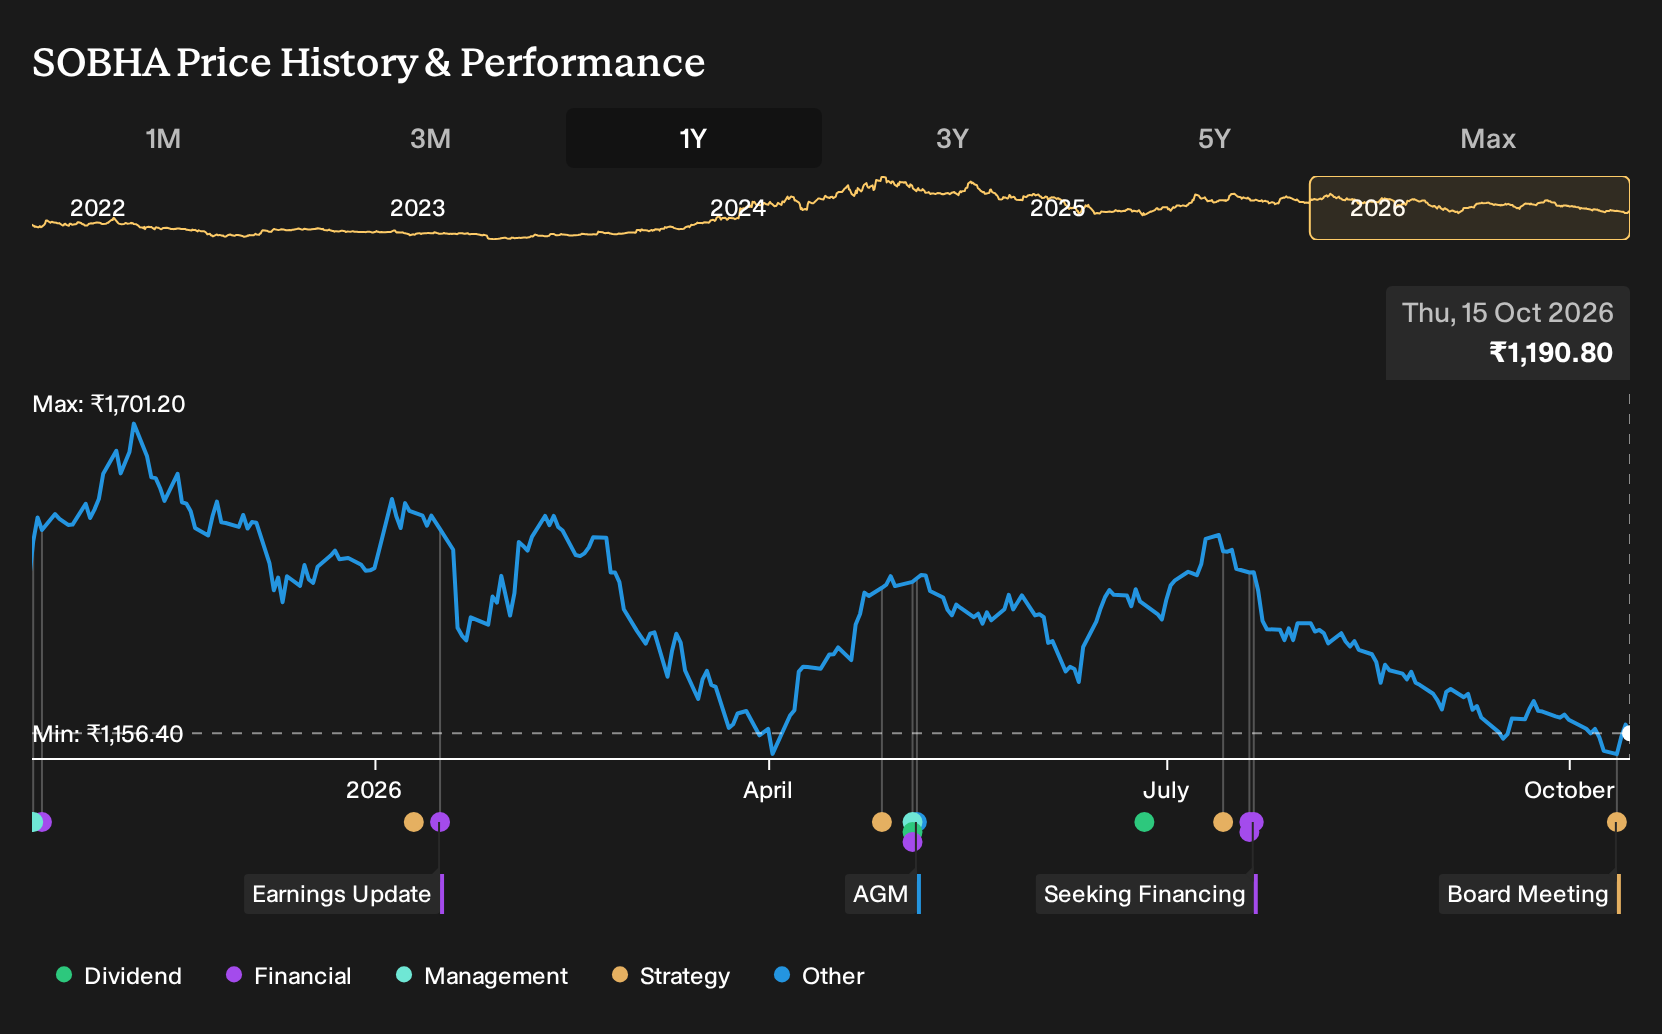
Sobha reported higher revenue and a stronger net margin in Q1 2027 compared with Q1 2026, yet the share price went the other way. Investors who held Sobha over the past year are down 22.7%, including dividends. That gap between sturdier recent results and a weaker return raises an obvious question. If you had been deciding whether to buy on 15 October 2025, what did the available information really suggest about this risk?
If the move has made Sobha harder to judge, start where the gap is still open and scan 198 high quality undervalued stocks.
The Two Sobha Stories Investors Were Arguing About
The shares cost ₹1,507 at the start of the period, and Sobha sat between two very different but plausible stories about what came next.
On the bullish side, a Fair Value of ₹2,459, the price implied if rapid growth played out, leaned on premium housing demand and quicker project launches in places like Greater Noida, with project EBITDA margins around 33% as a key support.
The bearish view anchored around a Fair Value of ₹1,200, an implied price if things went less well, stressing heavy exposure to metros such as Bengaluru and NCR and the risk that oversupply and saturated urbanization would restrain pricing power.
What The Results Changed For Sobha
The clearest fact was Sobha’s reported Q1 2027 jump in both revenue and profit versus Q1 2026. Net margin moved from 1.6% to 4.0%, which gave fresh support to the optimistic story that highlighted stronger profitability. The cautionary case was not invalidated, because one quarter of better margins does not settle longer term concerns about debt, costs, or market concentration.
The key lesson is simple. When a property developer like Sobha is presented as a margin expansion story, it is important to keep checking whether net margin and absolute earnings in later filings are actually tracking those promises.
What Sobha’s Current Price Already Assumes
Sobha trades at ₹1,191 today, after the share price declined about 22.7% over the past year. The selected Narrative still places its Fair Value above that level, based on internal cash generation, launch volume and a thick pipeline of contracted but not yet recognized revenue.
That view leans heavily on Sobha converting its large unrecognized order book into cash while keeping project launches on schedule so guided margins remain realistic.
"The current narrative that Sobha is undervalued implies that the share price does not fully reflect the net cash balance sheet, the large unrecognized revenue book of around INR 20,553 crores with at least 30% expected EBITDA margins, and management’s target of around INR 2,000 crores in annual operating cash flow."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
One Step Beyond Sobha
Sobha keeps pulling you back to concrete assets you can see. Towers, plots, finished apartments.
Real estate buyers and lenders still need something less visible. They lean on accurate data, benchmarks and marketplaces to decide what those towers are worth.
One specialist business focuses on that information layer for property. It tracks commercial buildings, housing markets, hotel performance and even loan portfolios.
Its software and portals help users compare rents, test prices and close deals. As more decisions move online and into models, that quiet data spine can matter a lot more.
One Narrative has already put a figure on it. → Uncover the company trading 14% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com