


Sonova Holding (SWX:SOON) has put its AI-heavy Roger On Sphere microphone and Integro CI cochlear implant system in the spotlight at the EUHA congress, giving investors fresh product news to assess.
That EUHA showcase lands at a time when Sonova Holding’s share price has climbed to CHF274.2. The company has recorded a strong 30-day share price return of 20.16% and a 90-day gain of 33.50%, while the 1-year total shareholder return of 28.51% points to momentum that has strengthened in recent months but still sits against a weaker 5-year total shareholder return, which declined 19.88%.
Scan beyond Sonova Holding and see how other hearing care and AI-focused peers are moving by checking our curated list of 125 healthcare AI stocks.
Sonova Holding now pairs fresh AI products with a share price that has run hard in recent months. The real test is whether that stronger story still lines up with sensible valuation.
Most Popular Narrative: 10% Overvalued
Against the latest close at CHF274.2, the most followed narrative pegs Sonova Holding's fair value nearer CHF250, using a 4.4% discount rate that keeps expectations grounded in its current earnings profile.
The combination of the CHF 90 million operations savings program, the reduction in Swiss franc denominated costs and the divestment of the lower margin Consumer Hearing business is set up to support the guided 7% to 12% core EBIT CAGR and further improve net margins.
See why 26 investors see Sonova Holding as 10% overvalued.
Result: Fair Value of CHF250 (OVERVALUED)
Still, the narrative around Sonova Holding can unravel quickly if FX pressure persists or Cochlear Implants in Europe face further pricing or reimbursement hits.
Find out about the key risks to this Sonova Holding narrative.
Another View: Sonova Holding Through The P/E Lens
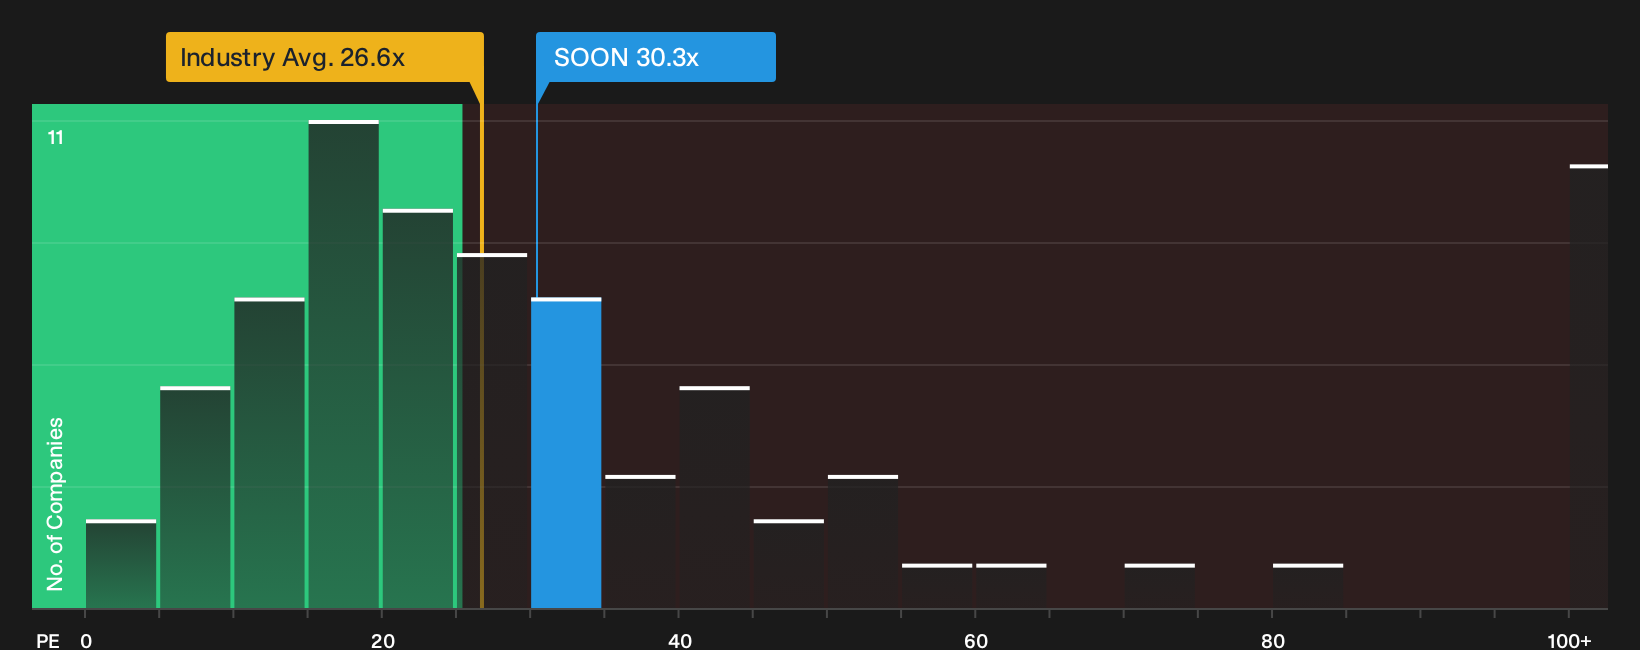
There is a very different picture when you look at Sonova Holding through its P/E ratio instead of that CHF250 fair value narrative. The stock trades on 30.3x earnings, which is lower than peer averages at 48.9x and close to a fair ratio of 31.1x, yet still above the wider European medical equipment group at 26.9x. Does that mix of relative richness to the sector and discount to peers and fair ratio signal more room to run or limited upside from here?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Sonova Holding is clearly split, with valuation signals pulling in different directions even as product news stays front and center. If you want to move quickly and build your own take rather than rely on any single storyline, review the 2 key rewards.
Looking for more investment ideas beyond Sonova Holding?
Do not stop at one opportunity. Use the Simply Wall St screener to quickly surface fresh stock ideas that match the kind of portfolio you actually want to build.
- Target potential mispricing by scanning a focused set of companies that screen as 198 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for businesses on the list of solid balance sheet and fundamentals (202 results).
- Hunt for future leaders early by checking the 613 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com