


Mani entered this Q4 2026 report wearing the badge of a high quality Japanese medical equipment specialist, with a premium valuation to match. The stock closed today at ¥1,558, with recent returns modest over one month and slightly weaker over three months, which signals expectations were already well set.
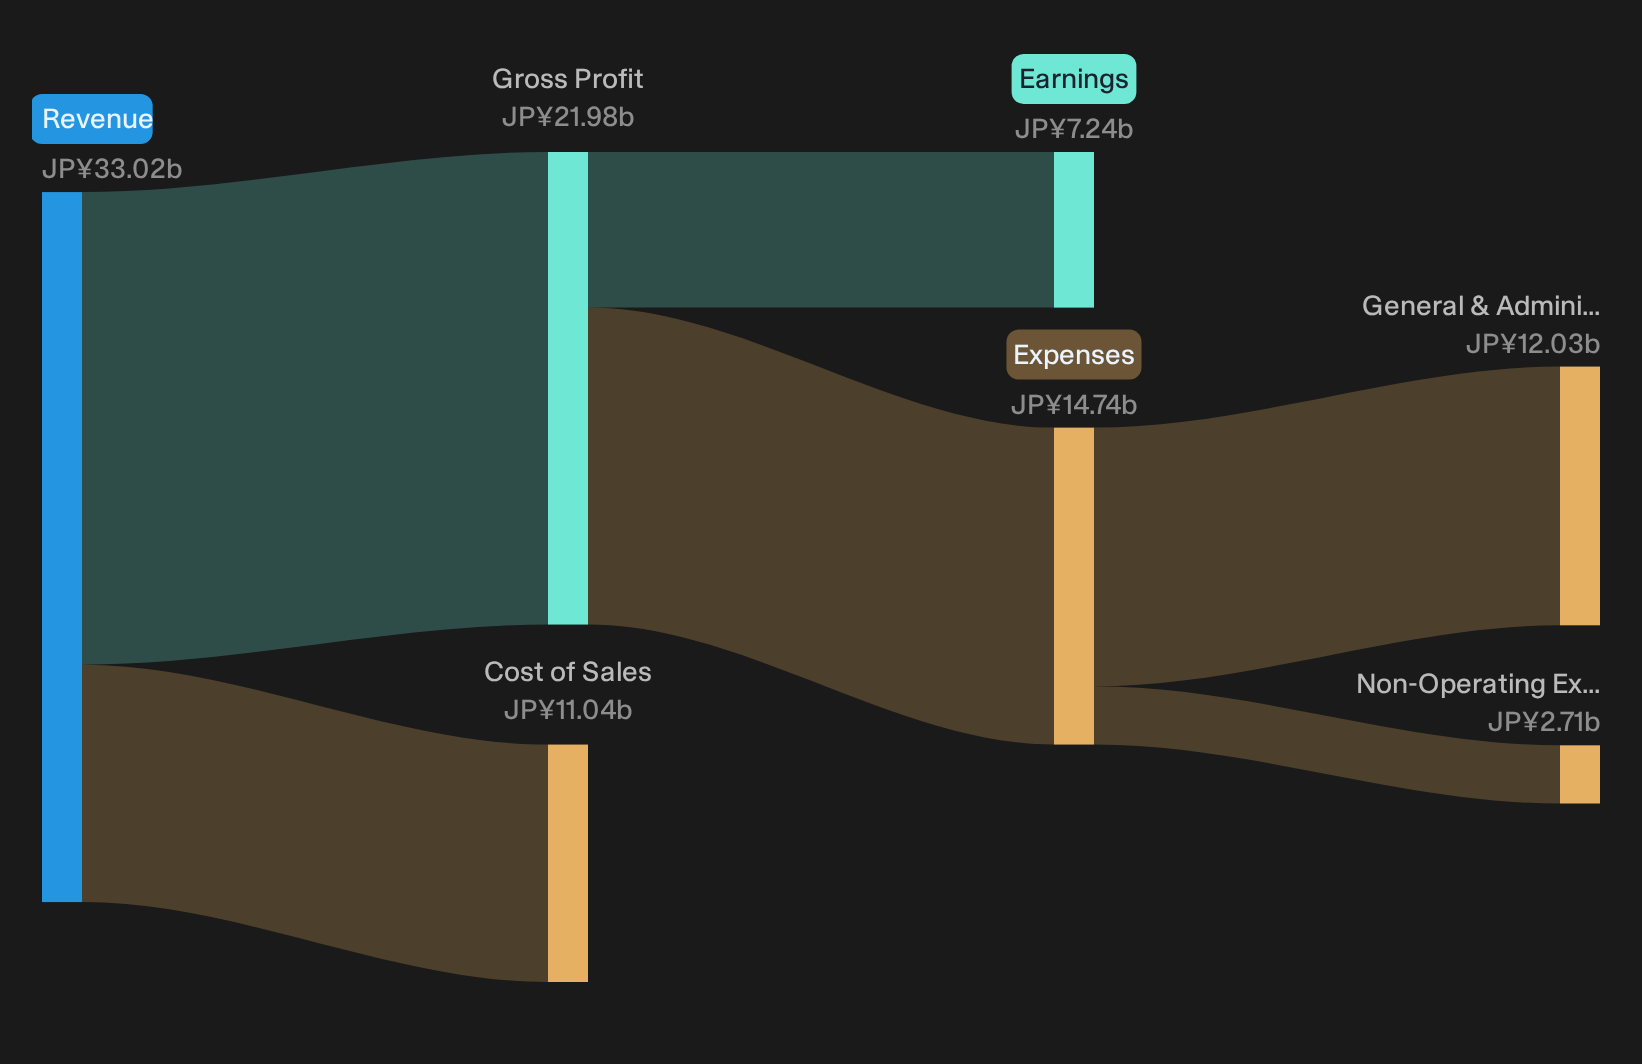
The fresh numbers tell a more nuanced story. Quarterly revenue reached ¥8,622m while basic earnings per share landed at ¥16.19. The tension sits in profitability. Net income of ¥1,595m continues to support solid trailing twelve month earnings. However, the sequential step down in quarterly EPS keeps the focus firmly on margin pressure rather than top line momentum.
Love Mani's premium positioning and steady earnings base, but uneasy about the squeeze on quarterly profitability and margins. Compare that setup with our list of solid balance sheet and fundamentals stocks (21 results).
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs. Q4 2025): ¥8,622m vs. ¥7,688m (up about 12%)
- Net Income (Q4 2026 vs. Q4 2025): ¥1,595m vs. ¥389m (very large year on year increase, over 4x)
- Basic EPS (Q4 2026 vs. Q4 2025): ¥16.19 vs. ¥3.95 (very large year on year increase, over 4x)
- Net Profit Margin (TTM 2026 vs. TTM 2025): 21.9% vs. 15.5% (margin higher year on year)
Earnings tell you how Mani did this quarter, but investors who care about valuation often focus on the cash that actually comes through the business. Based on Mani's cash flows alone, the stock could be a modest 5% overvalued.
Mani’s Growth Story Clears Key Early Hurdles
The bullish argument around Mani hinges on product and business model shifts translating into higher quality earnings rather than just headline growth.
"Transformation of MMG in Germany from a highly customized OEM supplier to a global branded product business using Mani’s existing export network, combined with a stated goal for a 10% operating income margin by fiscal year 2029, creates a path for higher consolidated operating margins and earnings."
Current results already line up with that roadmap. Group net profit margin on a trailing basis is 21.9% compared with 15.5% a year earlier, so profitability is moving toward the higher consolidated level this pivot is meant to support.
The price and this Narrative do not agree. → Uncover what this Narrative says Mani is actually worth.
Mani Bear Case Hinges On Execution Risk
For the cautious view on Mani, the core worry is that the manufacturing upgrade cycle adds cost and complexity without yet earning its keep.
"The transfer of automation from the Hanaoka smart factory to China and Vietnam is intended to compress launch timelines and manage labour costs. However, execution setbacks or slower scale up across multiple sites could weaken the benefit of advanced manufacturing and keep group operating margins under pressure."
Recent Q4 figures show quarterly EPS easing even as trailing profitability looks healthy. That mix points to some near term squeeze consistent with this concern, while the modest upward tweak to full year guidance shows no clear evidence yet that scale benefits are fully landing.
Hunt For Mispriced Earnings Power
Mani’s latest quarter highlights how earnings quality and near term margin pressure can collide in one story. The real opportunity sits in stocks that could be undervalued before the market catches up.
- Company 1 - 34% below our estimate - sells low code workflow tools firms adopt once email and spreadsheets can no longer handle cross team processes.
- Company 2 - 19% below our estimate - develops income producing real assets that bundle solar output, warehouses and accommodation into long term contracted cash flows.
- Company 3 - 20% below our estimate - supplies grinding and ceramics components customers need to keep upgrading precision manufacturing lines and electronic materials capacity.
That is three of the list. See every one of the 14 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com