


Hammerson (LSE:HMSO) moved into focus after the group confirmed Gina Szymanski will become Chief Financial Officer and join the board, a leadership shift that investors are now weighing against existing performance metrics.
Recent trading has been mixed for Hammerson, with the 7-day share price return of 6.28% and 1-day move of 2.03% contrasting with a 90-day share price decline of 8.31%. At the same time, the 1-year total shareholder return of 21.25% and 3-year figure of 74.82% indicate stronger longer term gains that frame this CFO appointment as another potential shift in how investors assess risk and opportunity around the business.
Scan how investor sentiment around Hammerson compares with other real estate plays by checking the hand picked list of solid balance sheet and fundamentals (9 results).
After a sharp 1-week rebound and a solid 3-year run, Hammerson leaves investors with a tougher call. Is most of the easy upside already in the rear view, or does the current valuation still leave meaningful headroom?
Most Popular Narrative: 13% Undervalued
Against a last close of £3.42, the most followed narrative puts Hammerson’s fair value at £3.94, which raises the question of whether recent price strength has fully captured the latest assumptions on earnings quality, capital allocation, and asset recycling.
Asset recycling and disciplined capital allocation (including monetizing strategic land at premiums to book and rotating out of lower-yielding assets into high-yielding flagship locations) are reducing leverage, lowering interest costs, and supporting margin expansion and long-term earnings resilience.
Investment in proprietary AI analytics and data-driven leasing is improving tenant mix, driving higher sales densities for occupiers, leading to sustained like-for-like rental growth and enhancing operating leverage as platform scale increases, positively impacting net margins and earnings scalability.
Find out how 7 investors see Hammerson as 13% undervalued.
Result: Fair Value of £3.94 (UNDERVALUED)
Still, Hammerson’s high leverage and heavy redevelopment spend mean that any setback on leasing or project delivery could quickly challenge the upbeat valuation story.
Find out about the key risks to this Hammerson narrative.
Another View On Hammerson’s Valuation
The SWS DCF model paints a very different picture for Hammerson. On this framework, the current share price of £3.42 sits well above an estimated future cash flow value of £0.67. This screens as clearly overvalued and places more emphasis on execution risk than the popular 13% undervalued narrative. Which story do you trust more when real cash generation is the anchor?
Look into how the SWS DCF model arrives at its fair value.
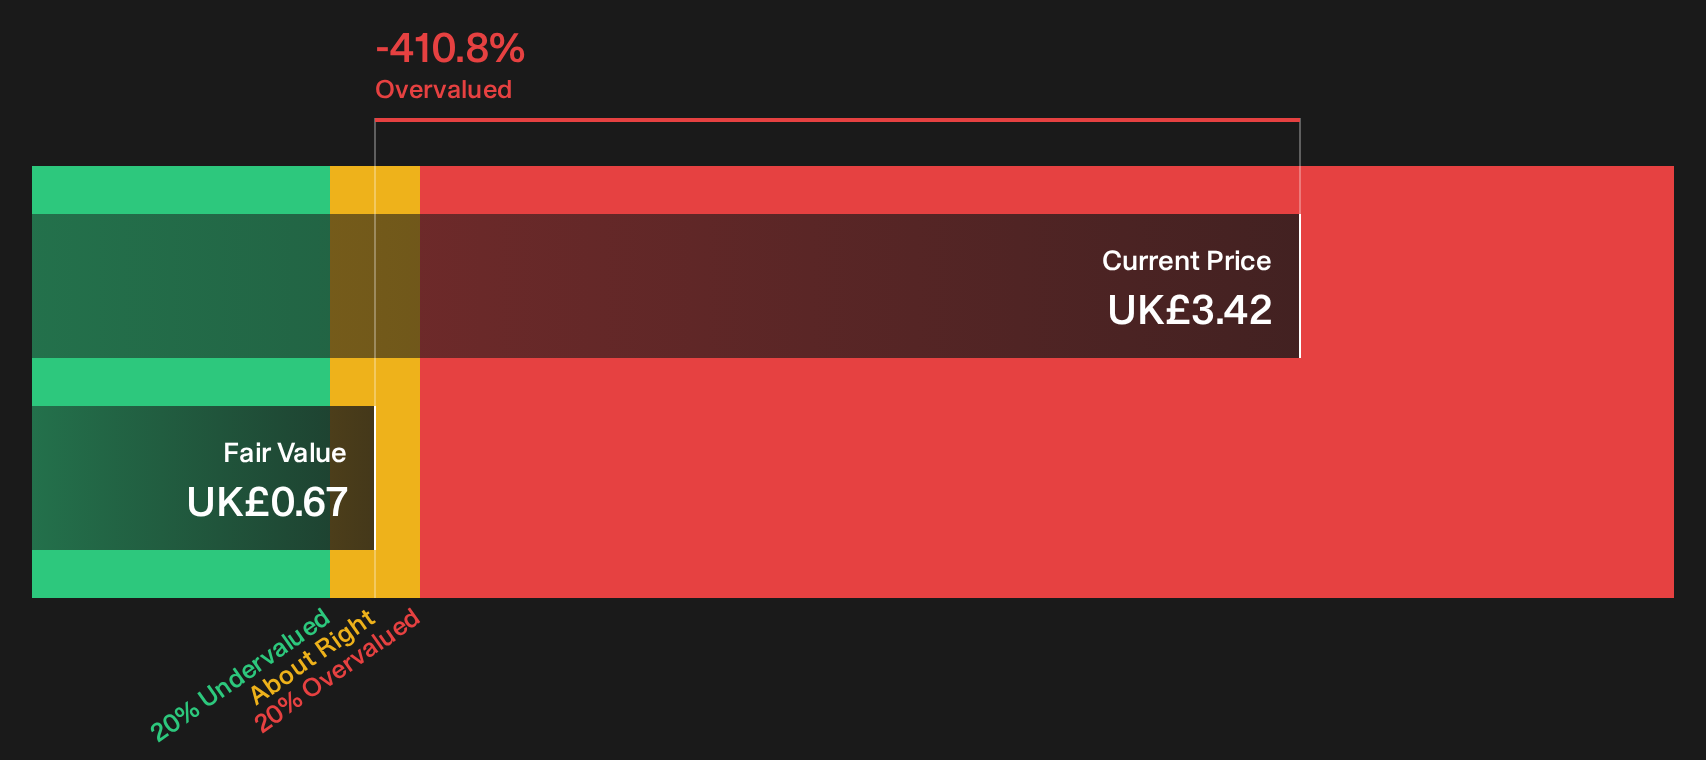
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hammerson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 9 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Hammerson’s value story and risk profile make this a judgment call, so move quickly to review the data and weigh both sides with the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Hammerson?
Hammerson offers one angle on the real estate story, but your next strong opportunity may sit in a very different corner of the market.
- Target stability with 4 resilient stocks with low risk scores that focus on resilient businesses where balance sheet strength and lower risk scores do more of the heavy lifting for you.
- Hunt for value using 5 high quality undiscovered gems that spotlight quality fundamentals in companies that many investors may not be watching yet.
- Build a future income stream through 4 dividend fortresses that highlight higher yielding stocks designed for investors who care about cash in hand.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com