


In October 2026, the global markets have been navigating a complex landscape marked by volatility in AI-related stocks, geopolitical tensions in the Middle East affecting oil prices, and mixed signals from major economic indicators. While large-cap indices like the S&P 500 have shown gains, small-cap stocks represented by the Russell 2000 Index have faced challenges amid these broader market dynamics. In such an environment, identifying potentially undervalued small-cap companies with insider activity can be an intriguing strategy for investors looking to capitalize on opportunities that may not yet be fully recognized by the market.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Q Technology (Group) | 3.3x | 0.2x | 46.83% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.9x | 0.9x | 39.77% | ★★★★★☆ |
| Timbercreek Financial | 17.0x | 9.9x | 37.46% | ★★★★☆☆ |
| Centurion | 15.7x | 3.0x | 21.11% | ★★★★☆☆ |
| Franchise Brands | 26.8x | 2.0x | 48.16% | ★★★★☆☆ |
| Pizza Pizza Royalty | 11.8x | 9.0x | 39.19% | ★★★★☆☆ |
| Sagicor Financial | 6.8x | 0.5x | -76.84% | ★★★★☆☆ |
| Yellow Pages | 8.3x | 0.8x | 29.83% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -225.76% | ★★★☆☆☆ |
| Linc | 11.9x | 12.4x | 35.76% | ★★★☆☆☆ |
Underneath we present a selection of stocks filtered out by our screen.
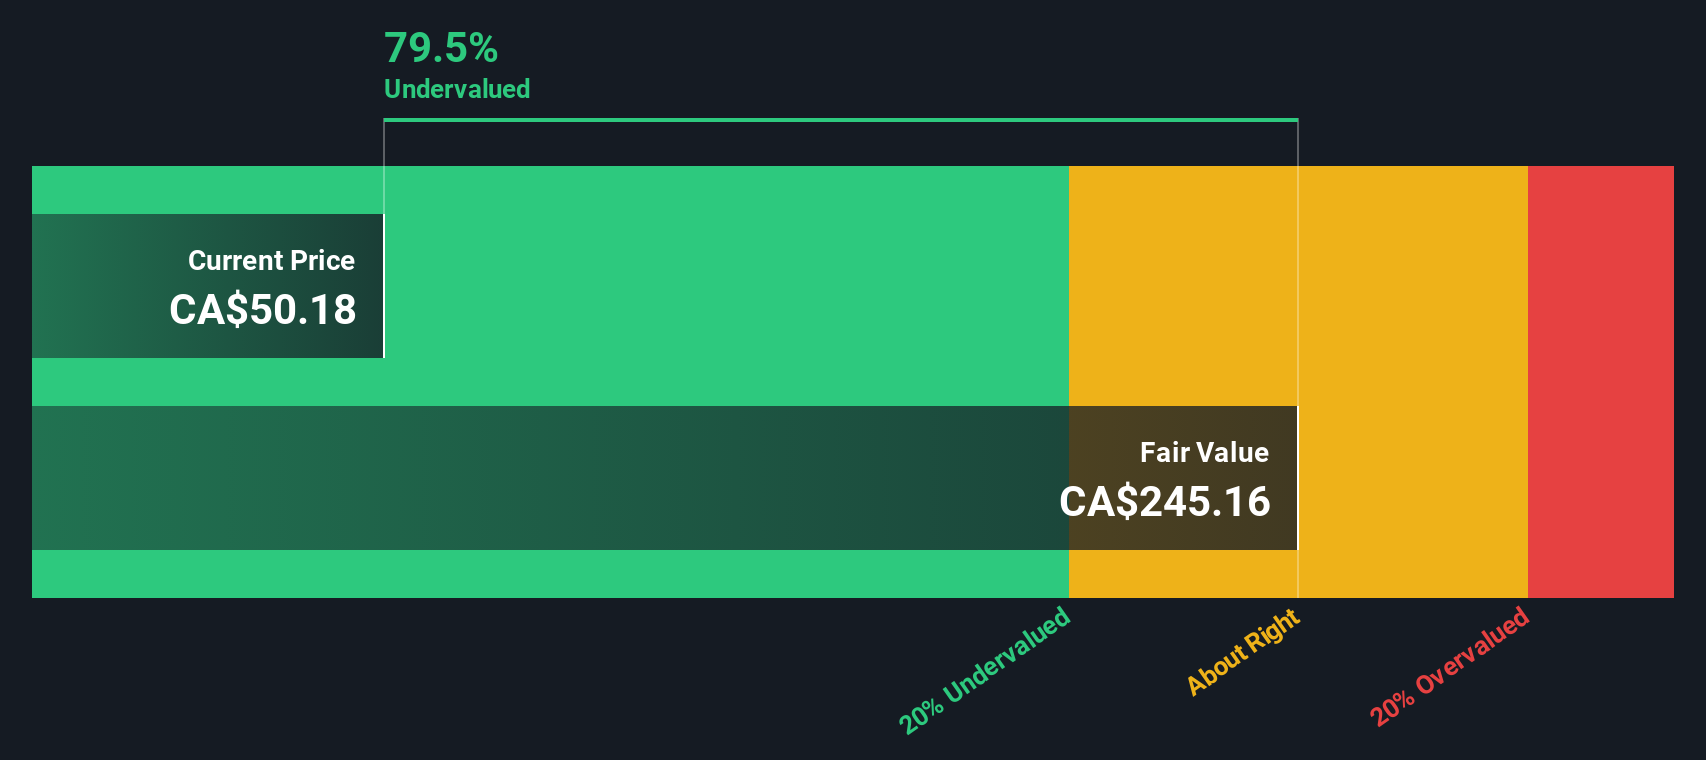
Calian Group (TSX:CGY)
Simply Wall St Value Rating: ★★★★★☆
Overview: Calian Group is a Canadian company that provides diverse services in healthcare, communications, learning, and cybersecurity with a market cap of approximately CA$1.2 billion.
Operations: Calian Group's revenue model shows a notable increase in gross profit margin, reaching 34.32% as of June 2026. The company has shown a steady rise in revenue, achieving CA$870.28 million by the same period. Operating expenses have also increased over time, with general and administrative expenses being a significant component of these costs.
PE: 25.5x
Calian Group, a small-cap company, recently secured a CAD 47 million contract with NATO's Joint Warfare Centre, enhancing its reputation as a trusted partner in defence training. Despite having higher-risk funding due to reliance on external borrowing, the company demonstrates strong earnings growth potential with third-quarter sales rising to CAD 230.4 million from CAD 192.22 million last year and net income reaching CAD 5.94 million from CAD 0.59 million previously. No insider confidence was noted through share purchases this period, but strategic alliances like the Northstar Defence Lab position Calian for future growth in integrated defence solutions and operational readiness initiatives across Canada and allied nations.
- Get an in-depth perspective on Calian Group's performance by reading our valuation report here.
Assess Calian Group's past performance with our detailed historical performance reports.
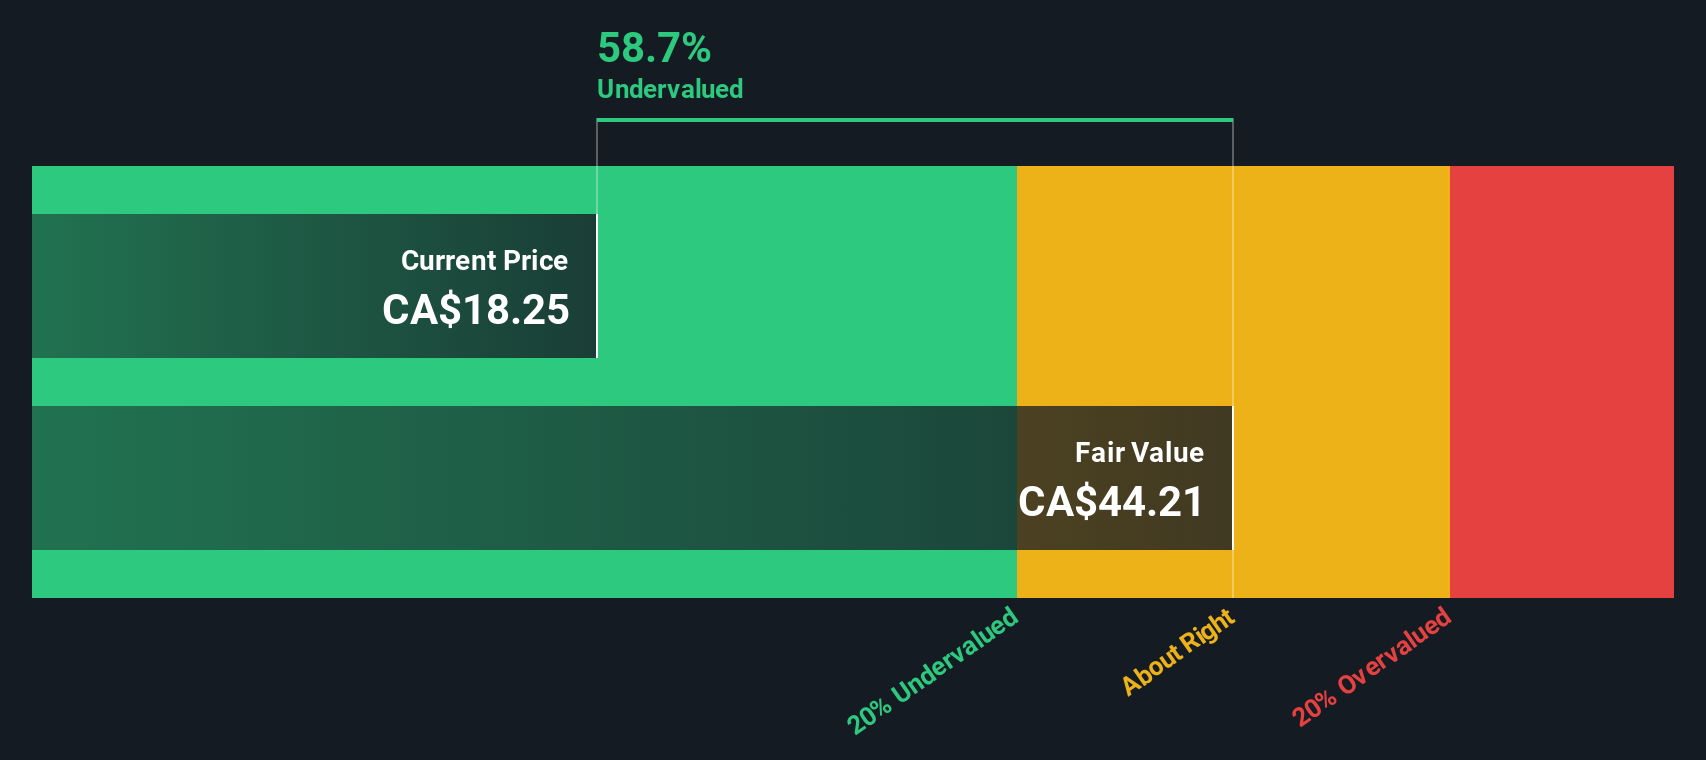
Flagship Communities Real Estate Investment Trust (TSX:MHC.UN)
Simply Wall St Value Rating: ★★★★★☆
Overview: Flagship Communities Real Estate Investment Trust focuses on owning and operating manufactured housing communities, with a market cap of approximately $0.52 billion.
Operations: Flagship Communities Real Estate Investment Trust generates its revenue primarily from residential real estate investments, with recent quarterly revenue reaching $113.85 million. The company has seen variations in its net income margin, which was 0.85% as of the latest period. Gross profit margins have fluctuated over time, most recently recorded at 65.37%. Operating expenses and non-operating expenses are key components affecting profitability within their financial structure.
PE: 4.3x
Flagship Communities Real Estate Investment Trust, a player in the affordable housing sector, recently expanded its footprint in Kentucky with a $2 million acquisition. Despite facing earnings pressure, with net income dropping to $4.24 million in Q2 2026 from $35.09 million the previous year, insider confidence remains evident through share purchases over recent months. The REIT's commitment to increasing cash distributions for six consecutive years underscores its focus on returning value to unitholders amidst growth challenges and high-risk funding reliance.
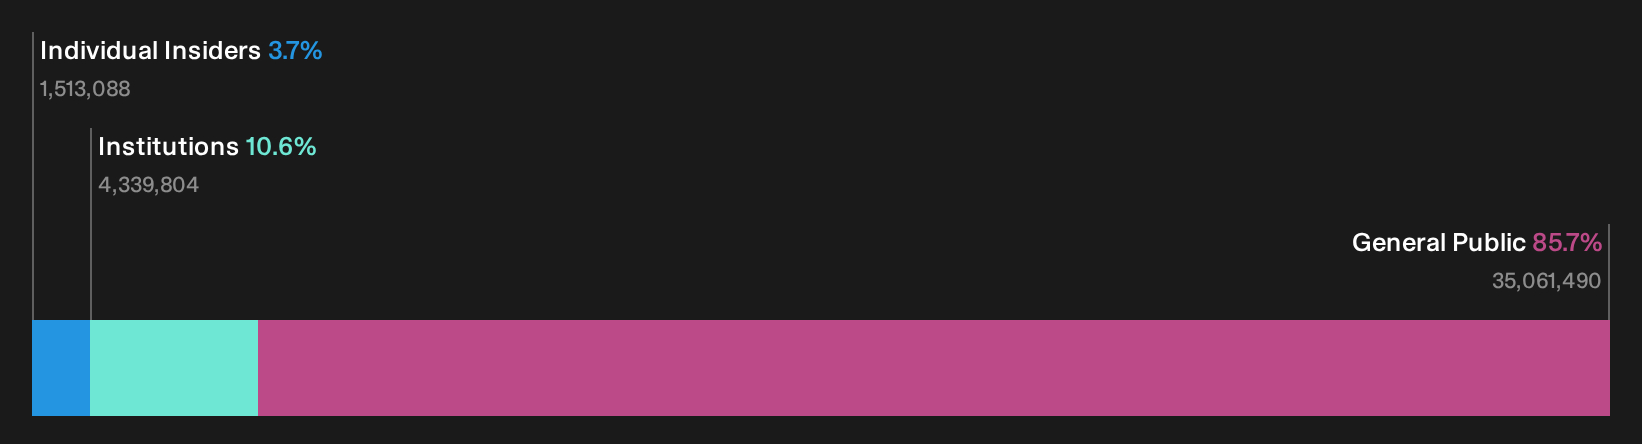
MCAN Mortgage (TSX:MKP)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: MCAN Mortgage is a Canadian company that operates in the financial services sector, primarily focusing on mortgage lending, with a market capitalization of approximately CA$0.57 billion.
Operations: The company generates revenue primarily from its financial services, specifically in the mortgage segment, with a recent revenue of CA$148.99 million. The gross profit margin has reached 100% in recent periods, indicating no cost of goods sold is recorded. Operating expenses have been significant, with general and administrative expenses comprising the bulk at CA$64.77 million in the latest period. Net income has been robust, reflecting a net income margin of 57.14%.
PE: 10.3x
MCAN Mortgage, with a focus on external borrowing for funding, has shown insider confidence through Independent Director Brian Chu's purchase of 5,700 shares valued at approximately C$120,762. Despite higher risk funding sources, the company reported solid growth in net income for Q2 2026 at C$24.01 million compared to C$20.19 million last year and declared a regular cash dividend of C$0.43 per share for Q3 2026. Revenue is expected to grow by 5.2% annually, indicating potential value amidst its small-cap peers.
- Delve into the full analysis valuation report here for a deeper understanding of MCAN Mortgage.
Evaluate MCAN Mortgage's historical performance by accessing our past performance report.
Turning Ideas Into Actions
- Click this link to deep-dive into the 118 companies within our Undervalued Global Small Caps With Insider Buying screener.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com