


- Marvell Technology recently unveiled new 224G Alaska E retimers, second generation Alaska A AEC DSPs and six channel Structera X CXL memory expanders, while teaming with Microsoft and Oracle on an Open Compute Project effort to standardize server level hardware security modules.
- The cluster of product launches and security collaboration underscores how Marvell Technology is trying to address AI data center pain points in bandwidth, memory capacity, power efficiency and cryptographic protection directly at the rack and server level.
- Next, the focus shifts to what this means for Marvell Technology's investment narrative as hotter US inflation pressures AI infrastructure funding.
Scan beyond Marvell Technology and explore other potential AI infrastructure beneficiaries with our hand picked 94 AI infrastructure stocks that are trying to solve similar bottlenecks in bandwidth, memory and power efficiency.
Marvell Technology Investment Narrative Recap
To own Marvell Technology, you effectively need to believe its data center and AI infrastructure roadmap can translate a US$12b FY27 and US$18b FY28 revenue ambition into durable earnings, even as mix shifts toward lower margin custom silicon. The key near term catalyst is execution on these AI programs against tight capacity, supplier prepayments and volatile customer ordering.
The main risk today is that this rapid pivot to AI hardware collides with funding pressure from higher rates and sentiment driven swings in AI spending. Recent Alaska connectivity and Structera X memory launches sharpen Marvell Technology’s positioning, but do not materially change that core execution versus demand risk equation yet.
Among the recent updates, the launch of the 224G Alaska E 3.2T retimer and second generation Alaska A 1.6T AEC DSP looks closest to the current AI connectivity catalyst. These parts directly target 200G per lane fabrics and 102.4T switches that underpin management’s expectations for rapid scaling in high speed copper and optical infrastructure tied to accelerators.
For you as a shareholder, the relevance is practical. The more Marvell Technology can prove these 3nm retimers and DSPs work across long reach copper, multiple protocols and dense AI racks, the more credible its FY27 and FY28 connectivity ramp appears. Execution risk stays real, from power and signal integrity challenges to hyperscaler qualification cycles.
What The Current Forecasts Assume For Marvell Technology
Analysts link the recent AI hardware releases to a steep financial ramp for Marvell Technology over the next few years. The consensus framework is simple for you as an investor. Forecasts point to revenue growing 47.5% each year over the coming three years, paired with an uplift in profit margins from 27.9% today to 31.7% by around 2029.
On the earnings line, the current analyst view anchors on a move from US$2.6b in earnings today to US$9.6b by about 2029. That jump would require roughly a 3.7x step up in profitability, even before factoring in that some forecasters only pencil in US$4.2b at the low end. Expectations also include share count rising about 3.4% per year for the next three years, which matters for anyone focusing on earnings per share rather than total profit.
Valuation assumptions around Marvell Technology are just as specific as the operational ones. To support the current analyst framework, the stock would need to transition from trading on a P/E of 90.4x today to 40.9x on the 2029 earnings estimate. That multiple sits below the cited US Semiconductor industry P/E of 52.4x, so the thesis builds in both higher earnings and a lower earnings multiple compared with today.
Marvell Technology's narrative projects US$30.4b revenue and US$9.6b earnings by 2029. This requires 47.5% yearly revenue growth and roughly a 3.7x earnings increase from US$2.6b today.
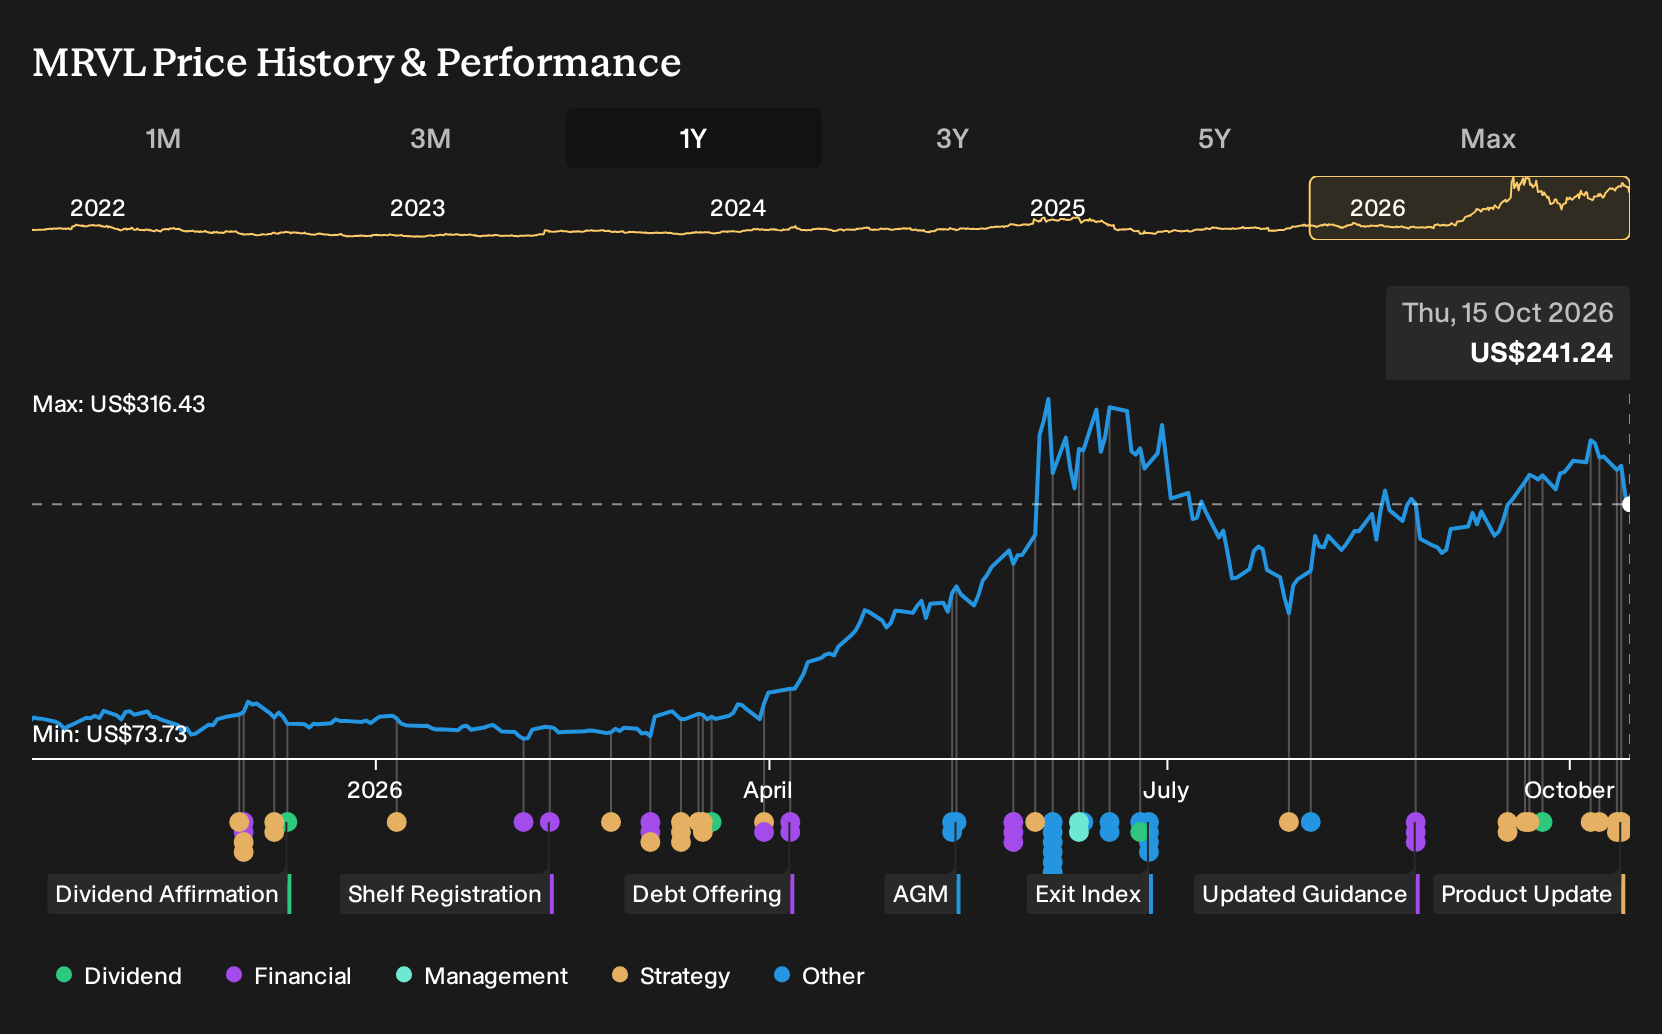
Uncover why Marvell Technology's fair value indicates a 22% potential upside to its current price, which could narrow quickly if earnings execution aligns with expectations.
Exploring Other Perspectives
One alternate story focuses on margin risk instead of connectivity upside. The most cautious analysts were assuming profit margins sliding to about 16.0% and earnings in 2029 closer to US$4.2b on roughly US$26.5b revenue. Those figures, set before this Marvell Technology product and security news, show how sharply views can differ. You can treat today’s announcements as a prompt to compare these contrasting scenarios yourself.
Explore 10 other Marvell Technology fair value estimates, including one that suggests as much as 42% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Marvell Technology research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Marvell Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marvell Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Marvell Technology?
If the Marvell Technology story has sharpened your thinking on AI hardware, it can help to compare it with other businesses that line up with your risk tolerance and income goals. The Simply Wall St Screener is built for that kind of side by side work so you can pressure test your thesis instead of relying on a single stock.
- If capital preservation is front of mind, filter for companies that screen well on balance sheet strength with our 32 resilient stocks with low risk scores and see which ones match your preferred risk profile.
- If you are hunting for resilient cash generators trading below what their fundamentals suggest, start with this 33 high quality undervalued stocks and see which businesses you want to research next.
- If quality and staying power matter more than brand recognition, widen your watchlist with a 20 high quality undiscovered gems that still show solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com