


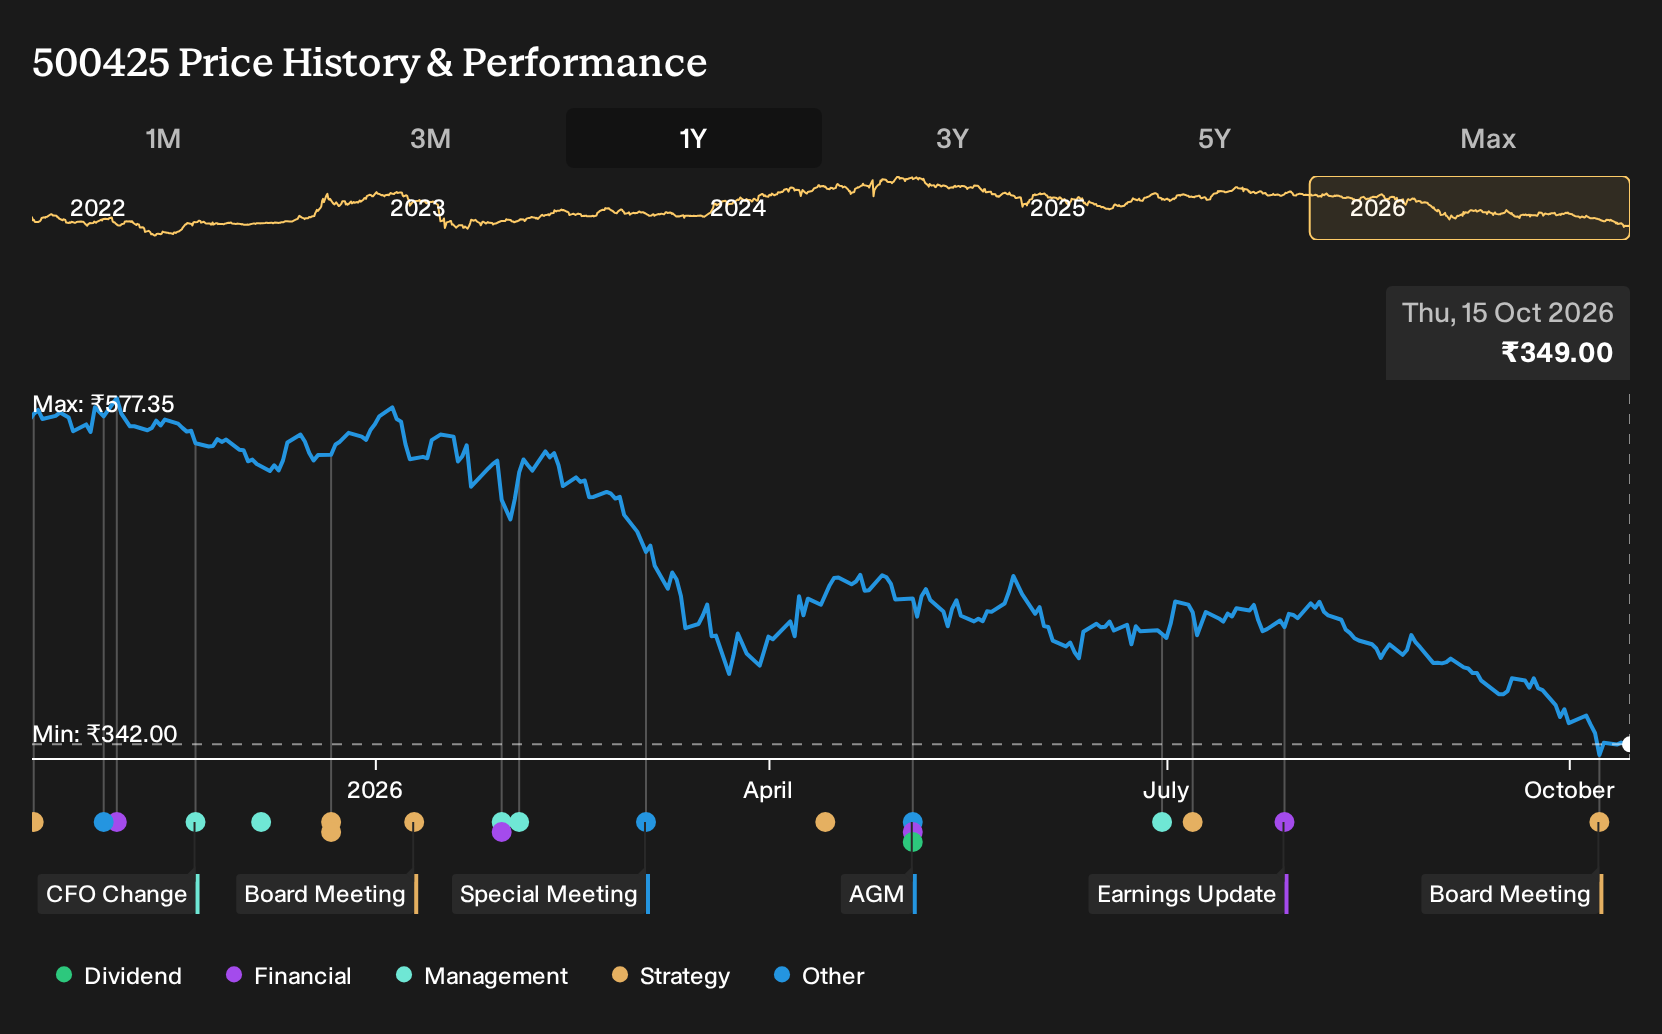
If you only looked at the crisp forecasts for Ambuja Cements in late 2025, the story sounded straightforward. Rapid urbanization, capacity additions and ESG credentials were all on the table. Holding Ambuja Cements over the past year would have meant a 38.4% loss, including dividends. Then Q1 2027 arrived with revenue and profit both lower than Q1 2026, and a thinner net margin. If you were deciding on 15 October 2025, what clues were visible that this gap could open up?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Ambuja Cements has already moved. See which of 196 high quality undervalued stocks still trade below our estimates.
The Two Ambuja Cements Stories Investors Had To Weigh
The shares cost ₹567 at the start of the period, and Ambuja Cements carried two very different stories that both sounded plausible.
The bullish narrative in September 2025 argued for a fair value of ₹654, built on revenue growth of 15.1% and an assumed future P/E of 37.1x over three years.
The bearish case in June 2025 pointed to a fair value of ₹378, focused on pressure from stricter environmental rules and rising raw material and carbon related costs.
What The Ambuja Cements Results Put To The Test
The clearest data point for Ambuja Cements was the Q1 2027 print. Revenue slipped to ₹95,000 million from ₹102,890.7 million a year earlier, while net income moved to ₹5,770 million from ₹7,878.8 million and net margin narrowed from 7.7% to 6.1%. That challenged the bullish story built on higher margins and a richer future P/E, and it leaned toward the cautious case.
The useful takeaway is simple. When a thesis leans heavily on margin resilience, treat net margin as the key checkpoint and test every new result against that single figure.
What The Fall In Ambuja Cements Now Asks You To Believe
Ambuja Cements now trades at ₹349 after falling 38.4% over the past year. The selected Narrative argues that its Fair Value sits above the current price, hinging less on breakneck expansion and more on disciplined cost per tonne and tighter control of new capacity.
For that decline to look like an opening rather than a warning, a buyer today would need to believe Ambuja Cements can actually deliver the planned structural cost savings while lifting utilization and mix quality at the acquired plants.
"The main thing that has to go right is execution on the moderated but still ambitious cost and efficiency program, which now targets about INR 250 per tonne of structural savings per year to hold FY27 cement cost near INR 4,250 per tonne and progress toward a longer run ambition of roughly INR 3,650 per tonne while lifting utilization and margins at Sanghi, Penna and Orient toward group levels."
The price and this Narrative do not agree. → Uncover what this Narrative says Ambuja Cements is actually worth
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 33% below our estimate - targets higher margin nutrition by expanding beyond dairy into specialized formulations and ingredients.
- Company 2 - 48% below our estimate - wins larger smart-technology and data-center build contracts as digital infrastructure projects accelerate.
- Company 3 - 43% below our estimate - shifts oncology software from one-off licenses to recurring support, maintenance and related service revenue.
Those are three of them. See all 202 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com