


Fresh equity overhang from Baidu’s new shelf registration
Baidu (NasdaqGS:BIDU) has filed a new shelf registration for up to US$2.88b of American Depositary Shares tied to an employee stock ownership plan, putting potential future equity issuance on investors’ radar.
Baidu’s share price has been under steady pressure, with a year to date share price return down 45.07% and a 1 year total shareholder return down 31.71%. The fresh US$2.88b shelf registration lands while momentum is already fading despite recent headlines around AI cloud growth and international expansion for Apollo Go.
Spot opportunities beyond Baidu by scanning a curated mix of beaten-down but financially solid tech players in our 33 high quality undervalued stocks that are poised for a potential sentiment shift.Baidu trades at a steep discount to analyst targets, yet the fresh US$2.88b shelf, weak advertising arm, and loss-making bottom line keep caution high. Is that gap mispricing, or is it a fair warning sign before looking at valuation?
Most Popular Narrative: 43% Undervalued
Baidu’s most followed narrative pegs fair value at $145.16 versus the recent $82.56 close. The story hinges on whether its AI ecosystem can justify that gap using an 11.08% discount rate.
The main thing that has to go right is that Baidu converts its AI leadership in cloud infrastructure, search monetisation and Apollo Go into sustained, profitable revenue that more than offsets pressure on traditional online marketing and higher AI investment.
See why 175 investors see Baidu as 43% undervalued.
Result: Fair Value of $145.16 (UNDERVALUED)
Still, the narrative can break if Baidu’s recent revenue decline and long lived asset impairments repeat, or if traditional online marketing weakness lasts longer than expected.
Find out about the key risks to this Baidu narrative.
Another View: Baidu on sales-based valuation
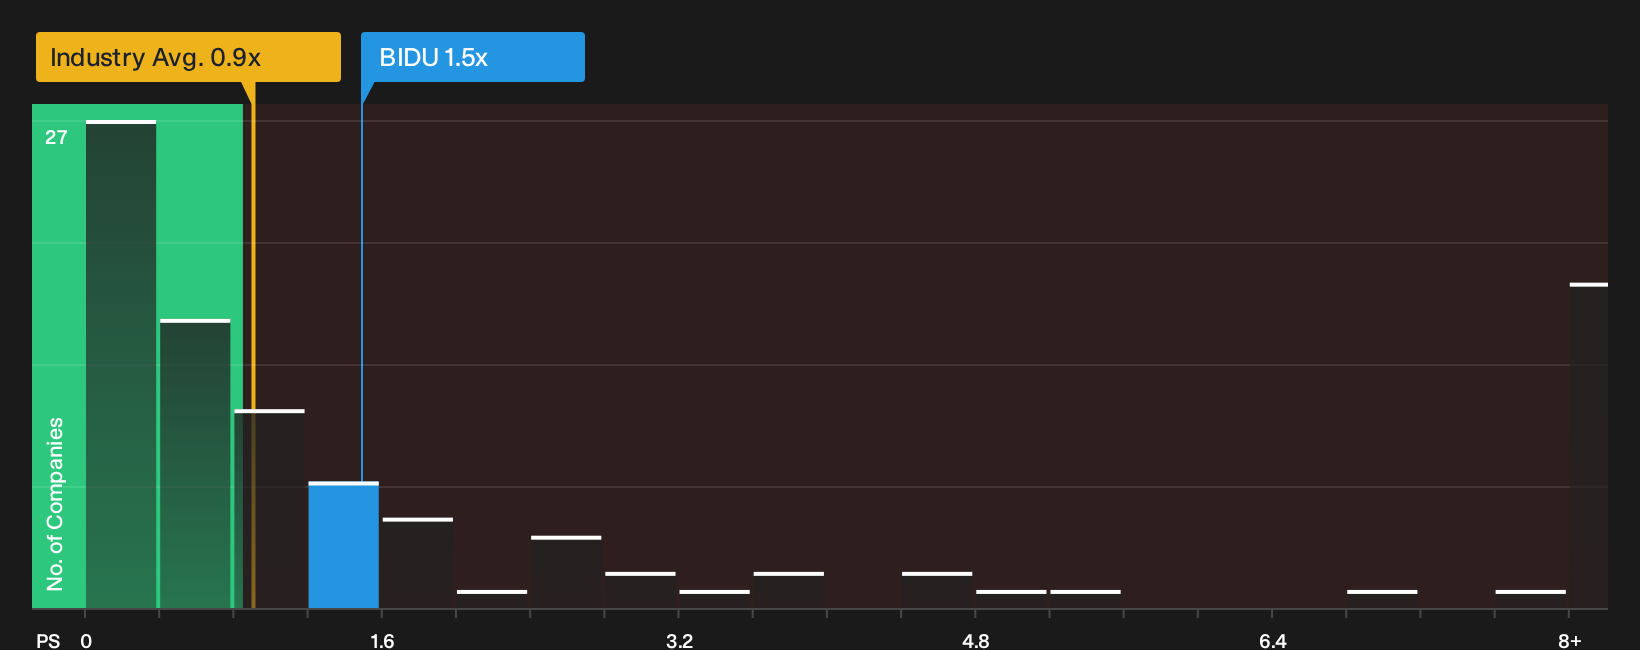
Analysts describe Baidu as materially undervalued on long term earnings potential, yet the current P/S suggests a more nuanced picture. The stock trades at 1.5x sales, which is expensive compared with the US Interactive Media and Services industry at 0.9x. It is, however, below direct peers at 4.6x and under a fair ratio estimate of 2.2x. This combination of a relative premium to the sector and a discount to peers raises a straightforward question: is this pricing a safety buffer, or a sign that investors still see substantial execution risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading the mix of discounts, fresh equity overhang, and execution risk around Baidu, it helps to inspect the numbers directly and decide what actually matters to you. Then put today’s pressure in context by weighing those concerns against 1 key reward
Looking for more investment ideas beyond Baidu?
Do not just stop at Baidu. Broaden your watchlist with other stocks that match your risk tolerance, income needs, and appetite for a potential rebound.
- Target potential mispricing by scanning a focused set of beaten down yet fundamentally strong opportunities through the 33 high quality undervalued stocks.
- Build steadier income potential by checking out companies in the 8 dividend fortresses that combine higher yields with robust payout support.
- Reduce portfolio stress by filtering for sturdier balance sheets and resilient fundamentals inside the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com